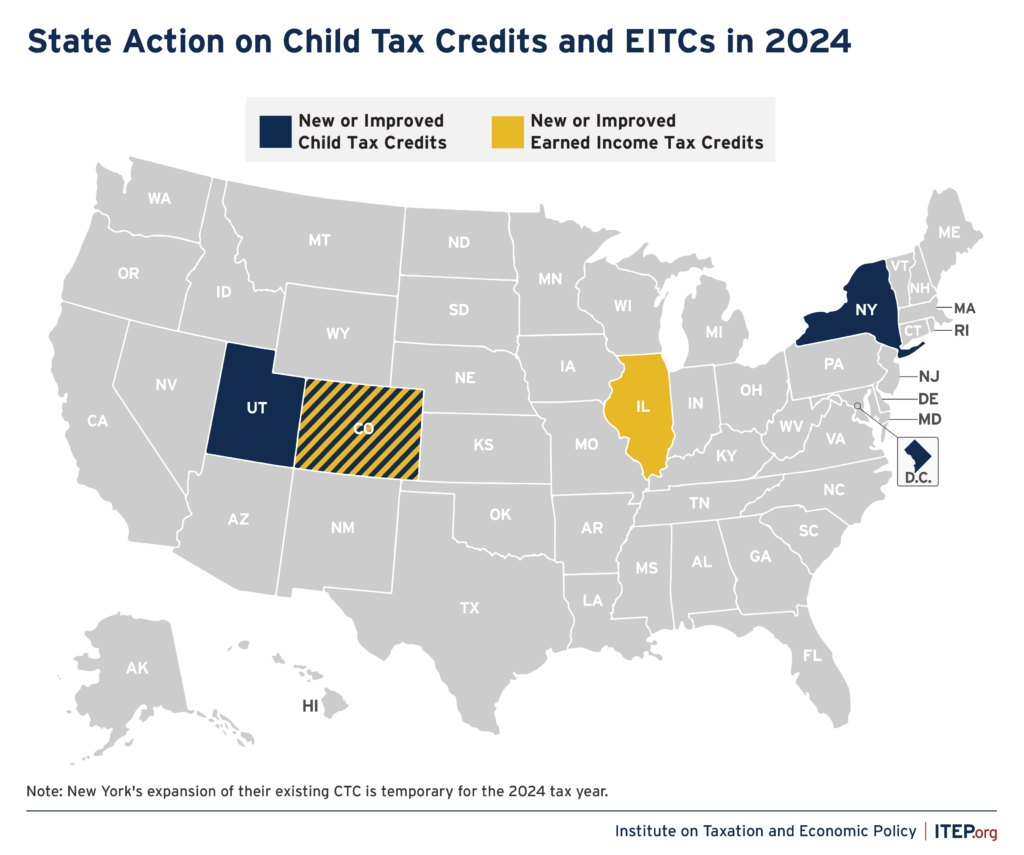
A child credit is a targeted government tax incentive or financial benefit designed to help families offset the rising costs of raising children, typically administered through annual tax filings or periodic advance payments. Qualifying parents and guardians must meet specific income thresholds, residency requirements, and dependency rules to claim the full amount available under current tax codes.
Families navigating the complexities of child-related tax benefits often encounter a labyrinth of evolving thresholds, strict identification requirements, and overlapping credit structures. Understanding how these financial mechanisms operate is essential for maximizing household budgets and maintaining compliance with tax authorities. Whether reviewing federal provisions or state-level supplements, knowing the operational mechanics ensures that eligible households do not leave vital financial support unclaimed.
Understanding the Framework of Child Credits
Child-related financial assistance generally takes the form of tax credits rather than standard deductions. Unlike a deduction, which merely reduces the amount of income subject to taxation, a credit provides a dollar-for-dollar reduction of your actual tax liability. This distinction is critical because credits can significantly lower tax burdens, and in certain configurations, yield a refund even if the taxpayer owes zero tax.
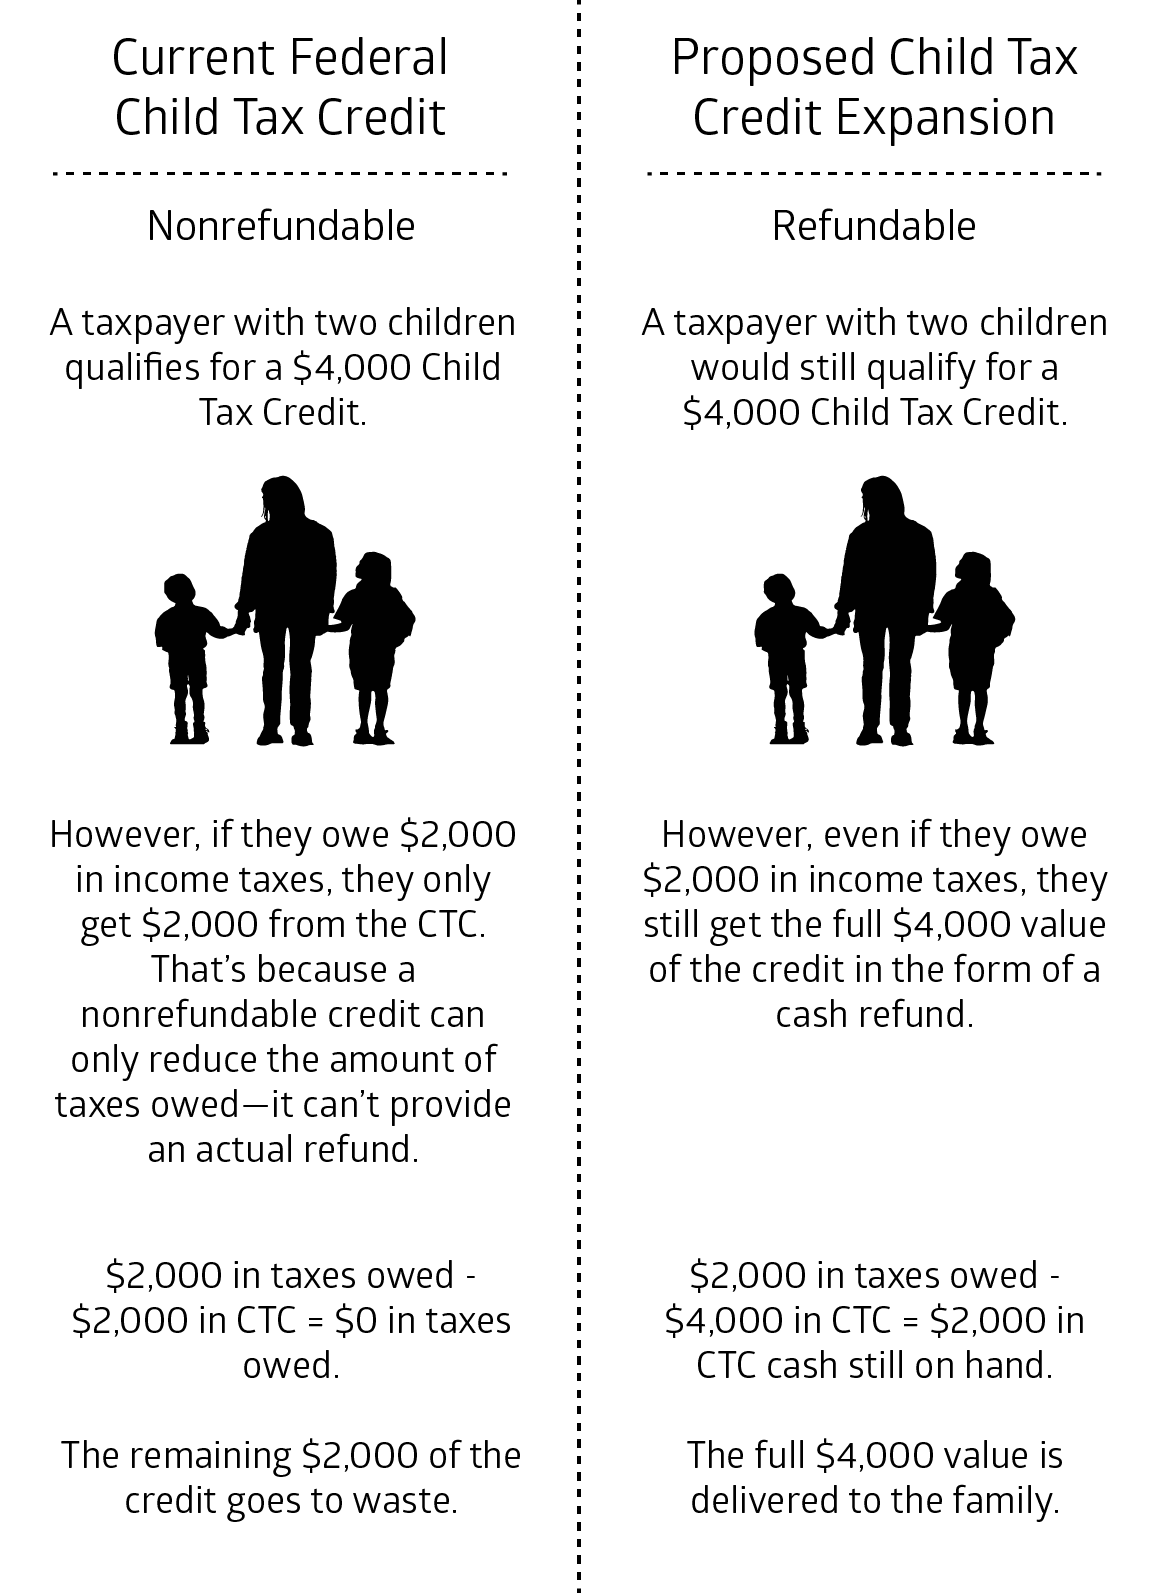
Most modern frameworks distinguish between non-refundable, partially refundable, and fully refundable credits. A non-refundable credit can reduce tax liability down to zero, but any excess credit value is lost. Conversely, a refundable or partially refundable credit allows claimants to receive the remaining balance as a direct cash refund. Governments structure these incentives to encourage workforce participation, alleviate child poverty, and support family stability.
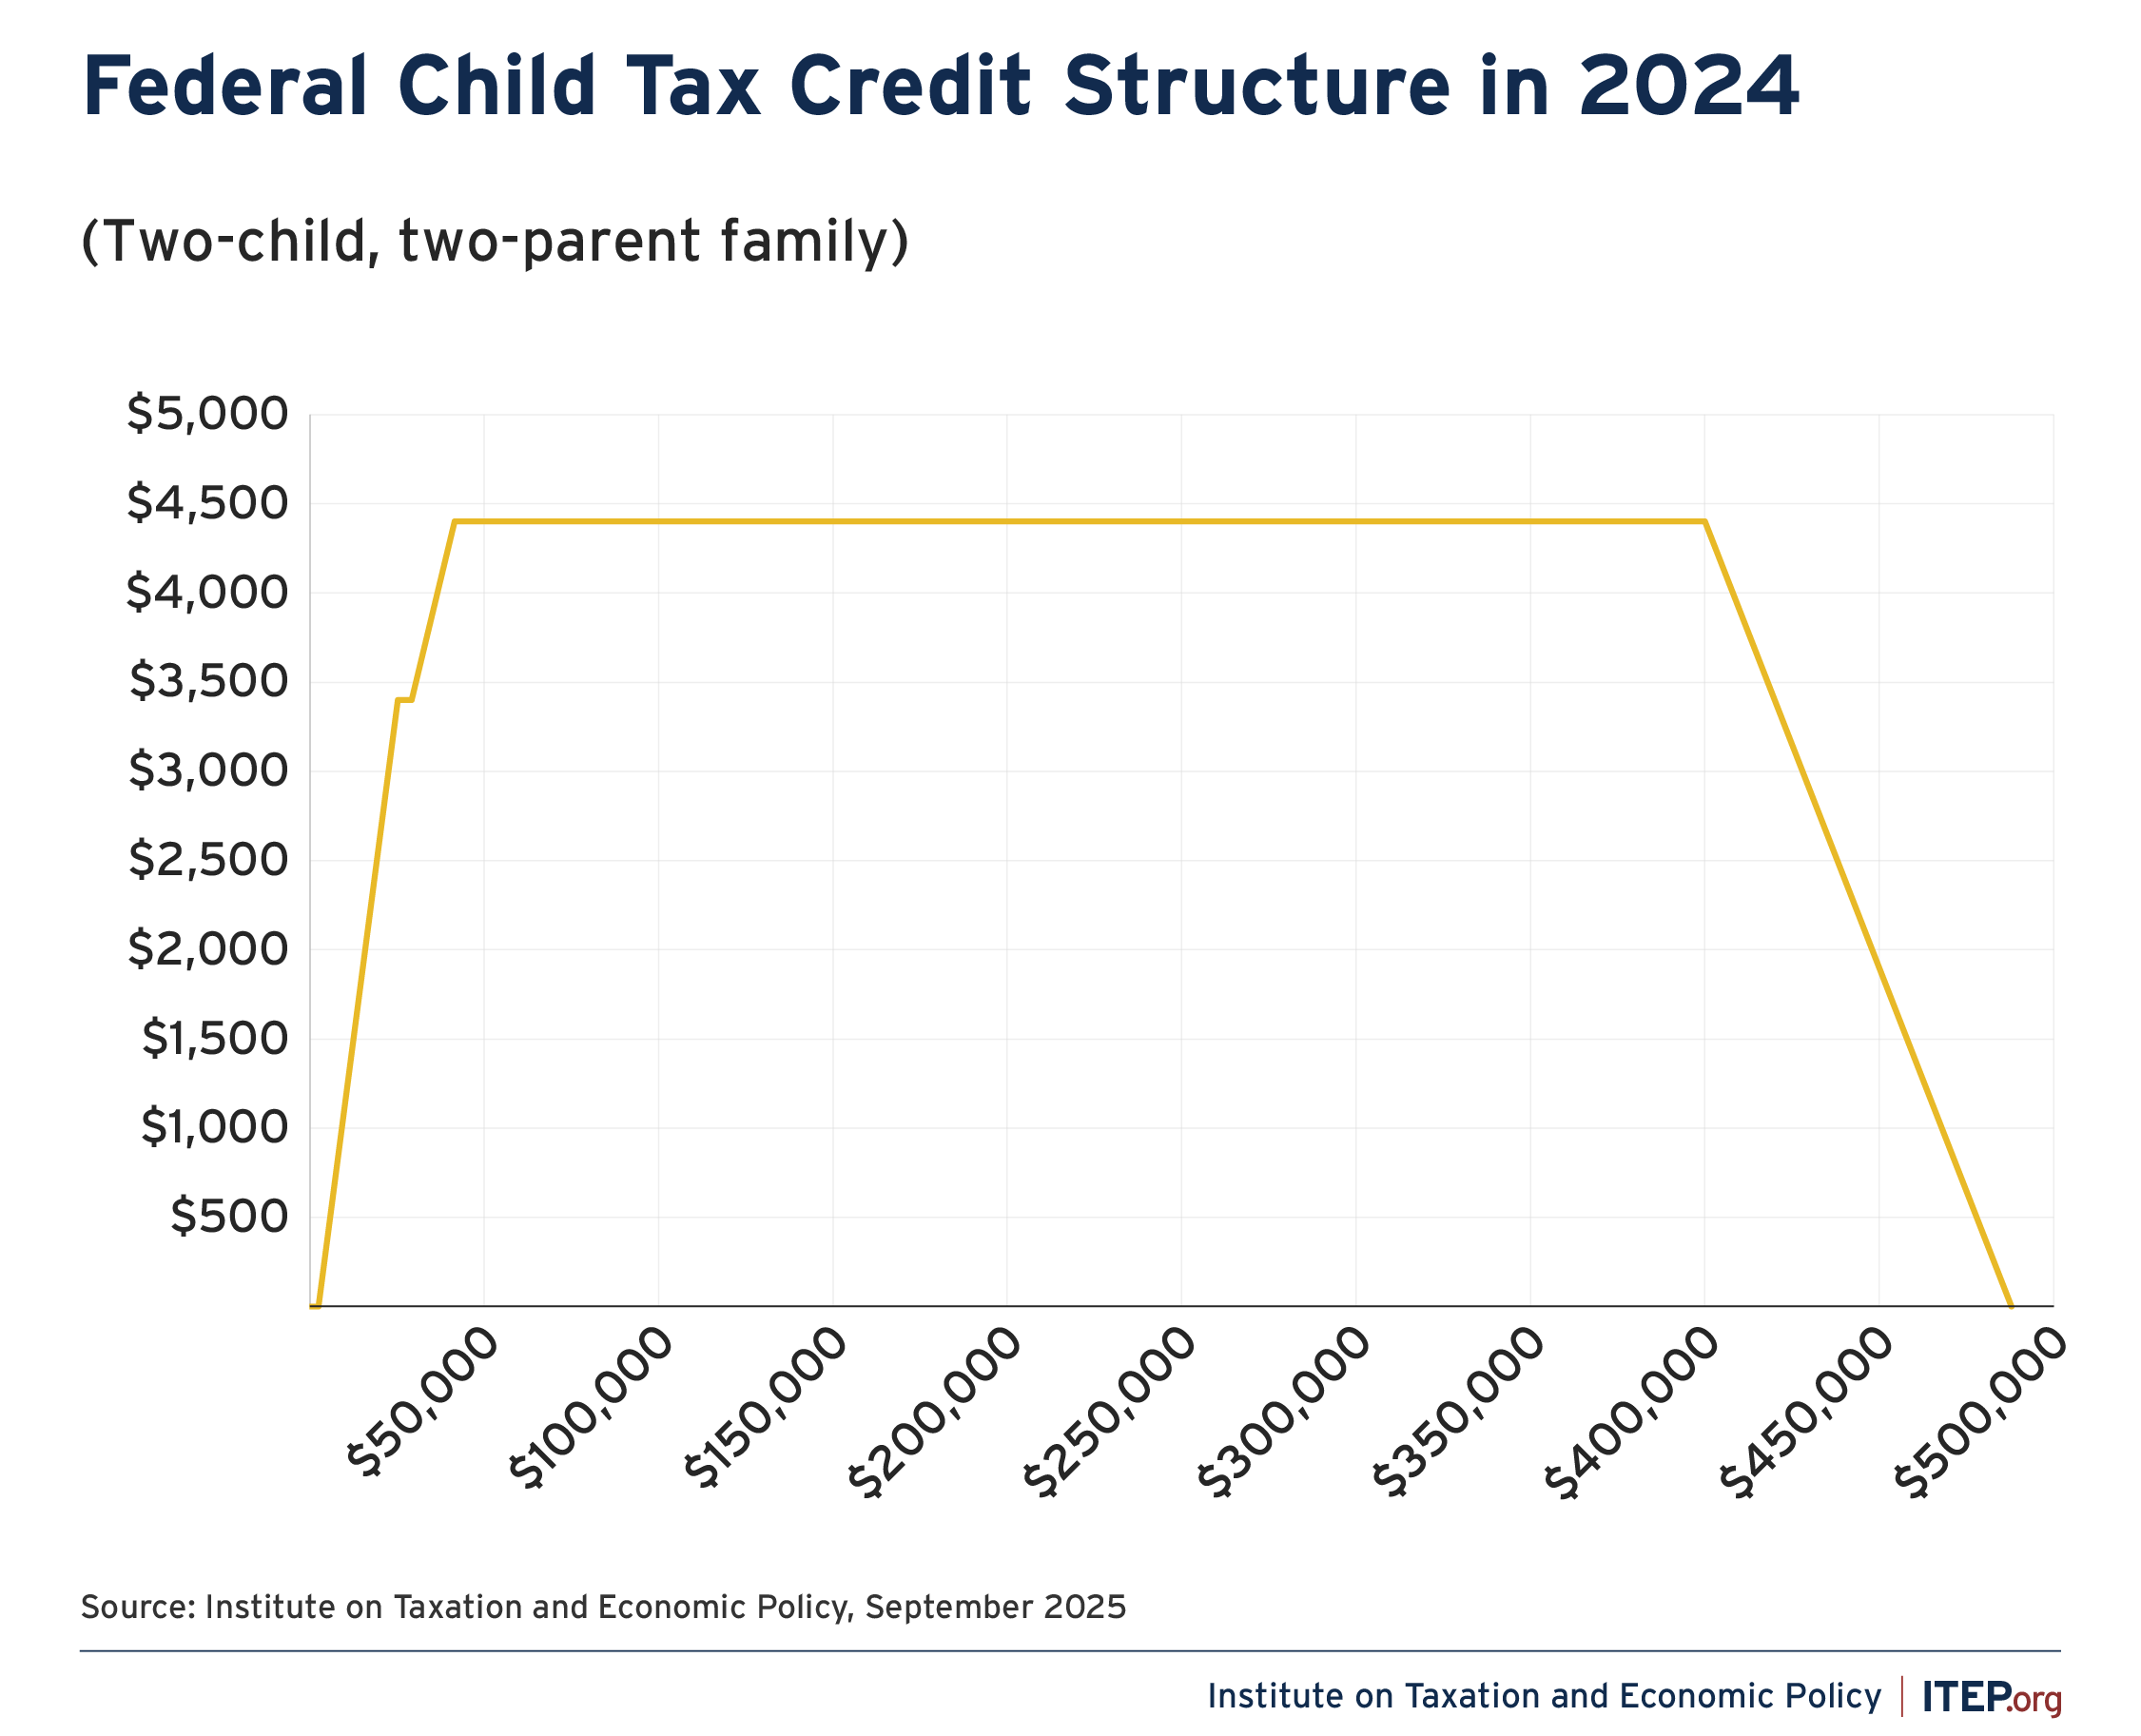
When evaluating these programs, policymakers typically establish adjusted gross income (AGI) phase-out thresholds. As a household's income rises above specified limits, the total value of the credit begins to diminish progressively. This targeted approach ensures that public funds are directed toward low- and middle-income families who bear a disproportionate financial load during their children's formative years.
Core Eligibility Criteria and Verification Requirements
Securing a child credit requires strict adherence to statutory eligibility rules. Tax authorities and benefit administrators enforce rigorous verification protocols to prevent fraudulent claims and ensure that funds reach qualifying households.
Relationship and Age Tests
To qualify, the child must bear a specific legal relationship to the filer. Eligible individuals typically include sons, daughters, stepchildren, eligible foster children, siblings, step-siblings, or descendants of any of these individuals. Additionally, the child must meet age limitations, which generally require the individual to be under a specified age threshold (such as under 17) by the close of the applicable tax year.
Residency and Support Requirements
The qualifying child must share a primary residence with the claimant for more than half of the calendar year, though specific exceptions exist for temporary absences due to illness, education, or military service. Furthermore, the child cannot have provided more than half of their own financial support during the tax year in question. Proof of residency and support may be requested during routine audits or automated return processing checks.
Identification Numbers
A valid taxpayer identification number is universally mandatory. In most jurisdictions, this requires a Social Security Number (SSN) issued before the due date of the tax return, including extensions. Children possessing only an Individual Taxpayer Identification Number (ITIN) may fall under separate, restricted benefit categories depending on the specific legislation governing the credit.
Key Differences Between Federal Child Tax Provisions
Tax codes frequently feature multiple provisions targeting families, which can lead to confusion. The table below outlines the primary distinctions between major federal child-related tax instruments to help taxpayers categorize their claims accurately.
| Benefit Type | Primary Purpose | Refundability Status | Key Income Phase-Out Trigger |
|---|---|---|---|
| Child Tax Credit (CTC) | Direct relief for raising dependent children under age 17. | Partially refundable (Additional Child Tax Credit). | Begins phasing out at higher modified adjusted gross income thresholds. |
| Child and Dependent Care Credit | Offset costs for daycare, babysitting, or care services enabling parents to work. | Non-refundable (historically subject to periodic legislative expansions). | Scales down based on AGI, reducing the maximum percentage allowed. |
| Earned Income Tax Credit (EITC) | Support low- to moderate-income working individuals and families. | Fully refundable. | Highly tiered based on earned income and number of qualifying children. |
Step-by-Step Guide to Claiming Your Credit
Filing for child-related financial benefits requires meticulous record-keeping and precise completion of tax documentation. Errors or omissions in reporting can lead to significant processing delays or automated audits by tax agencies.
- Gather Necessary Documentation: Collect all relevant tax forms, including W-2s, 1099s, and records of child care expenses if applicable. Ensure you have the full legal names, dates of birth, and verified Social Security Numbers for every dependent.
- Determine Qualifying Status: Review current tax guidelines to confirm that each child meets the age, relationship, residency, and financial support tests established for the tax year.
- Complete Relevant Tax Schedules: Fill out the primary tax return form alongside dedicated schedules (such as Schedule 8812 for the Child Tax Credit). Double-check calculations regarding earned income limitations and phase-out ranges.
- Verify Direct Deposit Information: If expecting a refund, input accurate bank routing and account numbers to expedite disbursement and avoid paper check mail delays.
- Retain Records for Auditing: Store copies of your filed return, supporting schedules, and expense receipts (such as daycare provider tax identification numbers) for at least three to seven years, depending on statutory look-back periods.
Common Mistakes and Troubleshooting Claim Delays
Even seasoned taxpayers occasionally stumble when navigating child credits, leading to rejected filings or delayed refunds. Recognizing these pitfalls helps safeguard your financial timeline.
One frequent error involves mismatched dependent information. If a child's name or Social Security Number on the tax return does not match government agency databases exactly, automated systems will immediately flag the return, freezing any associated refunds. Always verify data against the child's physical Social Security card prior to submission.
Another common issue arises from conflicting claims in shared custody arrangements. By law, only one parent can claim a qualifying child for the primary child credit in a given tax year. When parents divorce or separate without a clear, documented agreement—or attempt to claim the same child simultaneously—tax authorities initiate lengthy resolution processes to determine the custodial parent with primary residency rights.
Finally, failing to track earned income thresholds accurately can result in unexpected repayment obligations or reduced credit calculations. If a taxpayer's income fluctuates significantly throughout the year, utilizing estimated tax planning tools or consulting a qualified tax professional can prevent costly discrepancies.
Frequently Asked Questions
What happens if my income exceeds the phase-out threshold?
When your modified adjusted gross income surpasses the statutory threshold, the credit amount begins to reduce by a specific percentage for every dollar earned above that limit. If your income exceeds the upper bounds entirely, you may lose eligibility for that specific credit for the tax year, though other deductions or lower-tier benefits may still apply.
Can I claim a child credit if my child was born on December 31?
Yes. Tax rules generally dictate that if a child is born alive at any point during the tax year and meets all other dependency and residency tests, they qualify for the full credit for that entire tax year, provided they possess a valid Social Security Number issued in a timely manner.
Do state tax codes automatically mirror federal child credits?
No. State tax structures operate independently of federal laws. While some states offer a state-level child tax credit or working families credit that aligns with federal definitions, others have distinct income limits, residency rules, or do not offer a matching credit at all. Check your specific state department of revenue guidelines for local requirements.
What should I do if my child credit refund is delayed?
If your refund exceeds standard processing timelines, check the official tax agency tracking tool (such as the Internal Revenue Service "Where's My Refund?" portal). Delays are frequently caused by identity verification holds, mathematical errors, or missing documentation. Responding promptly to official correspondence from the tax agency is essential for resolution.
Are child credits considered taxable income?
Generally, federal tax credits and resulting refunds are not considered taxable income for federal income tax purposes. However, state-level tax treatment can vary, and certain specific benefit programs may have unique reporting rules. Consult state tax instructions or a certified public accountant for localized tax planning.
Strategic Financial Planning and Next Actions
Maximizing the financial impact of child credits extends beyond the annual tax filing season. Proactive household budgeting involves anticipating legislative changes, monitoring income shifts that could trigger phase-outs, and maintaining organized records of all child-related expenses throughout the year.
To ensure continuous compliance and optimal financial health, review your withholding amounts with your employer or adjust your estimated quarterly tax payments if your family's financial situation changes significantly. For complex family dynamics, such as recent custody modifications or adoption finalizations, consulting a licensed tax professional or certified public accountant provides tailored guidance that protects your household's financial interests.