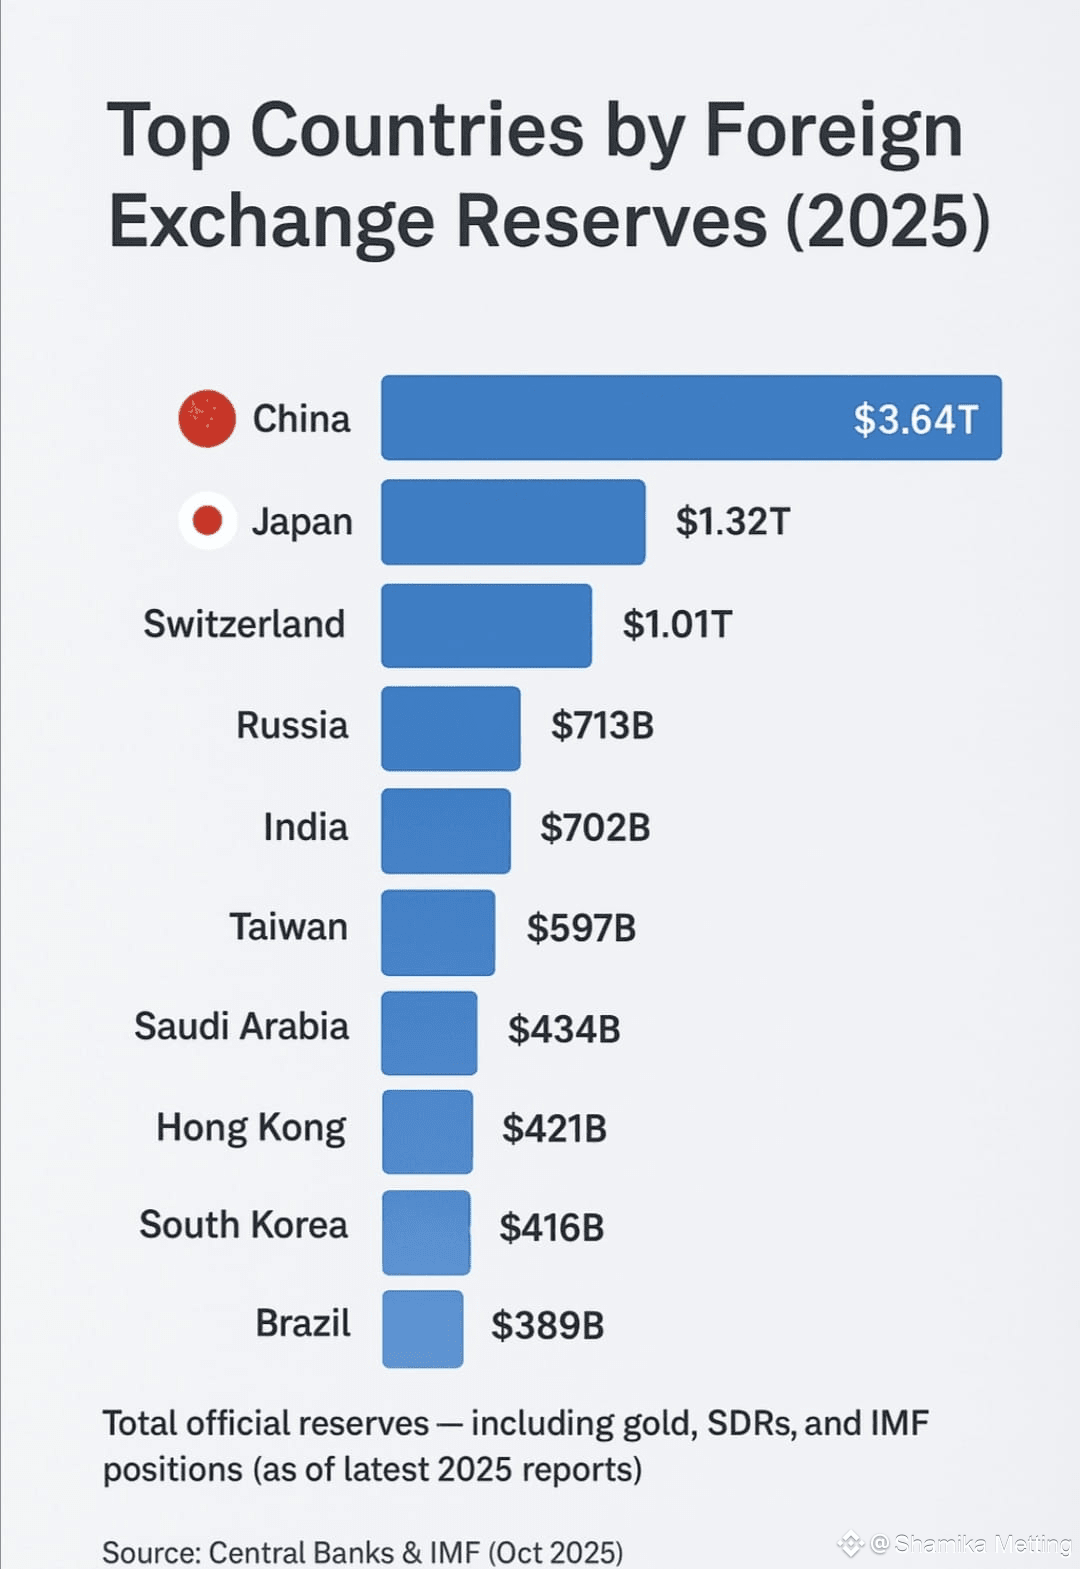
A forex reserve consists of external assets held in foreign currencies by a nation's central bank or monetary authority, primarily used to back domestic liabilities, stabilize exchange rates, and manage balance of payments crises. These financial stockpiles act as a crucial macroeconomic shock absorber for emerging and developed market economies alike.
What Is a Forex Reserve?
A foreign exchange reserve—commonly referred to as a forex reserve or reserve asset—represents official public sector holdings of foreign currency, gold, Special Drawing Rights (SDRs), and reserve positions within the International Monetary Fund (IMF). Central banks accumulate these assets through various channels, primarily by purchasing foreign exchange in domestic markets when capital inflows are strong, or through direct export revenues and sovereign borrowing.
The primary purpose of maintaining these reserves is to ensure that a central bank possesses adequate liquidity to intervene in foreign exchange markets, support the domestic currency during periods of sudden capital flight, and guarantee the settlement of international trade and debt obligations. Without adequate reserve cushions, national economies face heightened vulnerability to external shocks, sudden shifts in global investor sentiment, and volatile commodity pricing cycles.
The Macroeconomic Role of Central Bank Reserves
Central banks do not hoard foreign assets merely for prestige; these funds serve specific, operational mandates within monetary policy frameworks. When global financial markets experience stress, international investors frequently pull capital out of emerging economies and shift funds into safe-haven assets. This triggers sharp depreciations in domestic currencies, drives up the cost of imported goods, and induces domestic inflation.
By deploying a portion of its forex reserve into the open market—selling foreign currency and buying back domestic currency—a central bank can smooth out erratic exchange rate volatility. Furthermore, maintaining robust reserve levels reassures foreign creditors, credit rating agencies, and direct investors that the sovereign entity can service its foreign debt obligations without defaulting or imposing harsh capital controls.
Core Components of Foreign Exchange Reserves
Modern forex reserves are rarely held as piles of physical banknotes. Instead, they comprise a diversified portfolio of liquid international assets managed according to strict criteria emphasizing safety, liquidity, and yield, in that exact order of priority. According to statistical definitions established by the International Monetary Fund and monitored via systems like the IMF’s Data Dissemination Standards, reserves are categorized into distinct structural components.
1. Foreign Currencies
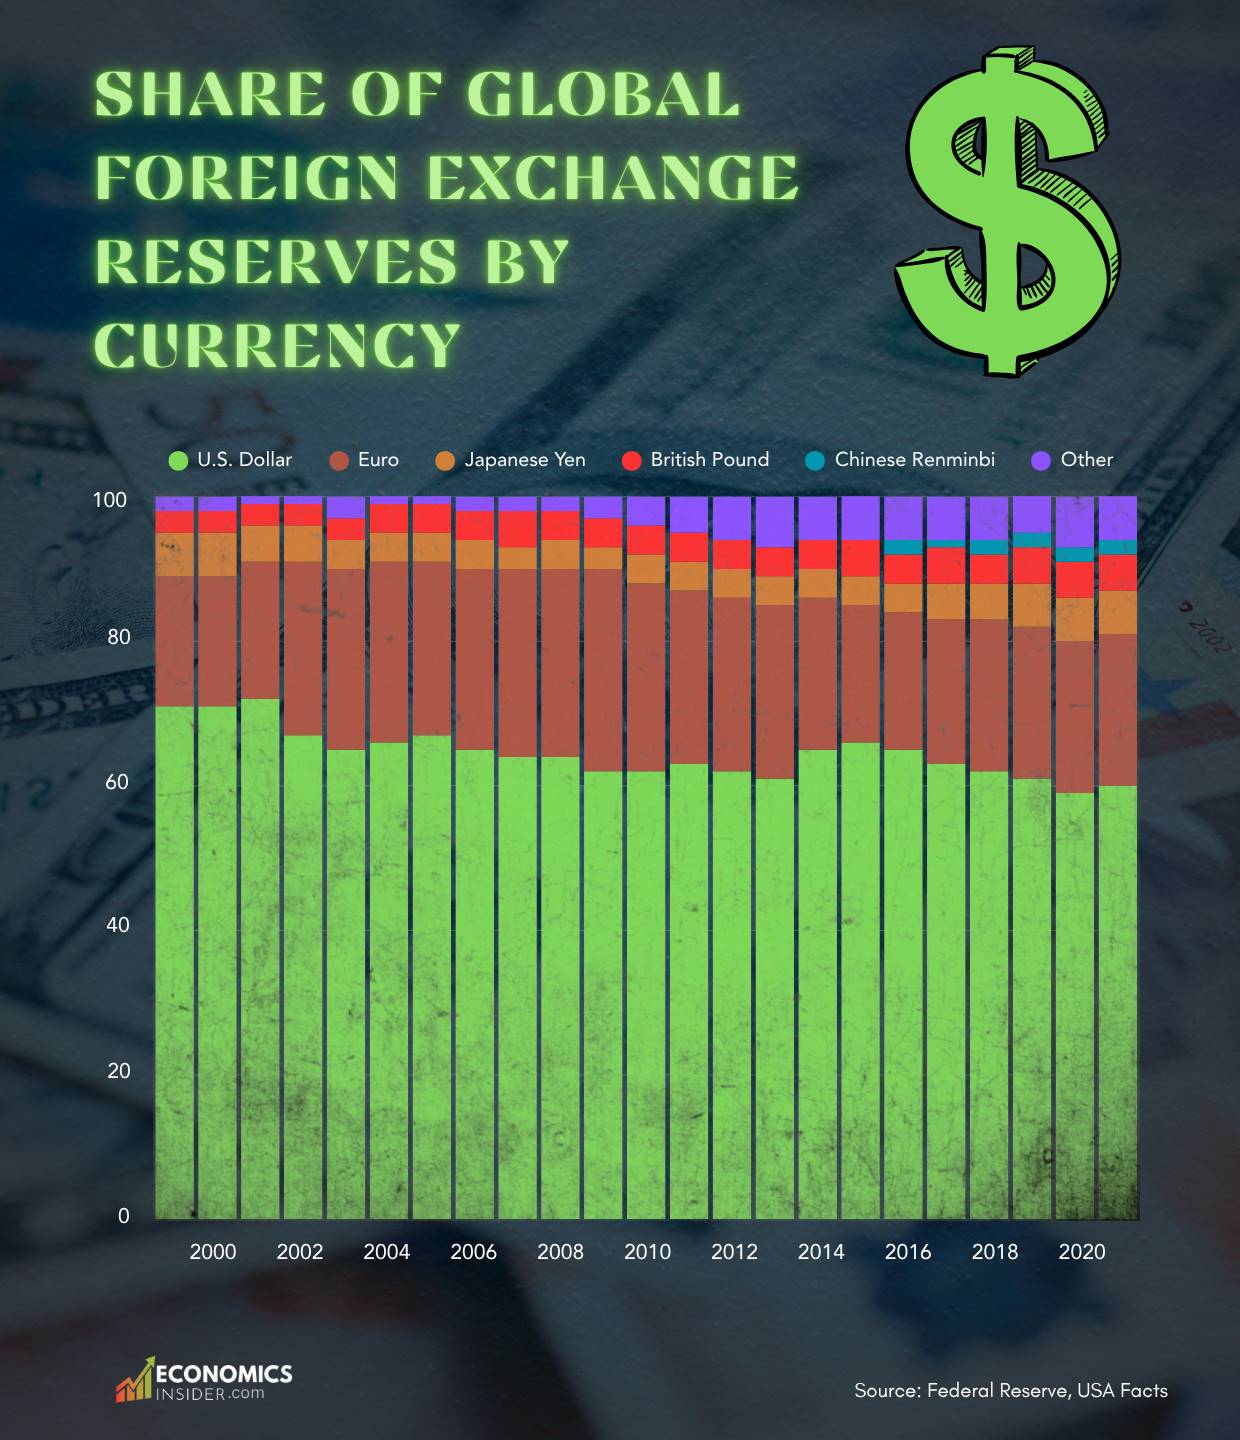
Foreign currency assets represent the largest share of most national forex reserves. These are held predominantly in globally accepted reserve currencies—most notably the United States Dollar (USD), Euro (EUR), British Pound (GBP), Japanese Yen (JPY), and Chinese Yuan (CNY). These currencies are held in the form of foreign bank deposits, short-term government treasury bills, sovereign bonds, and promissory notes issued by foreign governments.
2. Gold Reserves
Monetary gold remains a foundational component of sovereign reserves. Central banks hold physical gold bars stored in secure domestic vaults or international depositories, such as the Federal Reserve Bank of New York or the Bank of England. Gold serves as a traditional hedge against geopolitical instability, inflation, and systemic currency devaluation. While gold yields no direct interest, its intrinsic value provides ultimate backing of confidence in times of extreme crisis.
3. Special Drawing Rights (SDRs)
Created by the IMF in 1969, Special Drawing Rights are an international reserve asset created to supplement member countries' official reserves. An SDR is not a currency itself, but rather a potential claim on the freely usable currencies of IMF members. Its value is calculated daily based on a weighted basket of major global currencies. Central banks can exchange SDRs for usable currencies when facing balance of payments deficits.
4. Reserve Position in the IMF
Every member country of the IMF subscribes to a quota, a portion of which must be paid in reserve assets (historically gold or major currencies) and the remainder in the domestic currency. A country's reserve position at the IMF represents the reserve asset portion of its quota contribution, plus any lending the country has provided to the IMF under special credit arrangements. This position is readily accessible to the member country in times of external financial need.
Composition and Management of Sovereign Reserves
Managing a multi-billion-dollar or multi-trillion-dollar forex reserve requires sophisticated institutional governance. Central banks and specialized sovereign investment agencies utilize strict asset allocation frameworks to balance safety, liquidity, and return.
| Reserve Component | Primary Asset Types | Liquidity Level | Principal Function |
|---|---|---|---|
| Foreign Currencies | US Treasuries, German Bunds, UK Gilts, Foreign Bank Deposits | Extremely High | Market intervention, trade settlement, debt servicing |
| Monetary Gold | Physical Gold Bars (London Good Delivery standard) | Low to Moderate | Ultimate safe-haven asset, inflation hedge, confidence anchor |
| Special Drawing Rights | IMF-weighted currency basket claims | High | International liquidity supplementation, crisis backstop |
| IMF Reserve Position | Quota-based claims and credit lines with the IMF | High | Emergency balance of payments support |
The Priority Triangle: Safety, Liquidity, and Yield
The investment guidelines governing forex reserves differ fundamentally from commercial investment funds. While a private wealth fund prioritizes maximizing return on investment, a central bank must prioritize:
- Safety: Avoiding capital losses by investing primarily in high-grade sovereign debt issued by stable governments.
- Liquidity: Ensuring that assets can be converted into cash immediately without incurring market value losses during an acute crisis.
- Yield: Generating a modest return on investment only after safety and liquidity requirements are fully satisfied.
Why Central Banks Accumulate and Spend Reserves
The accumulation of foreign exchange reserves is a deliberate policy choice influenced by a nation's exchange rate regime and trade orientation. Nations that run persistent trade surpluses—particularly manufacturing and commodity-exporting economies—tend to accumulate massive reserve balances.
Export Competitiveness and Pegged Exchange Rates
Countries that peg their domestic currency to the US Dollar or another major anchor currency must actively intervene in foreign exchange markets to maintain that parity. If foreign capital floods into the country, driving up demand for the local currency, the central bank must print local currency and use it to buy foreign currency assets, thereby expanding its forex reserves. Conversely, if capital flows out, the central bank sells those reserves to defend the peg.
The Cost of Holding Reserves
Holding large pools of foreign reserves is not without economic costs. These opportunity costs arise because funds invested in low-yielding foreign sovereign bonds—such as US Treasury bills—could otherwise be deployed domestically toward infrastructure, education, or productive industrial investments that might generate higher domestic economic growth. Furthermore, when a central bank prints local currency to purchase foreign exchange, it can trigger domestic monetary expansion, requiring the central bank to sterilize the liquidity through domestic bond issuances, incurring interest expenses.
Frequently Asked Questions About Forex Reserves
What is the difference between forex reserves and a sovereign wealth fund?
Forex reserves are managed by central banks primarily for liquidity, monetary policy execution, and balance of payments stability, consisting of highly liquid short-term assets. Sovereign wealth funds, by contrast, are state-owned investment funds financed by surplus revenues (often from oil or commodity exports) that invest in higher-yielding, longer-term, and riskier assets like equities, real estate, and private equity to build generational wealth.
How do forex reserves impact a country's credit rating?
International credit rating agencies—such as Moody's, S&P, and Fitch—closely evaluate the adequacy of a nation's forex reserves when assessing sovereign credit risk. A robust reserve buffer capable of covering several months of imports and upcoming foreign debt obligations signals strong external solvency, lowering borrowing costs for both the government and domestic corporations.
What is the Guidotti Rule for reserve adequacy?
The Guidotti Rule is a benchmark for foreign reserve adequacy suggesting that emerging market economies should hold liquid foreign exchange reserves equal to 100% of their total external debt maturing within the coming twelve months. This rule was developed to ensure countries can withstand sudden stops in international capital flows without defaulting.
Can a country run out of forex reserves?
Yes. If a country experiences chronic trade deficits, massive capital flight, and sustained speculative attacks on its currency without access to external borrowing or IMF bailouts, its forex reserve can be entirely depleted. This scenario typically results in severe currency devaluation, sovereign default, hyperinflation, and the imposition of emergency import restrictions.
Conclusion and Practical Summary
Foreign exchange reserves function as the financial bedrock of a nation's economic sovereignty and external stability. Comprising foreign currencies, monetary gold, IMF reserve positions, and SDRs, these assets provide central banks with the necessary ammunition to defend currency values, service external debt, and navigate global financial turmoil. While maintaining vast reserves incurs opportunity costs, the systemic insurance they provide against sudden economic shocks remains indispensable in an interconnected global economy.