Tax records are the foundational documents that substantiate the income, deductions, and credits reported on a federal or state tax return. To remain compliant with the Internal Revenue Service (IRS) in 2026, individuals and businesses should generally retain these records for three to seven years, depending on the specific circumstances of the filing and the nature of the income reported.
The management of tax records involves more than just saving a copy of a signed Form 1040. It encompasses a systematic approach to gathering, organizing, and securing the evidence required to support every entry on a tax filing. Whether for personal financial planning, securing a mortgage, or preparing for a potential audit, understanding the nuances of tax recordkeeping is essential for financial health and legal protection.
Defining Tax Records and Their Primary Purpose
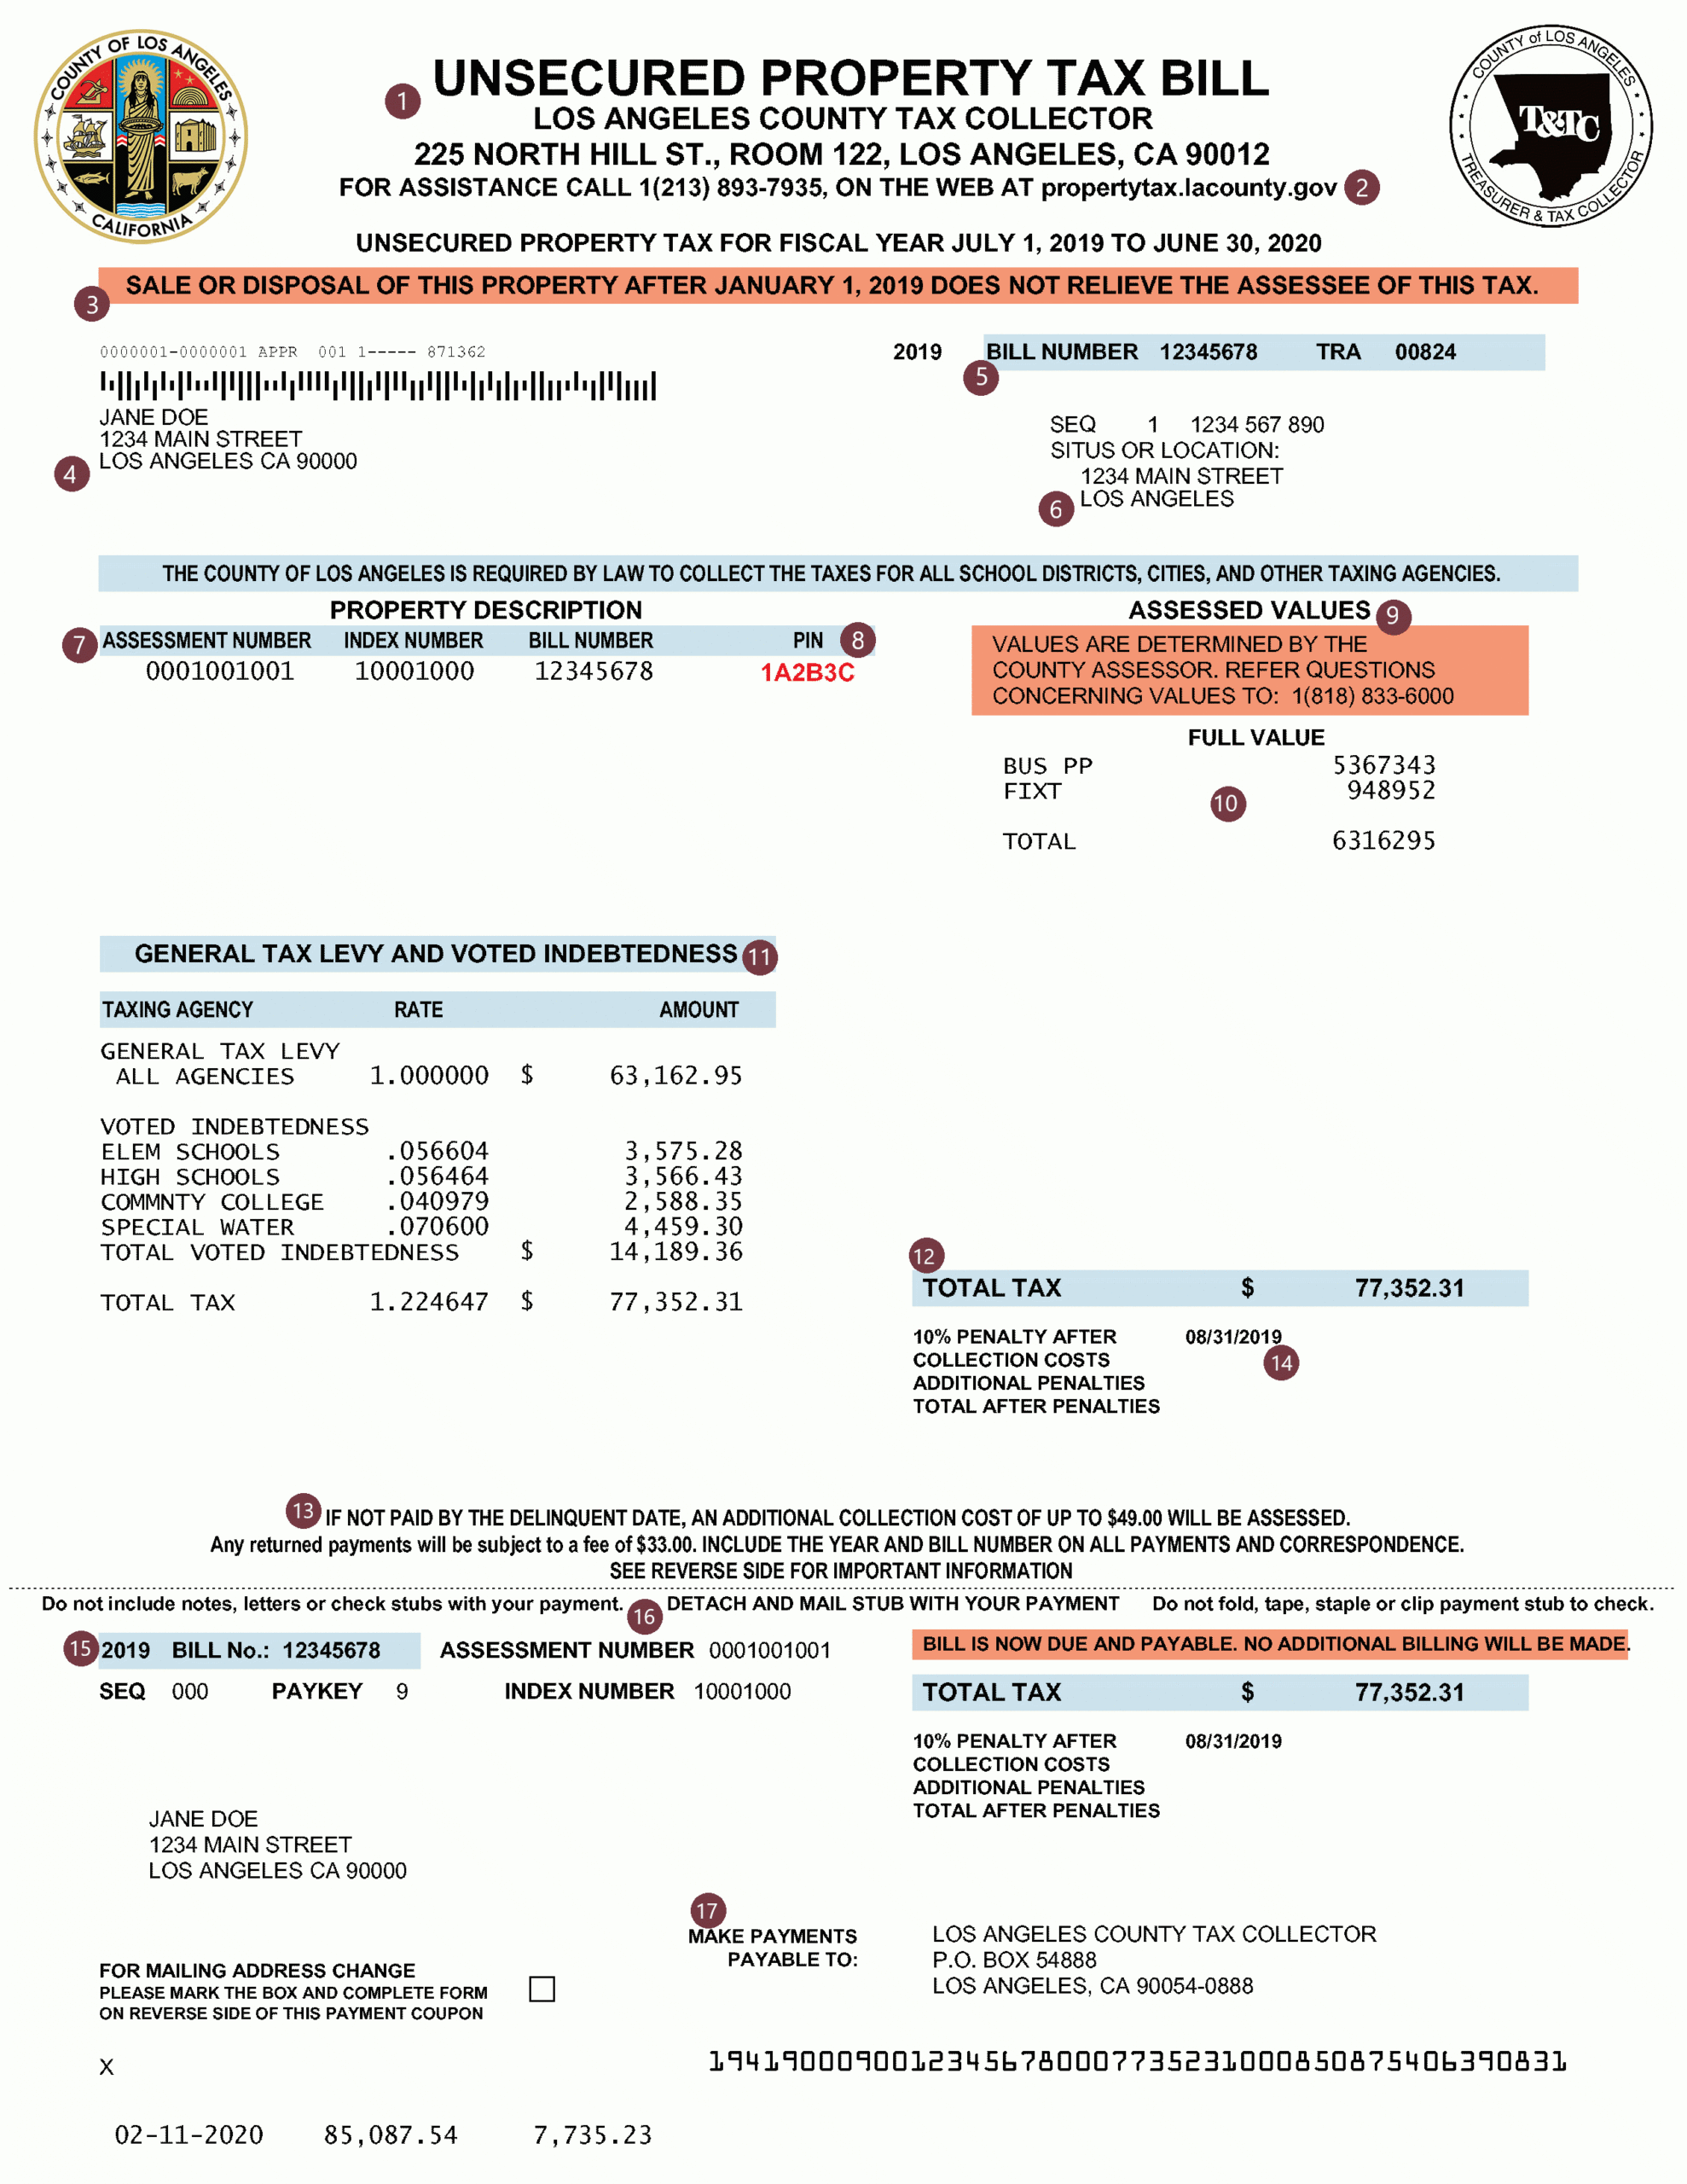
Tax records refer to any documentation that serves as evidence for the financial transactions reported to taxing authorities. These records provide a bridge between real-world economic activity and the figures appearing on tax forms. The primary purpose of maintaining these records is to prove the accuracy of a tax return if the IRS or state tax agency chooses to examine it.
Beyond audit protection, tax records are vital for several practical reasons:
- Loan and Mortgage Applications: Lenders almost universally require tax transcripts or returns to verify income and debt-to-income ratios.
- Calculating Future Gains: Records of property purchases and improvements (cost basis) are necessary to determine taxable gain or loss when an asset is sold.
- Insurance Claims: In the event of a disaster, tax records can help establish the value of lost or damaged property.
- Health Care Subsidies: Accurate records are required to reconcile advance payments of the Premium Tax Credit.
Categories of Essential Tax Records
Effective recordkeeping requires distinguishing between different types of documentation. In 2026, most taxpayers interact with both digital and physical records, but the evidentiary requirements remain consistent regardless of the format.
Income Documentation
Income records include all documents that show how much money was received during the year. For most employees, this starts with the Form W-2, which summarizes annual wages and taxes withheld. However, the modern economy frequently involves multiple streams of income, requiring a broader array of documents:
- 1099 Series Forms: These include 1099-NEC for non-employee compensation, 1099-MISC for miscellaneous income, 1099-INT for interest, and 1099-DIV for dividends.
- 1099-K Forms: With the continued prevalence of third-party payment networks and e-commerce platforms, Form 1099-K is a critical record for reflecting digital payment transactions.
- K-1 Schedules: These are used for income from partnerships, S-corporations, and trusts.
- Cryptocurrency and Digital Asset Records: In 2026, the IRS maintains strict reporting requirements for digital assets. Taxpayers must keep transaction logs, wallet addresses, and records of the fair market value of assets at the time of each trade or exchange.
Expense and Deduction Records
To lower tax liability, taxpayers often claim deductions. These must be backed by specific evidence, especially if the taxpayer chooses to itemize deductions on Schedule A rather than taking the standard deduction.
- Charitable Contributions: For cash contributions, a bank record or a written communication from the charity is required. For any single contribution of $250 or more, a contemporaneous written acknowledgment from the organization is mandatory.
- Medical Expenses: Invoices and payment receipts for healthcare services, prescriptions, and medical insurance premiums.
- Home Mortgage Interest: Form 1098, provided by the lender, serves as the primary record for interest paid and property taxes handled through escrow.
- Business Expenses: For those with self-employment income, receipts for travel, equipment, advertising, and office supplies are necessary. The IRS generally requires "adequate records" or "sufficient evidence" to support these claims.
Retention Timelines: How Long Should You Keep Tax Records?
The length of time you must keep a tax record is tied to the statute of limitations, which is the period during which the IRS can audit your return or you can amend a return to claim a credit or refund. As of 2026, the following guidelines represent the standard retention periods recommended by tax professionals.
| Situation or Document Type | Recommended Retention Period |
|---|---|
| Standard Income Tax Returns | 3 years from the date the return was filed or 2 years from the date the tax was paid, whichever is later. |
| Underreported Income (>25%) | 6 years if you omitted more than 25% of your gross income from the return. |
| Employment Tax Records | 4 years after the date the tax becomes due or is paid, whichever is later. |
| Property Records (Real Estate/Stocks) | Period of limitations for the year in which you dispose of the property in a taxable disposition, plus 3 years. |
| Bad Debt or Worthless Securities | 7 years. |
| Fraudulent Returns / Not Filing | Indefinite. There is no statute of limitations for fraud or failure to file. |
The "Three-Year Rule" and Its Exceptions
The basic statute of limitations for the IRS to assess additional tax is three years. Consequently, many taxpayers believe they can discard everything after the three-year mark. However, this is a risky strategy. If the IRS suspects a "substantial understatement" of income—defined as omitting more than 25% of gross income—the window for an audit doubles to six years.
Furthermore, state tax agencies often have different statutes of limitations than the IRS. For example, some states allow for an audit up to four or five years after filing. To be safe, many tax experts recommend a seven-year "catch-all" rule for standard tax records to ensure compliance with both federal and state regulations.
Retrieving Missing Tax Records and Transcripts
If a taxpayer loses their original records or needs a formal verification of their filing for a third party, the IRS provides several methods for retrieving information. It is important to distinguish between a "tax return" (the original form you filed) and a "tax transcript" (a summary of the return).
IRS Tax Transcripts
A transcript is often sufficient for most purposes, including mortgage applications and student aid verification. Transcripts are generally available free of charge. In 2026, the most efficient way to access these is through the IRS Online Account portal.
There are five main types of transcripts available:
- Tax Return Transcript: Shows most line items from the original return (Form 1040) as filed. It does not reflect changes made after the original filing.
- Tax Account Transcript: Provides basic data such as return type, marital status, adjusted gross income, and taxable income. Crucially, it also shows any adjustments made by the IRS after the return was filed.
- Record of Account Transcript: A combination of the Return and Account transcripts, providing the most complete picture of the tax filing.
- Wage and Income Transcript: Shows data from information returns the IRS receives, such as W-2s, 1099s, and 1098s. This is exceptionally useful if you lost your physical W-2.
- Verification of Non-filing Letter: Proof that the IRS has no record of a filed Form 1040 for a particular year.
Requesting Copies of Actual Returns
If a transcript is insufficient and an exact copy of the original return (including all attachments) is required, taxpayers must file Form 4506, Request for Copy of Tax Return. Unlike transcripts, there is a fee (currently $30 per return as of early 2026) for this service, and it can take up to 75 calendar days to process.
Organizing and Securing Records in a Digital Environment
By 2026, digital recordkeeping has become the standard for both efficiency and security. Physical receipts fade over time, and paper files are susceptible to damage from fire or water.
Digital Storage Best Practices
The IRS accepts digital receipts and records as long as they are "legible and exhibit a high degree of legibility and readability." To maintain a robust digital archive:
- Use High-Quality Scans: Use a dedicated scanner or a mobile scanning app that produces PDF files. Ensure all dates, vendor names, and amounts are clearly visible.
- Consistent Naming Conventions: Label files consistently (e.g., "2026_1099NEC_ClientName.pdf"). This makes searching for specific documents much easier during an audit.
- The 3-2-1 Backup Rule: Maintain three copies of your records, stored on two different types of media (e.g., an external hard drive and a local computer), with one copy stored off-site or in the cloud.
- Encryption and Security: Tax records contain Social Security numbers and sensitive financial data. Cloud storage should utilize end-to-end encryption and multi-factor authentication (MFA). Avoid storing unencrypted tax records on public or shared computers.
Handling Physical Records
For any documents that must remain in physical form (such as certain legal certificates or original wet-signature contracts), use a fireproof and waterproof safe. If you use a filing cabinet, organize it by tax year rather than by document type to simplify the purging process when the retention period expires.
Special Considerations for Property and Business Records
Certain assets and activities require much longer retention periods than the standard three-to-seven-year window.
Property and Investment Records
Records relating to property should be kept for as long as you own the asset plus the period of limitations for the year you sell it. This is because you must be able to prove your "basis"—the amount you invested in the asset.
- Real Estate: Keep the closing disclosure from your purchase, as well as receipts for "capital improvements" (e.g., a new roof, a kitchen remodel, or a swimming pool). Routine repairs do not add to basis, but improvements do and can significantly reduce your capital gains tax when you sell the home.
- Stocks and Bonds: Maintain records of purchase dates and prices. While modern brokerage statements track this automatically, you are ultimately responsible for the accuracy of the cost basis reported on your return.
Small Business and Self-Employment
Business owners are held to a higher standard of recordkeeping. In addition to income and expense records, businesses must maintain:
- Employment Tax Records: The IRS requires businesses to keep all records of employment taxes for at least four years after the tax becomes due or is paid. This includes payroll records, amounts of wages subject to withholding, and employee information.
- Asset Depreciation: If you depreciate equipment or vehicles over several years, keep the records showing the purchase price and the depreciation method used until you dispose of the asset and the statute of limitations for that year expires.
Disposal of Tax Records
Once the retention period has passed, tax records should not simply be thrown in the trash. Because these documents contain highly sensitive Personally Identifiable Information (PII), including names, addresses, and Social Security numbers, they are primary targets for identity thieves.
Professional shredding—either through a high-quality cross-cut home shredder or a professional document destruction service—is the only recommended method for disposing of physical tax records. For digital records, ensure that files are permanently deleted and that old hardware is wiped using data-sanitization software before being recycled or sold.
Frequently Asked Questions
What should I do if my tax records were destroyed in a natural disaster?
You should immediately attempt to reconstruct your records. The IRS provides guidance in Publication 584 (Individual) and Publication 584-B (Business) for calculating losses. You can request free transcripts of your returns and contact your employers, banks, and service providers for copies of statements and receipts.
Do I need to keep records of my non-deductible IRA contributions?
Yes. You should keep records of non-deductible contributions to a traditional IRA (reported on Form 8606) until you have withdrawn all funds from the IRA. This ensures you do not pay taxes twice on the same money when you eventually take distributions.
Can the IRS ask for records older than six years?
While rare, the IRS can request records from any year if they suspect tax fraud or if no return was ever filed. In these specific cases, there is no statute of limitations. For most compliant taxpayers, however, the six-year mark is the practical limit for federal inquiries.
Are digital photos of receipts sufficient for an audit?
Yes, provided the photos are clear, legible, and include all necessary information (date, vendor, amount, and business purpose). Most modern accounting software allows you to attach these images directly to specific transactions, which is highly recommended for audit readiness.
How do I get records from a state tax agency?
State agencies operate independently of the IRS. You must visit the website of your specific state's Department of Revenue or Taxation to request state tax transcripts. The process and fees vary significantly by state.
Practical Recommendations
To maintain a compliant and stress-free tax record system in 2026, implement a "scan-as-you-go" policy. Instead of waiting until tax season to organize a year's worth of paperwork, use a mobile app to digitize receipts the moment you receive them. Ensure your IRS Online Account is active and that you have verified your identity through the current authorized service (such as ID.me) to allow for immediate access to transcripts when needed. Finally, set a recurring annual date—such as after you file your current year's return—to review your archives and securely destroy documents that have exceeded the seven-year retention threshold.