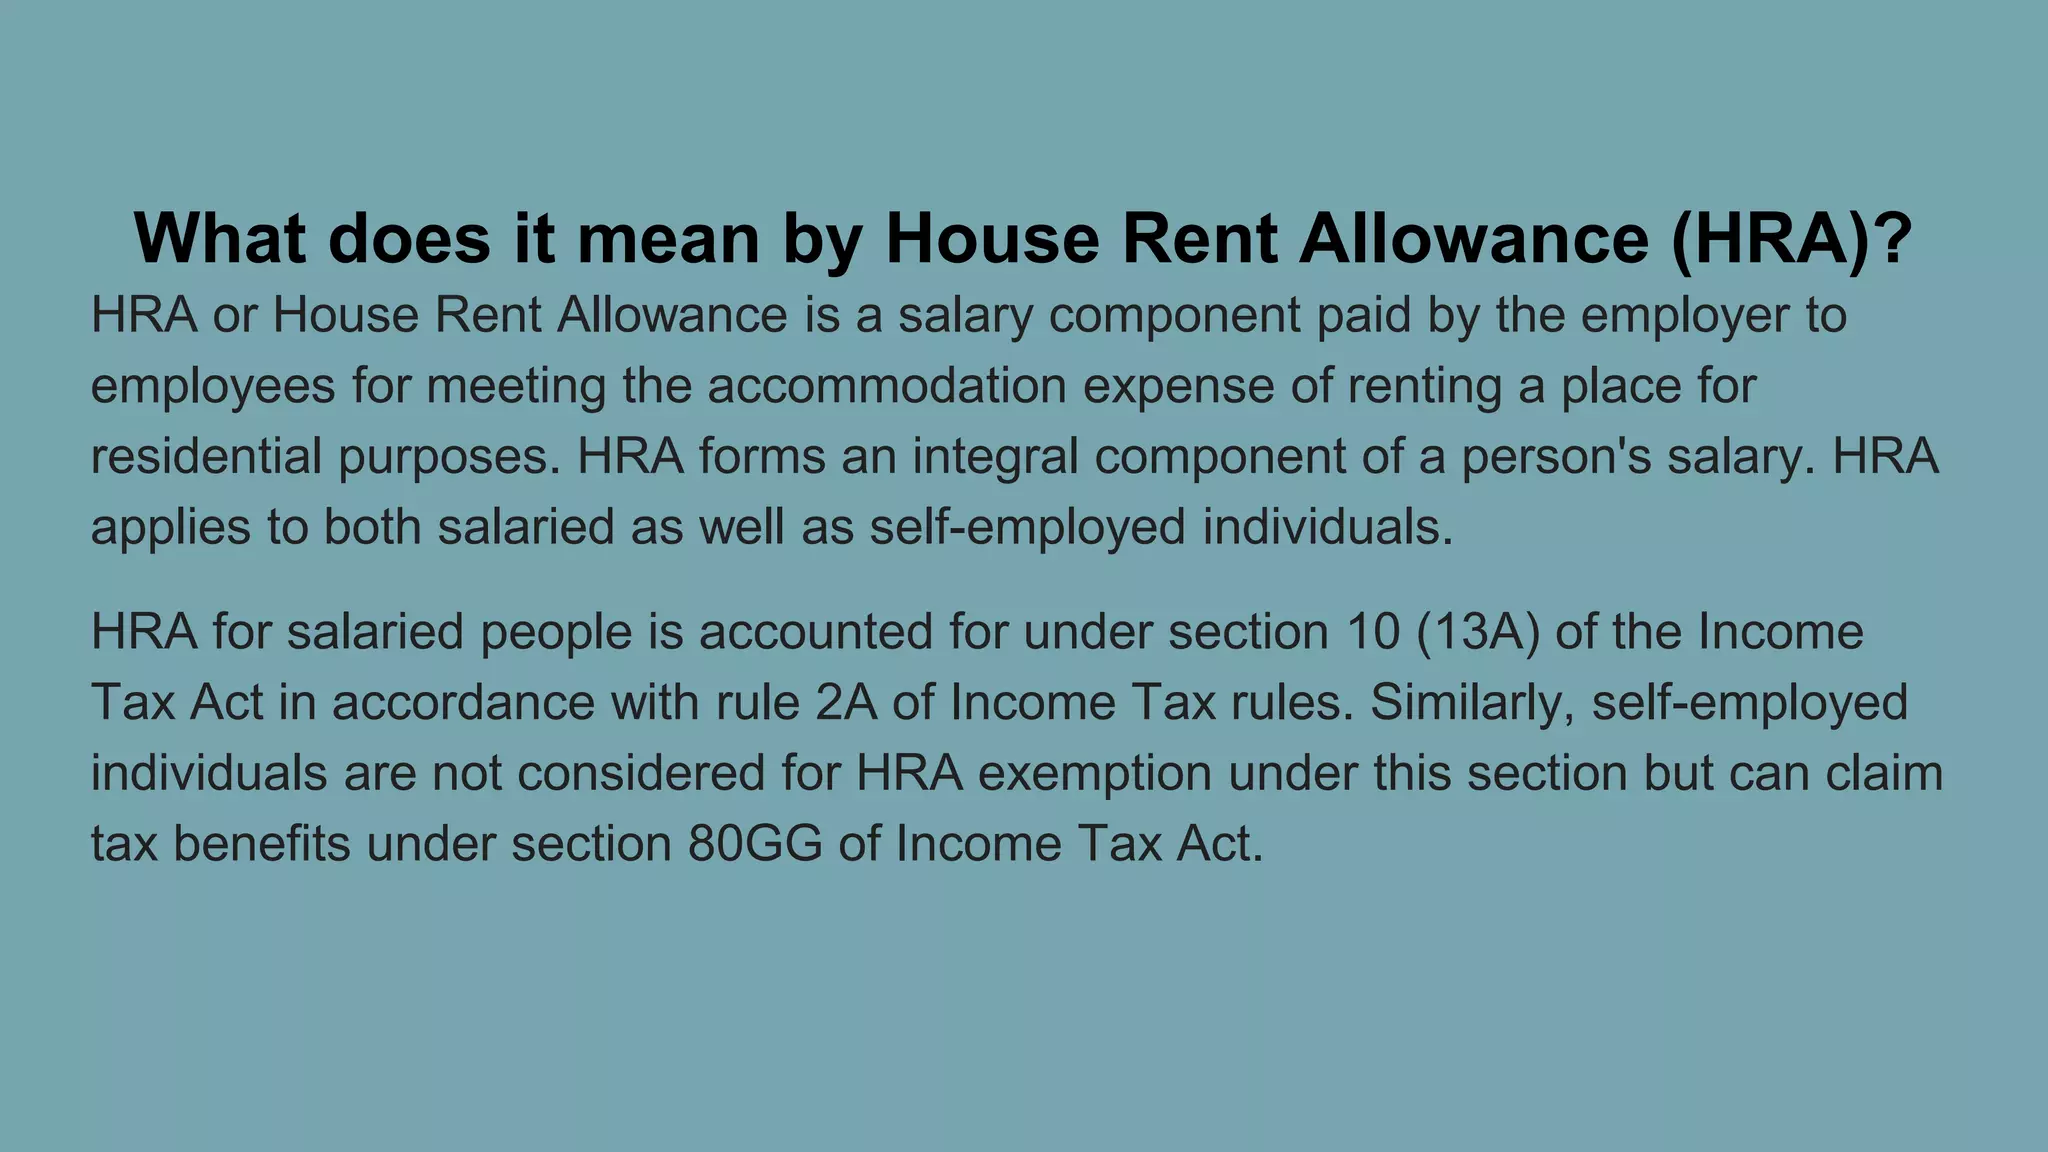
A House Rent Allowance (HRA) benefit is a specific financial component provided by employers to employees to help cover rental accommodation costs. To qualify for tax exemptions under this benefit, employees must live in rented housing, actually pay rent, and not own the residential property where they reside.
Introduction to House Rent Allowance (HRA)
Navigating the landscape of employee compensation requires a firm grasp of various allowances and deductions designed to optimize take-home pay while complying with national tax codes. Among these, the House Rent Allowance (HRA) stands out as one of the most common and valuable components of a salary structure. For millions of salaried workers, understanding how the HRA benefit functions is essential for reducing tax liabilities legally and effectively.
At its core, HRA is an allowance specifically earmarked for housing expenses. Employers pay this amount to employees as part of their regular compensation package. However, the distinct advantage of HRA lies in its potential for tax exemption. Under specific tax laws, a portion—or sometimes the entirety—of the HRA received can be excluded from taxable income, provided certain statutory conditions are met. This comprehensive guide explores the mechanics of HRA, eligibility criteria, the exact calculation methods mandated by tax authorities, documentation requirements, common pitfalls, and strategies for maximizing this benefit.
Fundamental Concepts and Eligibility Criteria
Before an employee can claim any tax exemption on their House Rent Allowance, they must satisfy a foundational set of eligibility rules. Misunderstanding these prerequisites is one of the leading causes of disallowed tax claims and subsequent notices from tax administrators.
Who Can Claim HRA?
To qualify for an HRA tax exemption, an individual must meet three primary criteria:
- Salaried Employment: The individual must be a salaried employee whose compensation structure explicitly includes HRA. Self-employed individuals or freelancers cannot claim HRA because they do not receive a salary from an employer; instead, they may explore other sections of tax code related to business expenses or self-employed deductions (such as Section 80GG in Indian tax law, which provides deductions for rent paid by those not receiving HRA).
- Actual Rent Payment: The employee must actually incur and pay rent for a residential accommodation that they occupy.
- Absence of Ownership: The employee must not own the residential property for which they are claiming the HRA exemption. If an individual lives in a house they own, any HRA received from an employer becomes fully taxable.
The Role of Accommodation Type
The nature of the accommodation significantly impacts how HRA is treated:
- Rented Property from a Landlord: The standard scenario where an employee signs a lease agreement with a third-party landlord and pays monthly rent.
- Living with Parents: Employees can pay rent to their parents, provided the parents own the property and declare the rental income in their own tax returns. This strategy requires formal documentation, including a valid rent agreement and bank transfer receipts, to withstand regulatory scrutiny.
- Living in One's Own Property: If an employee owns a home (even if they have an active home loan on it) and lives in it while receiving HRA, the entire HRA amount is added to their gross taxable income. However, they may still claim deductions on home loan interest and principal repayment under separate provisions.
How HRA Tax Exemption is Calculated
The calculation of the tax-exempt portion of an HRA benefit is not arbitrary. It is governed by strict statutory formulas. When an employee submits their rent receipts and lease agreements, payroll departments or tax authorities determine the exempt amount as the least of the following three parameters:
- Actual HRA Received: The total amount of House Rent Allowance paid by the employer during the financial year.
- Rent Paid Minus 10% of Basic Salary: The actual rent paid for the accommodation during the period, minus 10% of the employee's basic salary plus dearness allowance (DA), if applicable.
- City-Based Percentage of Basic Salary:
- 50% of Basic Salary + DA if the rented accommodation is located in a designated metro city (such as Mumbai, New Delhi, Kolkata, or Chennai).
- 40% of Basic Salary + DA if the rented accommodation is located in any other non-metro city.
Mathematical Example of HRA Calculation
To visualize how these rules apply in practice, consider a hypothetical scenario for a financial year:
- Basic Salary + DA: $500,000
- Actual HRA Received from Employer: $200,000
- Actual Rent Paid by Employee: $240,000 ($20,000 per month)
- Location: Non-Metro City (40% rule applies)
Let us evaluate the three statutory limits:
- Actual HRA Received: $200,000
- Rent Paid Minus 10% of Basic Salary:
- Actual Rent ($240,000) - [10% of $500,000 ($50,000)] = $190,000
- 40% of Basic Salary (Non-Metro):
- 40% of $500,000 = $200,000
Comparing the three results ($200,000; $190,000; and $200,000), the least amount is $190,000.
Therefore:
- Tax-Exempt HRA: $190,000
- Taxable HRA: $200,000 (Actual received) - $190,000 (Exempt) = $10,000
In this scenario, out of the $200,000 received as an HRA benefit, $190,000 is shielded from income tax, while the remaining $10,000 is added to the employee's taxable income and taxed according to their respective income tax bracket.
| Calculation Parameter | Rule / Condition | Example Value |
|---|---|---|
| Actual HRA | Total allowance received from employer | $200,000 |
| Rent Minus 10% Basic | Actual Rent Paid – (10% × Basic Salary + DA) | $190,000 |
| City Limit (Metro) | 50% of Basic Salary + DA (Delhi, Mumbai, Kolkata, Chennai) | N/A (Non-metro in example) |
| City Limit (Non-Metro) | 40% of Basic Salary + DA (All other cities) | $200,000 |
| Final Exempt Amount | Lowest of the three calculated parameters above | $190,000 |
Essential Documentation and Compliance
Claiming the HRA benefit requires maintaining an airtight paper trail. Tax authorities and corporate human resources departments require specific documents to verify the legitimacy of the rental arrangement before granting tax exemptions.
1. Rent Agreement
A legally valid, written rent agreement between the landlord and the tenant is mandatory. This document should explicitly state:
- The names and permanent addresses of both the landlord and the tenant.
- The complete address of the rented property.
- The monthly rent amount and the due date.
- The duration of the lease agreement (typically 11 months, renewable).
- Signatures of both parties and witnesses, along with stamp duty where legally required.
2. Rent Receipts
Employees must submit physical or digital rent receipts corresponding to the months for which the exemption is claimed. Each receipt should contain:
- The tenant’s name.
- The landlord’s name.
- The property address.
- The period for which rent is paid (e.g., monthly).
- The signature of the landlord.
- Revenue stamps (where mandated by local stamp acts for cash payments exceeding specified thresholds).
3. Landlord’s Permanent Account Number (PAN)
In many jurisdictions, if the annual rent paid exceeds a specific statutory threshold (for instance, $100,000 or local currency equivalent), providing the landlord's PAN to the employer is mandatory. Failure to provide the landlord's PAN can result in the employer withholding the HRA tax exemption entirely. If the landlord does not possess a PAN, a formal declaration signed by the landlord stating they do not have one is often required.
4. Proof of Payment
While rent receipts serve as primary proof, bank transfer records (such as canceled checks, online bank statements, or digital wallet receipts) provide robust secondary evidence that funds actually changed hands, minimizing audit risks.
Common Pitfalls and Troubleshooting
Navigating HRA claims involves several common mistakes that can lead to rejected exemptions, delayed refunds, or unexpected tax liabilities.
Paying Rent in Cash Without Receipts
Relying solely on informal cash payments without contemporaneous, signed rent receipts leaves employees defenseless during a tax audit. Always obtain signed receipts monthly or quarterly. When cash transactions are high, digital banking channels are vastly superior because they create an unalterable audit trail.
Incorrect Salary Component Definitions
Employees often make the mistake of calculating HRA exemptions using their Gross Salary rather than Basic Salary plus Dearness Allowance. Bonuses, overtime pay, commissions, and standard perquisites are excluded from the baseline salary figure used in the statutory formula. Using an inflated salary base will result in incorrect calculations and potential under-reporting of taxes.
Claiming HRA and Home Loan Tax Benefits Simultaneously
A common point of confusion arises when individuals purchase a home using a mortgage while continuing to live in a rented property in a different city (or even the same city due to professional posting).
- Can you claim both? Yes. If you own a house in one city and live in a rented house in another city due to employment, or if your owned house is under construction and you reside elsewhere, you can legally claim both the HRA tax exemption on your rent and the tax deductions on your home loan (interest under Section 24 and principal under Section 80C, where applicable).
- Living in your own house while claiming HRA: If you own a house and live in it while also paying rent to a relative for a different property simply to claim HRA, tax authorities may scrutinize the arrangement as a tax avoidance scheme, potentially disallowing the claim.
Frequently Asked Questions
Can I claim HRA if I live with my parents?
Yes, you can claim HRA if you live in a property owned by your parents, provided you pay them genuine monthly rent and possess a formal rent agreement. Your parents must report this rental income in their personal tax returns as income from house property. You cannot claim HRA if you simply live in your parents' house without a formal tenancy arrangement or cash/bank rent transfer.
What happens if I forget to submit rent proofs to my employer?
If you miss the deadline for submitting rent proofs to your employer’s payroll department, the employer will deduct tax at source (TDS) assuming no HRA exemption applies. However, you can typically claim the HRA exemption directly when filing your annual personal income tax return by recalculating your tax liability and claiming a refund for the excess TDS withheld.
Is PAN of the landlord mandatory for all HRA claims?
Not always. The requirement for a landlord's PAN typically applies only when the total annual rent paid exceeds a specified statutory threshold. If your annual rent is below this threshold, PAN submission is generally not mandatory, though maintaining signed rent receipts remains essential.
Can both spouses claim HRA if they live in the same rented accommodation?
Yes, both spouses can claim HRA individually if they are both salaried employees and both contribute to the rent, provided the rent agreement reflects both as joint tenants or distinct rent payments are made. However, they cannot claim exemption on the same portion of rent; the total claimed exemptions cannot exceed the actual rent paid.
What salary components are excluded when calculating HRA?
When applying the statutory HRA formula, allowances such as transport allowances, medical allowances, special allowances, performance bonuses, and employer contributions to retirement funds are excluded. Only the basic salary and the dearness allowance (if part of the terms of employment) form the baseline calculation.
Conclusion and Next Actions
Maximizing the House Rent Allowance (HRA) benefit requires careful attention to detail, adherence to statutory calculation formulas, and diligent record-keeping. To ensure your HRA claims are audit-proof and fully optimized, review your current compensation structure with your human resources or payroll department, secure a formal, stamped rent agreement with your landlord, and establish a digital paper trail for all monthly rent transfers. By proactively managing these requirements, you can legally minimize your tax burden and retain more of your hard-earned income.