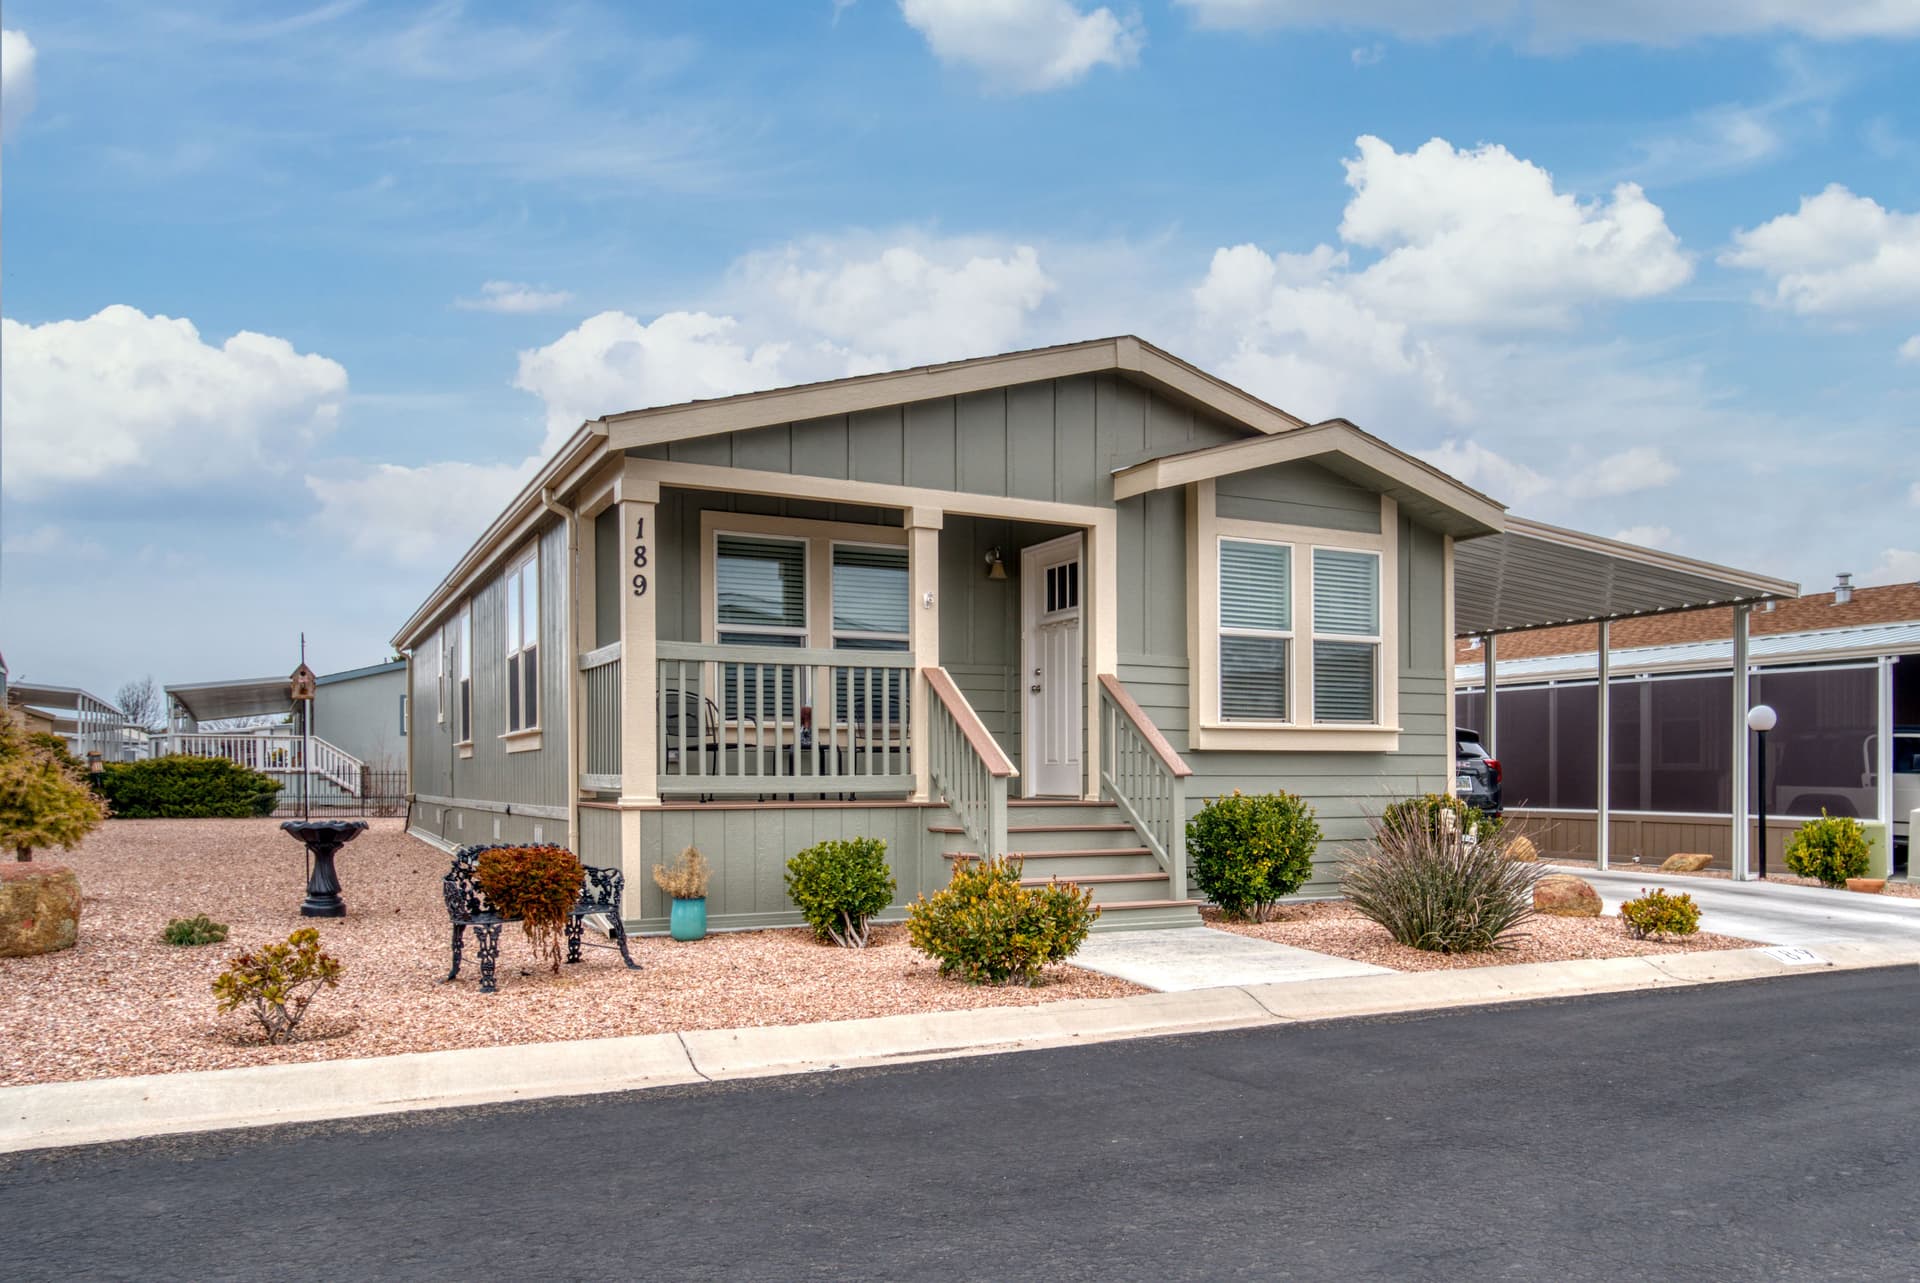
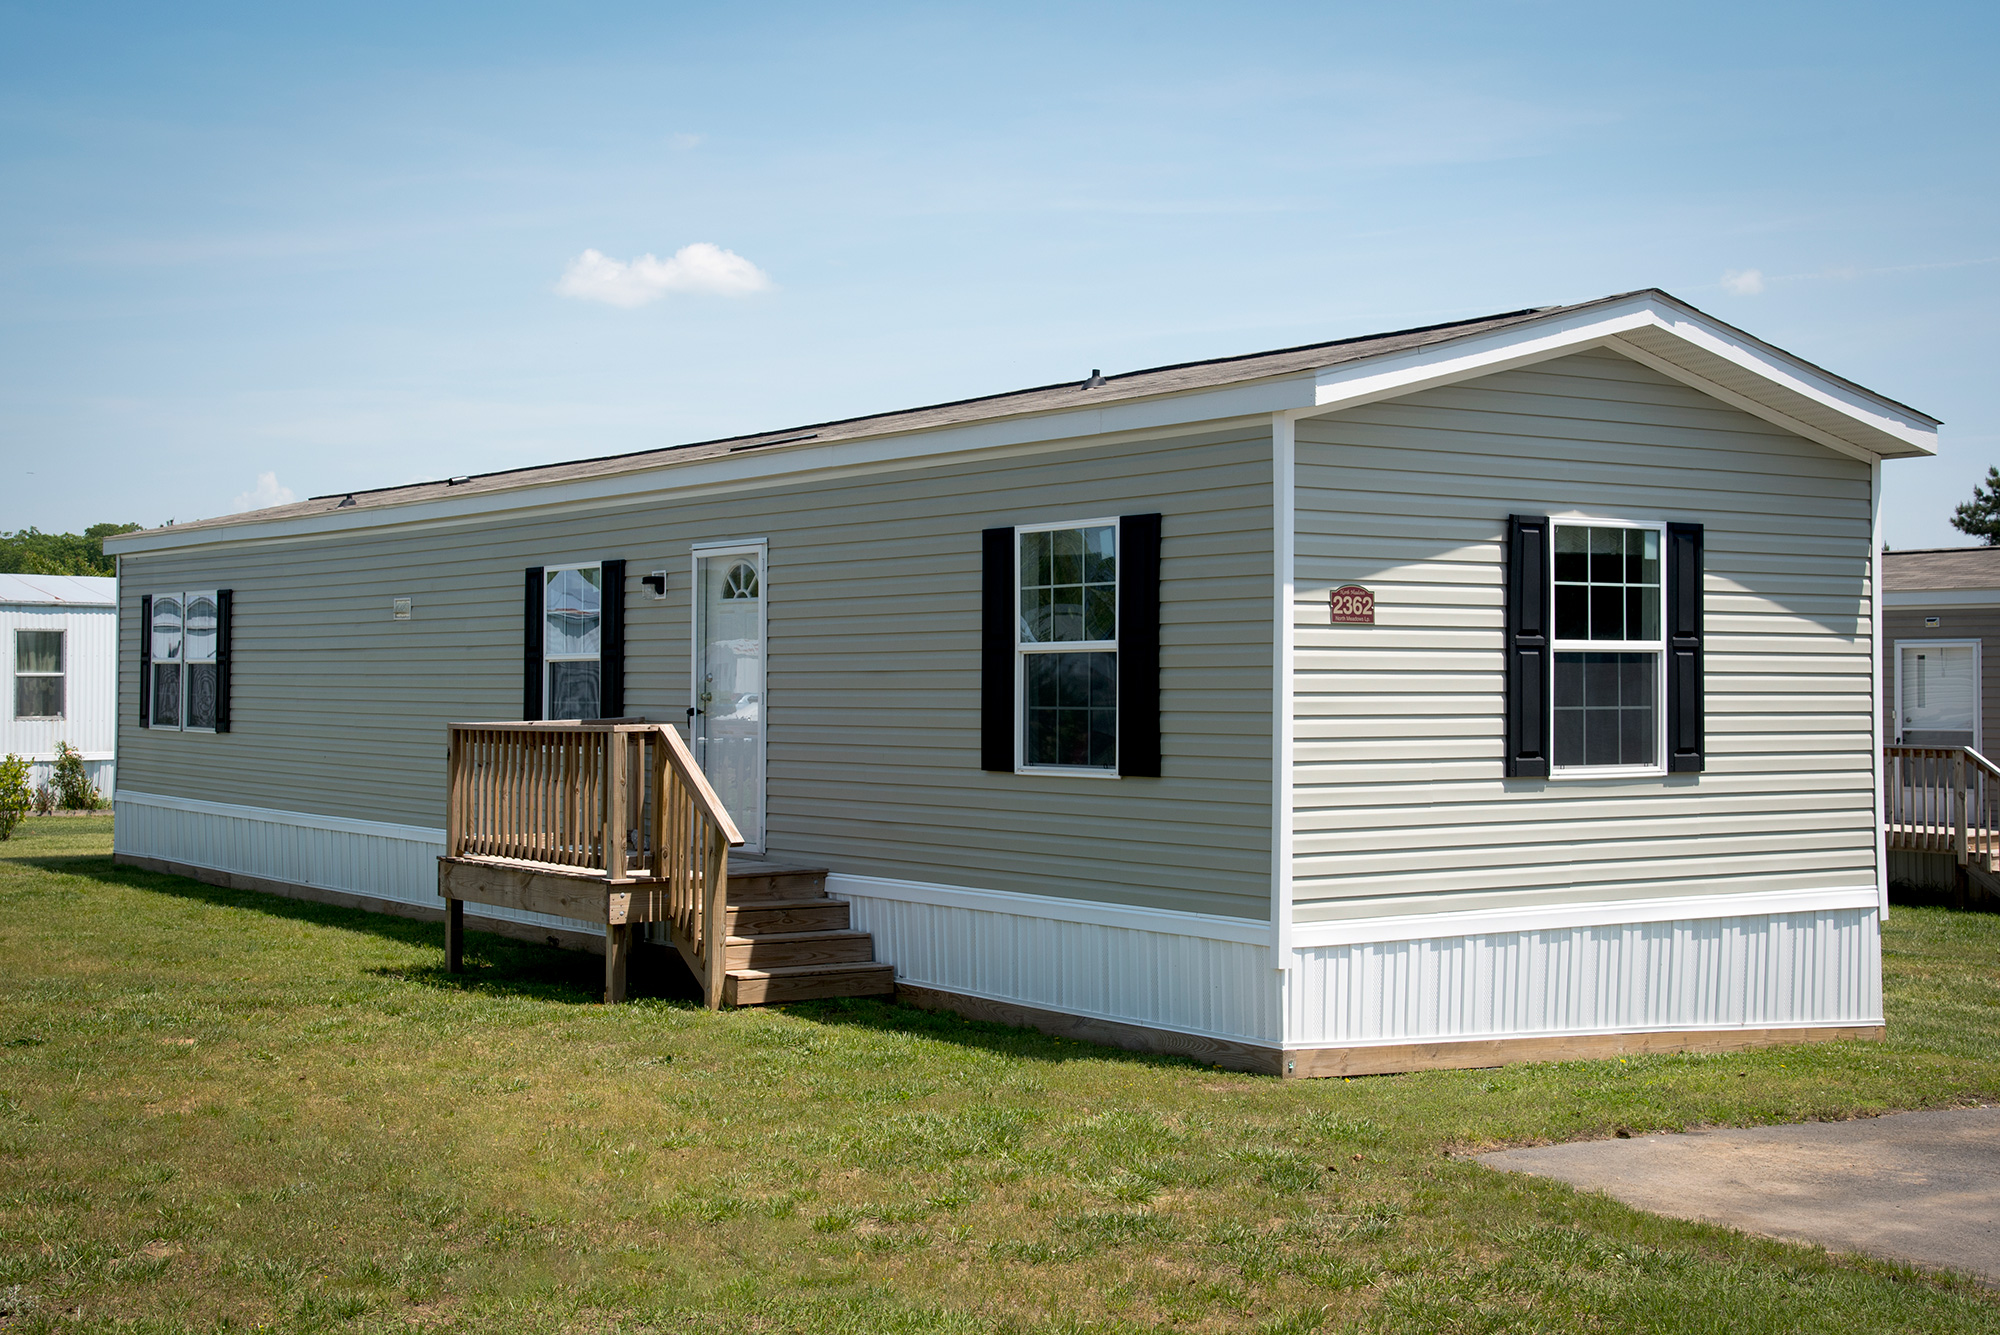
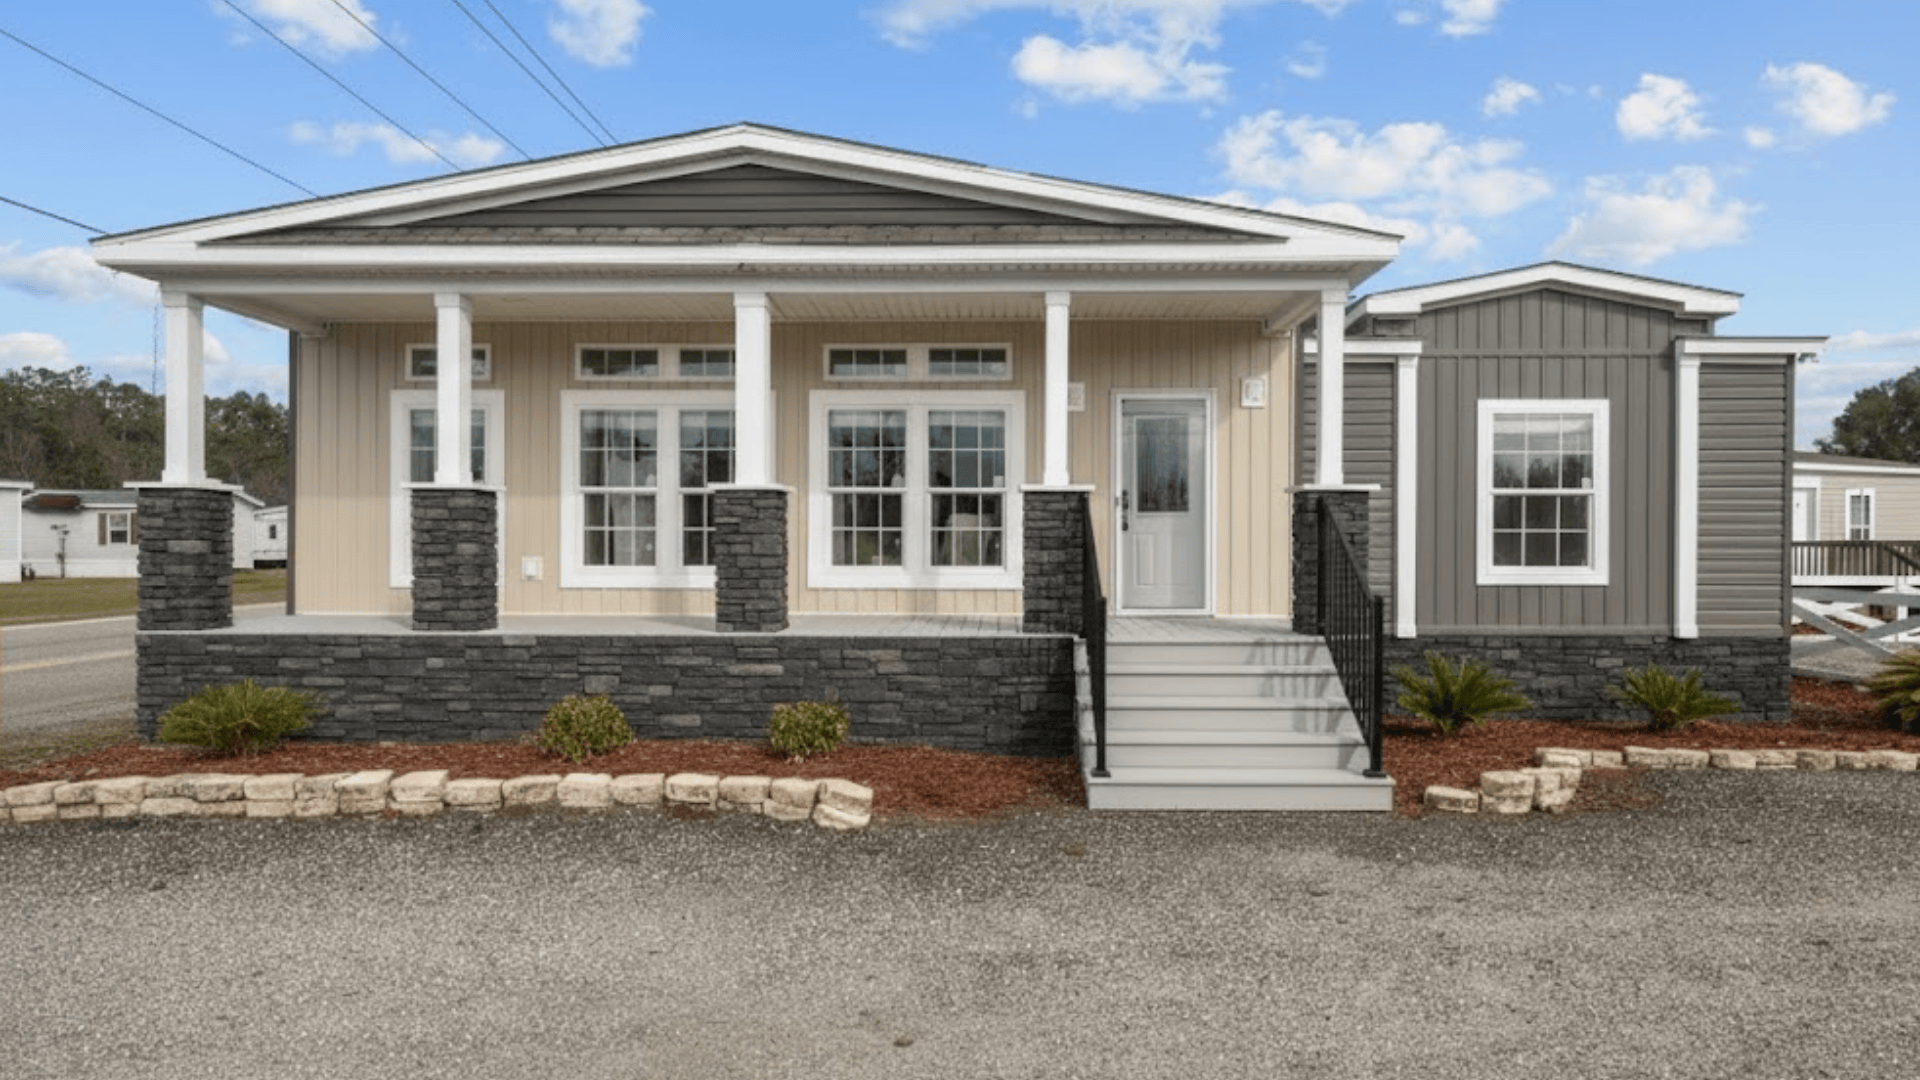
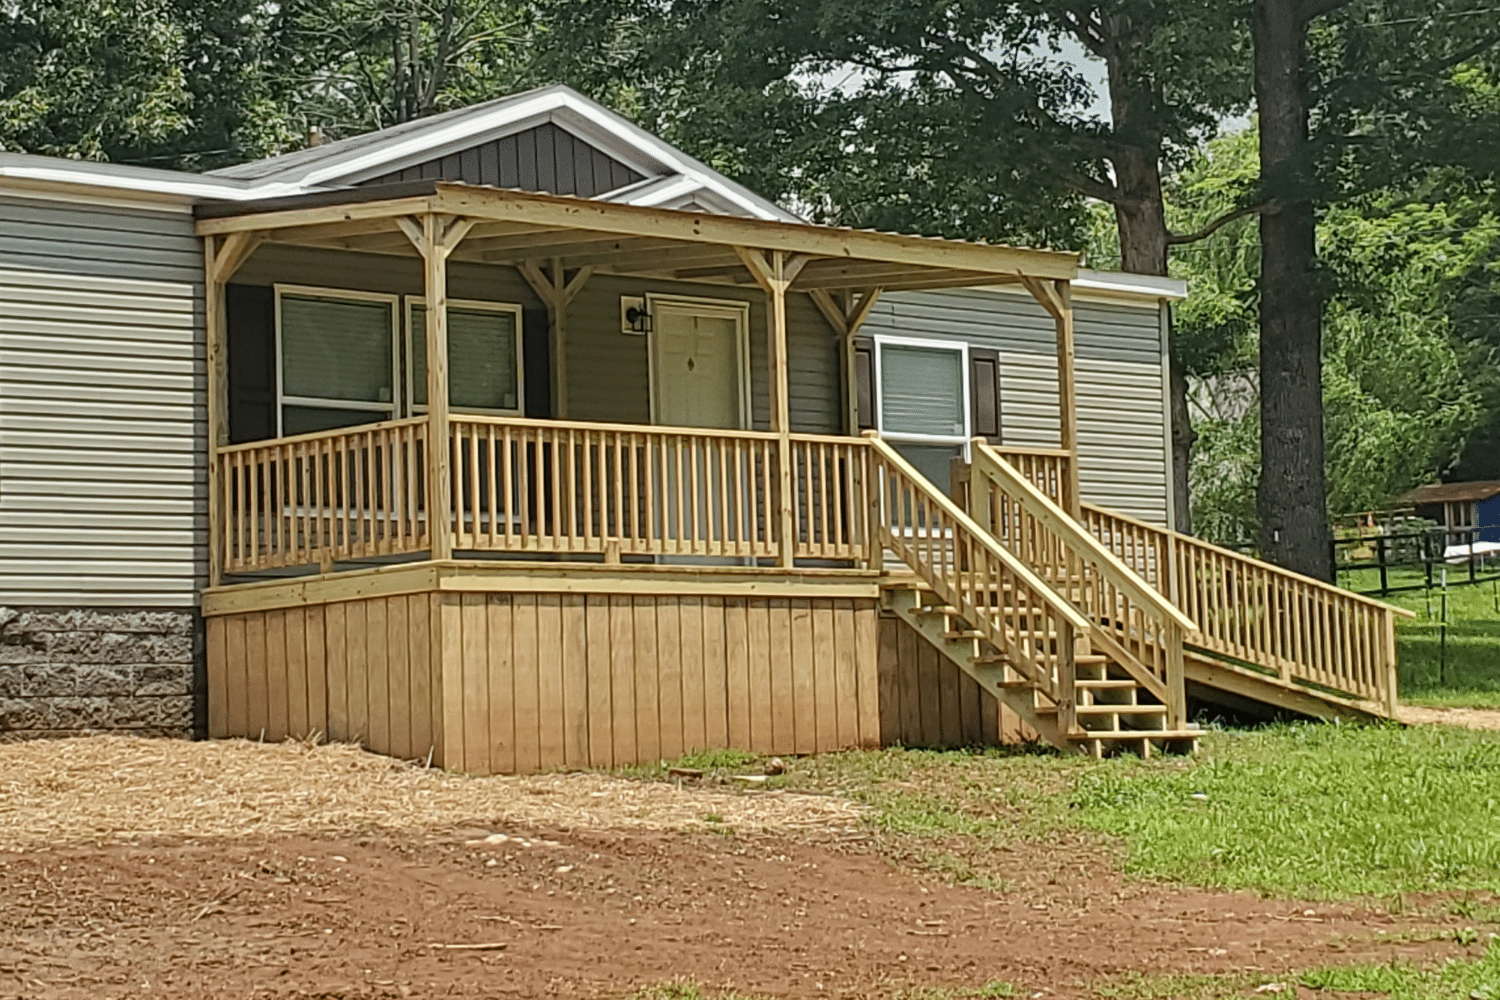
A mobile home is a prefabricated residential structure built entirely in a controlled factory environment on a permanent chassis, designed to be transported to a site—either a rented space in a manufactured home community or privately owned land—where it serves as a permanent, year-round dwelling.
Introduction and Core Definitions
The terminology surrounding manufactured housing has evolved significantly over the decades, leading to frequent confusion among prospective buyers, real estate investors, and local policymakers. To understand what a mobile home is today, it is essential to distinguish between historical designations, modern manufacturing standards, and legal classifications.
Historically, any prefabricated dwelling built on a chassis prior to 1976 was commonly referred to as a mobile home. However, the paradigm shifted permanently with the enactment of the National Manufactured Housing Construction and Safety Standards Act of 1974, enforced by the U.S. Department of Housing and Urban Development (HUD). Since June 15, 1976, homes built to these federal standards are legally classified as "manufactured homes," whereas the term "mobile home" technically applies only to units constructed prior to that date. Despite this legal distinction, the vernacular "mobile home" remains deeply entrenched in public discourse.
Navigating the market for factory-built housing requires a firm grasp of these definitions because financing, insurance underwriting, and municipal zoning laws treat pre-1976 mobile homes very differently from post-1976 HUD-code manufactured homes. Furthermore, modular homes—which are also built in factories—differ fundamentally because they are transported to a site and assembled on a permanent foundation to comply with local site-built residential building codes rather than the federal HUD code. Recognizing these structural and regulatory boundaries ensures that buyers, sellers, and property owners approach the market with accurate expectations regarding safety, valuation, and legal rights.
Construction Standards and Federal Regulations
The safety, structural integrity, and energy efficiency of modern factory-built housing are governed strictly by federal oversight rather than localized building codes. This federal preemption ensures uniformity across state lines, allowing manufacturers to build standardized units efficiently while maintaining rigorous safety thresholds.
The HUD Code Framework
The HUD code dictates strict requirements for structural design, wind resistance, thermal protection, fire safety, and energy efficiency. Unlike traditional site-built homes that must satisfy municipal building inspectors at various stages of construction, manufactured homes undergo exhaustive quality assurance inspections directly within the factory setting. Independent, HUD-certified inspection agencies monitor plant procedures, examine raw materials, and review construction methodologies. Every completed section of a manufactured home receives a red metal certification label—commonly referred to as a HUD tag—affixed to the exterior. This tag serves as permanent proof that the structure complies with all applicable federal safety and construction standards.
Wind Zones and Thermal Zones
The United States is divided into distinct zones for wind resistance and thermal performance under the HUD code, directly impacting how a home must be engineered:
- Wind Zones: The country is categorized into Wind Zone I, Wind Zone II, and Wind Zone III. Wind Zone I covers standard inland areas, while Wind Zone III encompasses hurricane-prone coastal regions requiring reinforced roof trusses, heavy-duty anchoring systems, and impact-resistant exterior wall assemblies.
- Thermal Zones: Thermal Zones 1, 2, and 3 dictate the minimum insulation values (R-values) required for floors, walls, and roofs. Homes destined for colder northern climates (Thermal Zone 3) feature significantly higher insulation levels and advanced vapor barriers compared to units built for milder southern regions.
Types of Mobile and Manufactured Homes
Factory-built housing configurations are categorized primarily by their physical dimensions and transport methodology. Selecting the appropriate configuration depends heavily on lot size, family size, transportation logistics, and municipal zoning constraints.
Single-Wide Homes
Single-wide manufactured homes are constructed as a single transportable unit, typically measuring between 14 and 18 feet in width and ranging from 56 to 76 feet in length.
- Advantages: They generally offer lower purchase prices, require smaller lots, and incur lower installation and utility connection expenses.
- Disadvantages: Interior floor space is inherently limited, and placement options within modern urban or suburban communities can be restricted by local zoning ordinances that favor multi-section layouts.
Multi-Section Homes
Multi-section homes—most commonly double-wides or triple-wides—consist of two or more independent units transported separately to the site and joined together on a permanent foundation. Double-wides typically offer 20 feet or more in width, creating expansive floor plans that mirror traditional site-built suburban houses.
- Advantages: They provide significantly more square footage, customizable room configurations, higher potential appraisal values, and greater architectural variety.
- Disadvantages: They require larger parcels of land or wider community spaces, involve complex transportation logistics, and demand higher setup and foundation costs.
| Feature / Aspect | Single-Wide Homes | Multi-Section (Double/Triple-Wide) Homes | Modular Homes |
|---|---|---|---|
| Governing Code | Federal HUD Code | Federal HUD Code | Local/State Site-Built Building Codes |
| Foundation Type | Piers, anchors, and tie-downs (skirting) | Piers, anchors, or permanent crawl space/basement | Permanent perimeter foundation (crawl space/basement) |
| Average Width | 14 to 18 feet | 24 to 32+ feet (joined on-site) | Varies widely based on architectural plan |
| Mobility Potential | High (can be towed on chassis) | Moderate (transported in sections, reassembled) | Low (permanently affixed to foundation) |
| Financing Vehicle | Personal property (chattel) loan or specialty mortgage | Chattel loan or conventional real estate mortgage | Standard conventional real estate mortgage |
Land Ownership and Community Placement
One of the most consequential decisions a buyer faces is determining where to place the home. The chosen location influences ongoing monthly expenses, legal rights, property appreciation potential, and lifestyle flexibility.
Placing a Home on Owned Land
Owning the underlying real estate provides the greatest degree of long-term stability and financial upside. When a manufactured home is permanently affixed to privately owned land, it is frequently classified as real property rather than personal property. This legal reclassification opens access to traditional, low-interest real estate mortgages and allows the home and land to appreciate in value as a unified asset. However, buyers must verify local zoning laws, secure necessary building permits, install engineered foundations, and arrange for independent utility connections—including well, septic, or municipal water and sewer lines.
Renting Space in a Manufactured Home Community
Placing a home within an established land-lease community—often managed by commercial operators or resident-owned cooperatives—involves paying monthly space rent.
- Community Amenities: Many communities offer amenities such as paved streets, street lighting, clubhouses, swimming pools, and gated security.
- Community Rules: Residents must adhere to community guidelines regarding exterior maintenance, pet policies, vehicle parking, and architectural modifications.
- Financial Considerations: While initial capital requirements are lower because land purchase costs are eliminated, monthly space rent is subject to periodic increases, and relocating the home later involves substantial financial expense.
Financing and Insurance Options
Securing capital and protecting physical assets require specialized financial products tailored to the unique legal status of factory-built housing.
Chattel Loans vs. Mortgages
Because older or single-wide mobile homes are legally categorized as personal property (chattel) when located on leased land, traditional real estate mortgages cannot be utilized. Instead, buyers obtain chattel loans, which function similarly to auto loans. Chattel loans typically carry higher interest rates and shorter repayment terms than traditional mortgages. Conversely, when a modern multi-section manufactured home is permanently attached to owned land and converted to real property status, borrowers qualify for conventional government-backed loans, including FHA Title I, FHA 203(b), VA loans, and USDA rural development loans.
Homeowners Insurance Considerations
Insuring a mobile or manufactured home requires specialized coverage due to construction differences and wind vulnerability. Insurers evaluate the age of the structure, the presence of HUD certification labels, roofing materials, and the quality of the anchoring system. Comprehensive policies generally cover fire, windstorm, vandalism, and personal liability. Homeowners residing in designated wind-prone regions or flood zones must secure supplementary riders, as standard policies frequently exclude catastrophic storm surges or rising water damage.
Common Operational and Maintenance Challenges
Proactive maintenance safeguards the structural longevity and safety of factory-built homes. Because these structures utilize lightweight building materials and specialized mechanical systems, neglecting routine upkeep can lead to costly degradation.
Leveling and Stabilization
Settling is a natural occurrence for homes installed on piers and ground anchors. Over time, soil expansion, contraction, and moisture fluctuations can cause the chassis to shift slightly. Routine inspections by licensed contractors are necessary to verify that the home remains level. An unlevel structure leads to sticking doors, jammed windows, stress cracks in drywall, and structural strain on framing joints.
Moisture Control and Skirting
Skirting—the material enclosing the perimeter crawl space between the ground and the floor joists—serves an essential thermal and protective function. Skirting must include adequate ventilation openings to prevent moisture accumulation beneath the floorboards, which can otherwise trigger wood rot, mold proliferation, and rust on the steel chassis. Additionally, insulation wrap around water supply lines located within the crawl space requires diligent monitoring to prevent freezing during severe winter conditions.
Frequently Asked Questions
What is the difference between a mobile home and a manufactured home?
The distinction is primarily chronological and legal. The term "mobile home" formally refers to factory-built housing constructed before June 15, 1976. On that date, the HUD construction code took effect, legally redesignating subsequent units as "manufactured homes" and imposing rigorous federal safety standards.
Can a mobile home be financed with a traditional mortgage?
Yes, but specific conditions must be met. If the home is located on leased land in a community, it cannot receive a traditional mortgage and requires a chattel loan. If the home is permanently affixed to land owned by the borrower and legally converted to real property, it qualifies for standard conventional and government-backed mortgages.
Do mobile homes appreciate in value over time?
Historically, mobile homes placed on rented land depreciate similarly to automobiles due to the loss of underlying land value. However, manufactured homes placed on privately owned land and permanently attached to a foundation appreciate at rates comparable to traditional site-built homes, driven primarily by the appreciation of the real estate itself.
What are HUD tags, and why are they important?
HUD tags are metal certification labels affixed to the exterior of every manufactured home section. They verify that the home was built in compliance with federal construction and safety standards. Lenders, insurance companies, and municipal zoning boards frequently require proof of these tags before approving loans, policies, or permits.
Are mobile homes safe during severe weather events?
Modern manufactured homes built to HUD Wind Zone specifications offer structural safety comparable to site-built homes during high winds, provided they are properly installed with engineered anchoring and tie-down systems. Residents should always follow local emergency evacuation protocols during severe weather events such as tornadoes or hurricanes.
Conclusion and Next Actions
Investing in or owning a mobile home demands careful evaluation of legal classifications, land ownership rights, and specialized financing structures. Prospective buyers must prioritize verifying HUD certification, inspecting foundation stability, and reviewing local zoning or community lease agreements before committing capital. For current owners, maintaining proper leveling, moisture barriers, and adequate insurance coverage ensures long-term structural integrity and asset preservation. To proceed, consult licensed local housing inspectors, qualified lenders specializing in chattel or manufactured housing finance, and municipal planning departments to verify site-specific regulatory requirements.