Navigating NJ Medicare requires understanding Original Medicare, Medicare Advantage, Medigap supplements, and state-specific assistance programs like NJ FamilyCare and PAAD. Residents can choose between federal Original Medicare and private plan alternatives, while qualifying low-income individuals can leverage state assistance to significantly reduce out-of-pocket medical and prescription drug expenses.
Introduction to Medicare in New Jersey
Navigating the healthcare landscape in New Jersey can feel overwhelming, particularly for individuals approaching age 65 or those qualifying earlier due to a disability. Medicare is a federal health insurance program, but the choices you make—ranging from how you receive your benefits to how you protect yourself against catastrophic out-of-pocket costs—depend heavily on the state-specific resources available to you. In New Jersey, Medicare beneficiaries have access to a robust network of healthcare providers, specialized regional health maintenance organizations (HMOs), preferred provider organizations (PPOs), and critical state-level financial assistance programs designed to bridge the gap between federal coverage and personal affordability.
Understanding how Medicare operates in the Garden State involves examining federal baselines and state overlays. While the core rules governing Part A (hospital insurance) and Part B (medical insurance) remain uniform across the United States, New Jersey offers unique supplementary pathways, prescription assistance programs, and consumer protection regulations that dictate how private insurance companies operate within state lines. Whether you are enrolling for the first time, evaluating an annual change to your coverage, or attempting to assist an aging family member, a structured approach is essential to securing comprehensive, cost-effective healthcare.
The Core Structure of Medicare: Parts A, B, C, and D
Before evaluating New Jersey-specific options, every beneficiary must understand the foundational structure of the federal Medicare program. Medicare is divided into distinct parts, each covering specific types of medical services, supplies, and pharmaceutical needs.
Medicare Part A: Hospital Insurance
Medicare Part A helps cover inpatient hospital stays, care in a skilled nursing facility, hospice care, and some home health care. For most individuals, Part A is premium-free if you or your spouse paid Medicare taxes while working for at least 10 years (40 quarters). If you do not qualify for premium-free Part A, you can purchase it by paying a monthly premium. Part A comes with deductibles and coinsurance for inpatient stays, meaning it does not cover 100% of hospital costs without secondary insurance.
Medicare Part B: Medical Insurance
Medicare Part B covers medically necessary services—such as doctor visits, outpatient care, preventative services, and durable medical equipment—as well as some preventative health screenings. Unlike Part A, all beneficiaries pay a monthly premium for Part B, which is typically deducted directly from their Social Security benefits. Part B also features an annual deductible and a standard 20% coinsurance for most doctor services, with no annual out-of-pocket maximum under standard Original Medicare.
Medicare Part C: Medicare Advantage
Often referred to as an "All-in-One" alternative, Medicare Advantage plans are offered by private insurance companies approved by Medicare. These plans bundle Part A, Part B, and usually Part D (prescription drug coverage) into a single plan. Many New Jersey Medicare Advantage plans offer extra benefits not covered by Original Medicare, such as routine dental, vision, hearing, and wellness program memberships. However, these plans often utilize specific provider networks (HMO or PPO) and may require prior authorizations for specialized medical procedures.
Medicare Part D: Prescription Drug Coverage
Prescription drug coverage is vital for managing chronic conditions and everyday health needs. Part D plans are sold by private insurance companies approved by the federal government. Every Part D plan has a formulary—a list of covered drugs—and organizes medications into tiers that dictate your copayment or coinsurance costs. New Jersey residents can choose from a wide array of standalone Part D prescription plans if they stay with Original Medicare, or they can select a Medicare Advantage plan that includes prescription drug coverage (MAPD).
Comparing Your Medicare Coverage Paths in New Jersey
When you become eligible for Medicare in New Jersey, you face a major structural decision: stick with Original Medicare supplemented by private insurance, or enroll in a Medicare Advantage plan. Each path has distinct operational mechanics, cost structures, and network restrictions.
| Feature / Consideration | Original Medicare (Parts A & B) + Medigap + Part D | Medicare Advantage (Part C) |
|---|---|---|
| Network Restrictions | See any doctor or hospital nationwide that accepts Medicare. No referrals needed. | Generally restricted to regional networks (HMO/PPO). Referrals often required for specialists. |
| Out-of-Pocket Costs | Predictable costs if paired with a Medigap policy. No annual out-of-pocket maximum on standard Medicare alone. | Includes a strict annual out-of-pocket maximum for in-network care, protecting against high medical bills. |
| Extra Benefits | Rarely includes routine dental, vision, or hearing unless purchased separately. | Frequently bundles extra benefits like dental, vision, hearing, and gym memberships. |
| Prescription Drug Coverage | Requires purchasing a separate standalone Medicare Part D prescription drug plan. | Most plans bundle prescription drug coverage (MAPD) directly into the package. |
| Underwriting & Premiums | Medigap policies may require medical underwriting if purchased outside initial enrollment periods. | Premiums can be low or $0, but you must continue paying your Part B premium. |
New Jersey Medigap (Medicare Supplement) Insurance
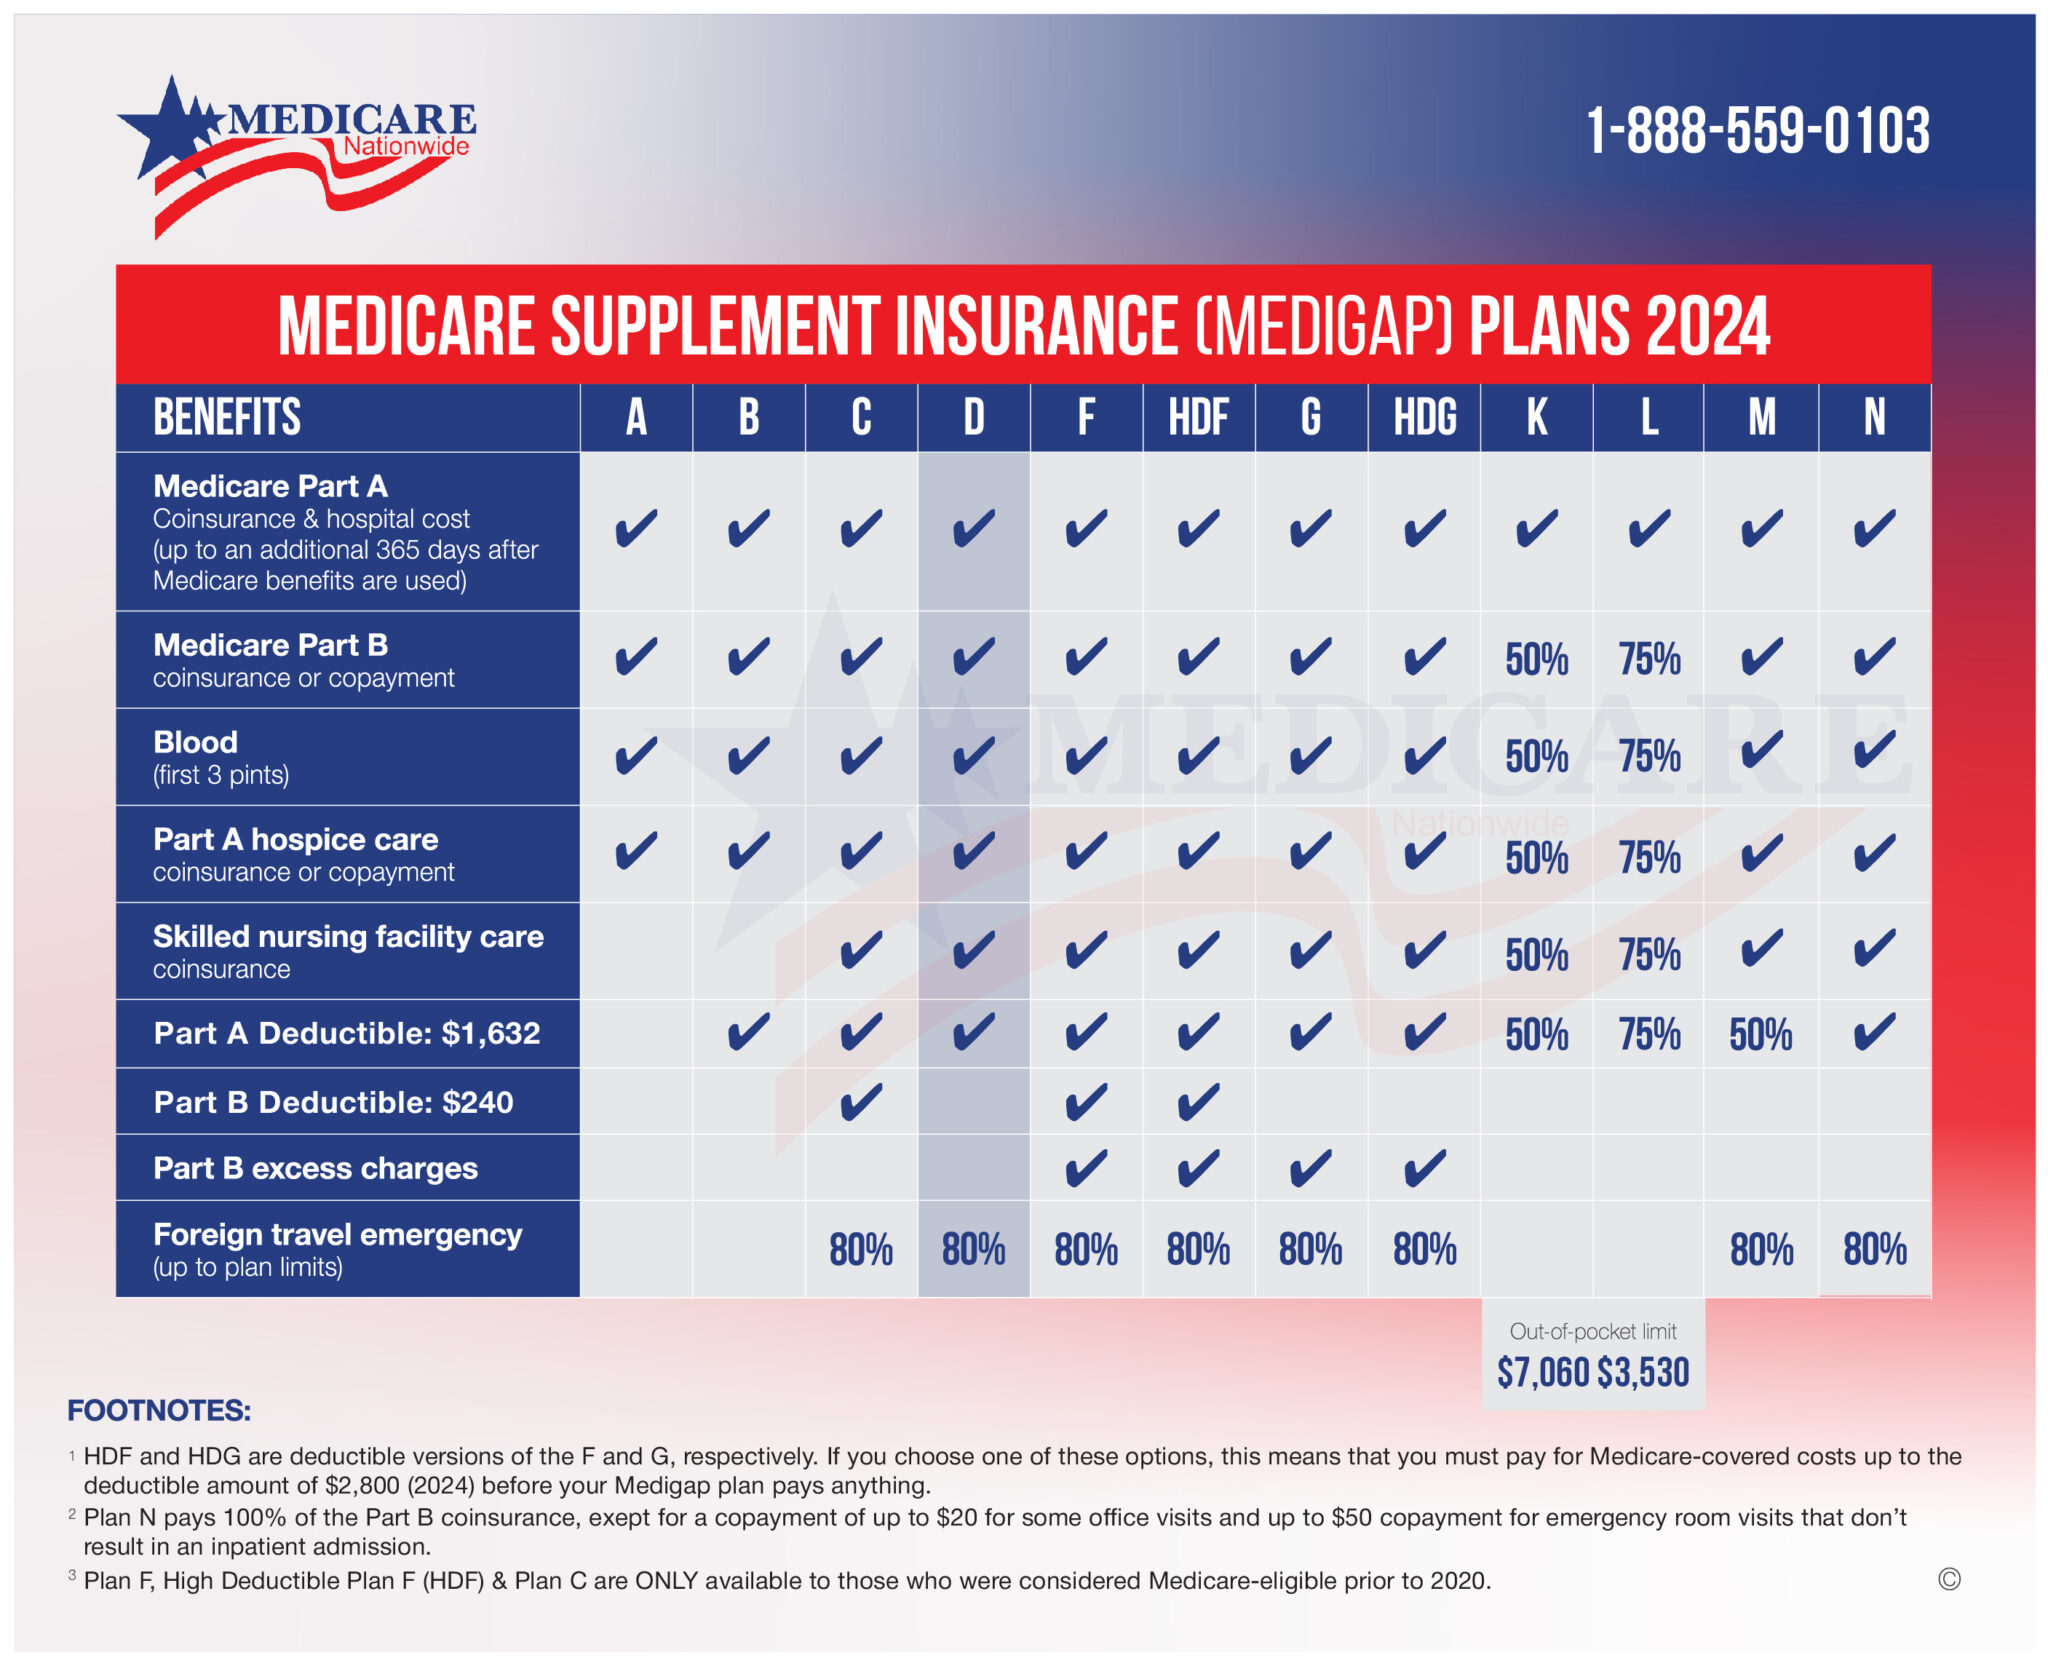
Because Original Medicare leaves you exposed to 20% coinsurance, deductibles, and a lack of annual out-of-pocket caps, many New Jersey residents purchase a Medicare Supplement Insurance (Medigap) policy. Regulated by both federal and state laws, Medigap policies are sold by private insurance companies to fill the "gaps" in Original Medicare.
Standardized Plan Letters
Medigap plans are identified by letters (such as Plan G, Plan N, and Plan A). Each standardized plan with the same letter offers the exact same basic benefits, regardless of which insurance company sells it. For example, a Plan G purchased from Company A provides identical core benefits to a Plan G purchased from Company B. The only differences among companies are customer service ratings, stability, and monthly premiums.
New Jersey Medigap Open Enrollment Window
The optimal time to buy a Medigap policy in New Jersey is during your Medigap Open Enrollment Period. This is a one-time, six-month window that begins the month you turn 65 and are enrolled in Medicare Part B. During this window:
- Insurance companies cannot deny you coverage or charge you higher premiums due to pre-existing health conditions (medical underwriting is prohibited).
- You have guaranteed issue rights to any Medigap policy sold in the state.
If you miss this window and attempt to purchase a Medigap policy later, insurers in New Jersey can evaluate your medical history through underwriting and may deny coverage or charge significantly higher rates based on your health status.
State-Specific Financial Assistance Programs for NJ Medicare Beneficiaries
New Jersey offers robust state-sponsored programs to assist low-to-moderate-income seniors and individuals with disabilities in covering Medicare premiums, deductibles, and prescription medication costs.
1. New Jersey Medicare Savings Programs (MSPs)
Administered through the state Medicaid office, Medicare Savings Programs help pay for Medicare Part B premiums, deductibles, and coinsurance. Depending on your income and asset levels, you may qualify for one of three main tiers:
- Qualified Medicare Beneficiary (QMB): Helps pay for Part A and Part B premiums, as well as Medicare deductibles, coinsurance, and copayments.
- Specified Low-Income Medicare Beneficiary (SLMB): Helps pay for your monthly Medicare Part B premium.
- Qualifying Individual (QI): Also helps pay for the Part B premium, granted on a first-come, first-served basis with priority given to those who received assistance the previous year.
2. Pharmaceutical Assistance to the Aged and Disabled (PAAD)
New Jersey’s PAAD program is a state-funded prescription assistance program designed to help eligible older adults and disabled individuals save money on brand-name and generic medications. PAAD sets a flat copayment cap for covered prescriptions, shielding beneficiaries from catastrophic drug costs. To qualify, residents must meet specific annual income limits and be at least 65 years of age or receiving Social Security Disability benefits.
3. Senior Gold Prescription Discount Program
For New Jersey residents whose incomes exceed the PAAD eligibility limits but fall below higher thresholds, the Senior Gold Prescription Discount Program offers an alternative. Members pay a fixed percentage of the prescription cost plus a small copayment, ensuring continued access to discounted medications even if they earn slightly too much for traditional PAAD benefits.
Key Enrollment Windows and Deadlines
Timing is everything in the Medicare ecosystem. Missing official enrollment windows can result in permanent financial penalties, delayed coverage, and out-of-pocket exposure.
Initial Enrollment Period (IEP)
Your Initial Enrollment Period is your first chance to sign up for Medicare. It lasts for 7 months:
- The 3 months before the month you turn 65,
- Your birthday month, and
- The 3 months following your birthday month.
Annual Enrollment Period (AEP)
Running from October 15 to December 7 each year, the Annual Enrollment Period allows all Medicare beneficiaries to make changes to their coverage. During this window, you can:
- Switch from Original Medicare to a Medicare Advantage plan (or vice versa).
- Switch from one Medicare Advantage plan to another.
- Enroll in, drop, or switch a Medicare Part D prescription drug plan.
Changes made during AEP take effect on January 1 of the following year.
Medicare Advantage Open Enrollment Period (MAOEP)
Running from January 1 to March 31 annually, this period is exclusively for individuals already enrolled in a Medicare Advantage plan. During this timeframe, you can switch to a different Medicare Advantage plan or drop your Advantage plan and return to Original Medicare, adding a standalone Part D plan if needed.
Navigating Enrollment Challenges and Common Mistakes
Navigating the complexities of Medicare leaves room for costly errors. Awareness of common pitfalls ensures a smoother enrollment process.
Delaying Part B Without Creditable Coverage
If you are still working past age 65 and have employer-sponsored health insurance, you may be able to delay enrolling in Medicare Part B without penalty. However, you must verify that your employer coverage is considered "creditable coverage" by Medicare standards. Delaying Part B without qualifying employer coverage can trigger lifelong financial penalties added to your monthly Part B premium.
Confusing PAAD with Medicare Part D
Many New Jersey residents assume that state programs like PAAD replace the need for a Medicare Part D plan. In reality, PAAD works in conjunction with Medicare Part D. Beneficiaries must still enroll in an approved Medicare Part D plan, and PAAD helps cover the remaining out-of-pocket costs and copayments associated with that plan.
Free, Unbiased Assistance: NJ PAIC and SHIP
Navigating plan options, checking formularies, and calculating total annual costs can be daunting. Fortunately, New Jersey provides free, confidential, and unbiased counseling through the State Health Insurance Assistance Program (SHIP).
New Jersey SHIP is part of a national network supported by the Administration for Community Living. SHIP counselors do not sell insurance, work for private carriers, or receive commissions. They provide personalized guidance to help you evaluate your options, check drug pricing, review Medicare Summary Notices, and understand your rights under federal and state law. You can connect with your county's local SHIP office through the New Jersey Department of Human Services or via local senior centers.
Conclusion and Recommended Next Actions
Securing the right healthcare coverage in New Jersey requires a careful assessment of your medical needs, financial situation, and preferred provider networks. Start by reviewing your current health status and anticipated medication needs for the coming year. Next, verify your eligibility dates and mark your calendar for essential enrollment windows. If you need personalized support, contact your local New Jersey SHIP office to schedule a consultation with an unbiased counselor. Taking these proactive steps ensures you secure a stable, comprehensive healthcare foundation.