Finding a bank notary can save you time and money when you need to authenticate signatures, verify identities, and execute legal, financial, or real estate documents. Many major financial institutions offer notary services, often free of charge or at a minimal cost for account holders, making them a practical alternative to independent mobile notaries or shipping store services.
Navigating the process of getting a document notarized requires understanding what a notary public actually does, which banks provide these services, what identification and paperwork are required, and the inherent limitations you might encounter. While the concept of notarization sounds straightforward—signing a document in the presence of an authorized official—specific institutional policies dictate whether your local branch can assist you. This guide examines how bank notaries operate, the steps you must take before visiting a branch, and how to ensure your notarization goes smoothly.
Understanding the Role of a Bank Notary Public
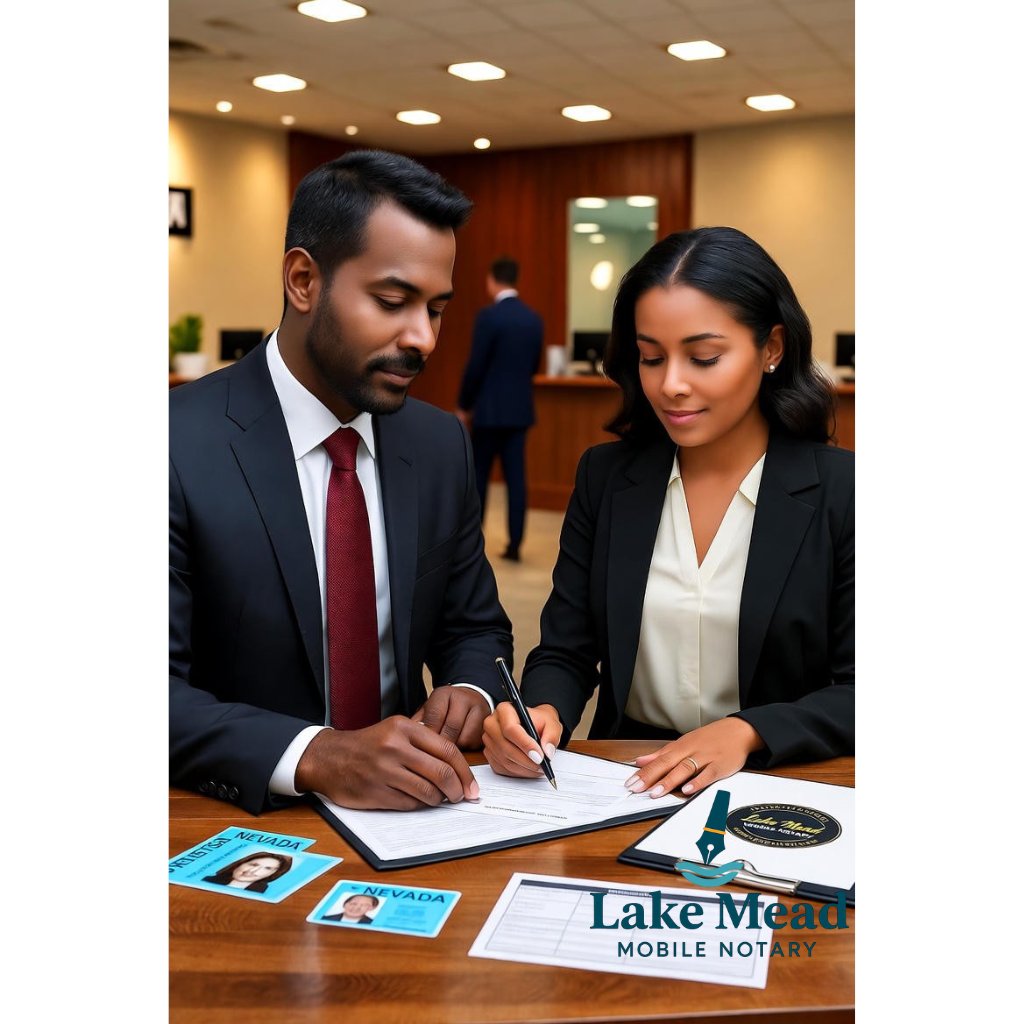
A bank notary is a public official appointed by state government authorities—typically the Secretary of State—to serve as an impartial witness in the signing of important documents. Within a banking environment, these employees hold their standard teller, customer service, or managerial roles while maintaining an active notary commission. Their primary legal function is to deter fraud by verifying the identity of the person signing the document, ensuring that they are signing willingly and under no duress, and administering oaths or affirmations when required.
It is important to understand that a bank notary acts only as an official witness to the signature, not as a legal advisor. They cannot draft documents, explain the legal implications of what you are signing, or choose the type of notarial act required for your paperwork. Attempting to ask a bank notary for legal guidance will generally result in a polite refusal, as doing so would violate state laws prohibiting the unauthorized practice of law.
Furthermore, bank notaries are bound by strict geographical and institutional boundaries. Their commission is tied to a specific state, meaning a notary commissioned in New York cannot notarize a document under Florida jurisdiction unless they hold a commission there (though some states allow cross-border notarizations under specific conditions). Additionally, banks have the legal right to establish internal corporate policies limiting the types of documents their employees are permitted to notarize during business hours.
Availability and Policies Across Major Financial Institutions
Not every bank branch employs a notary public, and those that do may not always have one on duty. Staff turnover, scheduling conflicts, lunch breaks, and part-time status often mean that an individual branch might temporarily lack active notarial coverage. Therefore, calling ahead before visiting a physical location is an essential step.
Major national banks handle notary services differently. For instance, institutions like Bank of America, Chase, and Wells Fargo often employ notaries across many of their retail branches, but their availability varies significantly by region and individual branch traffic. Some smaller credit unions and community banks also provide notary services exclusively as a courtesy perk for members in good standing, sometimes refusing service entirely to non-account holders.
| Financial Institution | Typical Account Holder Cost | Non-Customer Policy | Appointment Recommendation |
|---|---|---|---|
| Major National Banks (e.g., Chase, Bank of America) | Usually Free | Frequently Declined or Limited | Highly Recommended |
| Regional & Community Banks | Usually Free | Varies by Branch | Required |
| Credit Unions | Always Free | Usually Not Available | Recommended |
| Independent Mail Centers (e.g., UPS Store) | Varies ($10–$20 per signature) | Open to All | Walk-ins Welcome |
Fees charged by banks also vary. Many financial institutions offer free notary services as a retention benefit to checking or savings account holders. However, if you do not hold an account with the bank, they may either turn you away or charge a state-regulated per-signature or per-act fee. Understanding these institutional nuances prevents wasted trips and unexpected expenses.
Prerequisites and Preparation Before Visiting the Branch
Securing a successful notarization session at a bank depends heavily on proper preparation. Arriving at the teller counter or customer service desk without the correct documentation or with improperly prepared paperwork will cause the notary to turn you away.
Essential Identification Requirements
State laws universally require notaries to positively identify any signer before executing a notarial act. Acceptable forms of identification must be current, government-issued, and contain a photograph and signature. Common acceptable documents include:
- Valid driver’s licenses issued by any U.S. state.
- State-issued identification cards.
- U.S. passports or official passport cards.
- Permanent resident cards (Green Cards).
- U.S. military identification cards.
Expired identification documents are strictly unacceptable, even if they expired only a day prior. If your identification lacks a physical description or signature, some states permit secondary forms of identification, such as credit cards or employee badges, but relying on primary photo identification is always safest.
Document Completion Rules
One of the most common reasons bank notaries refuse to notarize documents is improper completion.
- Do not sign in advance: Most notarial acts require you to sign the document directly in front of the notary public. If you sign the document at home before arriving, the notary must refuse the service because they cannot witness your act of signing.
- Complete all blank spaces: Ensure that all blanks in the document are filled in or crossed out with a line. Notaries cannot notarize incomplete documents because blank spaces create vulnerabilities for post-signing fraudulent insertions.
- Verify witness requirements: If your document requires independent witnesses in addition to a notary, you must bring those individuals with you. Bank employees cannot act as witnesses for your personal documents due to liability risks and conflict-of-interest policies.
Types of Notarial Acts Performed at Banks
When you present a document to a bank notary, they will typically perform one of a few standard notarial acts. Knowing which act your document requires helps the notary quickly verify their capacity to complete the transaction.
- [Document Presented]
- Requires Oath/Affirmation?
- [Jurat] (e.g., Affidavits, Deposition)
- Acknowledging Signature?
- [Acknowledgment] (e.g., Deeds, Powers of Attorney)
- Requires Oath/Affirmation?
1. Acknowledgments
An acknowledgment is used to verify that a signer has executed a document voluntarily and understands its contents. During an acknowledgment, the signer declares to the notary that the signature on the document is their own. The document can be signed before arriving at the bank, but the signer must appear before the notary in person to confirm the signature's authenticity. This act is common for real estate deeds, trusts, and powers of attorney.
2. Jurats
A jurat requires the signer to sign the document in the presence of the notary and take an oath or affirmation swearing that the contents of the document are true and correct. Jurats are frequently used for affidavits, depositions, and financial statements submitted to courts or government agencies. Because an oath is involved, the signer must raise their right hand and verbally swear or affirm to the truthfulness of the statements.
3. Signature Witnessing
In some jurisdictions, a signature witnessing act is used when a document requires verification that a specific person signed it, but neither an oath nor a formal acknowledgment is mandated by the receiving agency. The process closely mirrors an acknowledgment, requiring physical presence and verified identification.
Operational Restrictions and Common Exclusions
While banks employ notaries to assist customers with routine financial and legal matters, corporate risk management departments place strict limitations on what bank notaries are allowed to handle. Understanding these restrictions prevents frustration when visiting a branch.
Many major banks explicitly prohibit their notaries from notarizing real estate closing documents, quitclaim deeds, or multi-page mortgage refinancing packages originating from third-party title companies or online mortgage brokers. These complex transactions require specialized closing agents or mobile notaries who can dedicate significant time to explaining loan terms—something a busy bank teller cannot do.
Additionally, bank notaries are generally barred from notarizing documents in which the bank itself has a direct financial or beneficial interest, unless permitted by specific state statutes. Furthermore, notaries cannot notarize documents for family members or spouses, as this creates an inherent conflict of interest that invalidates the legal integrity of the notarization. If a document is written in a foreign language that the notary cannot read or translate, or if the notary cannot communicate directly with the signer without an intermediary, they must decline the service to ensure informed consent and prevent fraud.
Step-by-Step Guide to Getting Your Document Notarized at a Bank
Executing your notarization efficiently involves a logical sequence of verification, preparation, and presentation. Follow these structured steps to ensure your visit succeeds on the first attempt.
- Verify Bank Availability: Call your local branch ahead of time. Ask specifically if an active notary public is scheduled to be on duty during the time you plan to arrive.
- Review Document Guidelines: Check your document for pre-signing instructions, required witness signatures, and the presence of proper notarial wording (the certificate block at the bottom or on a separate attached page).
- Gather Required Identification: Ensure all signers possess current, government-issued photo identification that matches the name listed on the documents exactly.
- Assemble All Signers: If multiple people must sign the document, every single signer must appear before the notary in person at the same time, bringing their respective identifications.
- Leave Signature Lines Blank: Keep your pen away from the signature line until the notary instructs you to sign in their physical presence.
- Present to the Notary: Approach the designated desk or teller, explain that you need a notarization, present your identification, and follow the notary's instructions regarding oaths or acknowledgments.
- Complete Payment (If Applicable): Pay any required non-customer fees as instructed by the bank representative.
Frequently Asked Questions About Bank Notaries
Are bank notary services always free?
No. While many banks provide notary services free of charge as a courtesy to their checking or savings account holders, policies vary widely. Non-customers are frequently charged a fee per signature or per document, and some institutions refuse service to non-account holders entirely. Always verify pricing policies before visiting.
Can a bank notary refuse to notarize my document?
Yes. A bank notary can and must refuse service under several legal and operational conditions. Common reasons for refusal include expired identification, the signer's inability to prove their identity, signs of coercion or mental incapacity, documents with blank spaces, or internal bank policies prohibiting specific document types like real estate deeds or wills.
Do I need to bring my own witnesses?
It depends on the document. If your paperwork requires independent witnesses (such as a will or certain contracts), you must bring them with you. Bank employees cannot act as witnesses for your personal documents due to corporate liability policies and potential conflicts of interest.
Can a bank notary notarize out-of-state documents?
Generally, yes, provided the document is governed by U.S. laws and does not require specialized international certification like an apostille. However, the notarial act itself must be performed within the physical state where the notary holds their official commission.
What happens if the name on my ID does not match my document?
The name on your government-issued photo identification must match the name on the document exactly. If you have recently married or changed your name legally, you must bring official documentation—such as a certified marriage certificate or court order—to bridge the discrepancy, or the notary must refuse service.
Conclusion and Next Actions
Utilizing a bank notary is one of the most accessible and cost-effective ways to authenticate essential documents, provided you approach the process with proper preparation. Start by confirming branch availability and verifying that your identification and paperwork meet all legal and institutional standards. By understanding what bank notaries can and cannot do, you can avoid unnecessary delays and complete your financial, legal, or personal transactions smoothly. For complex transactions like real estate closings or estate planning, contact your institution in advance or consult a specialized mobile notary service to ensure your specific document type is fully supported.