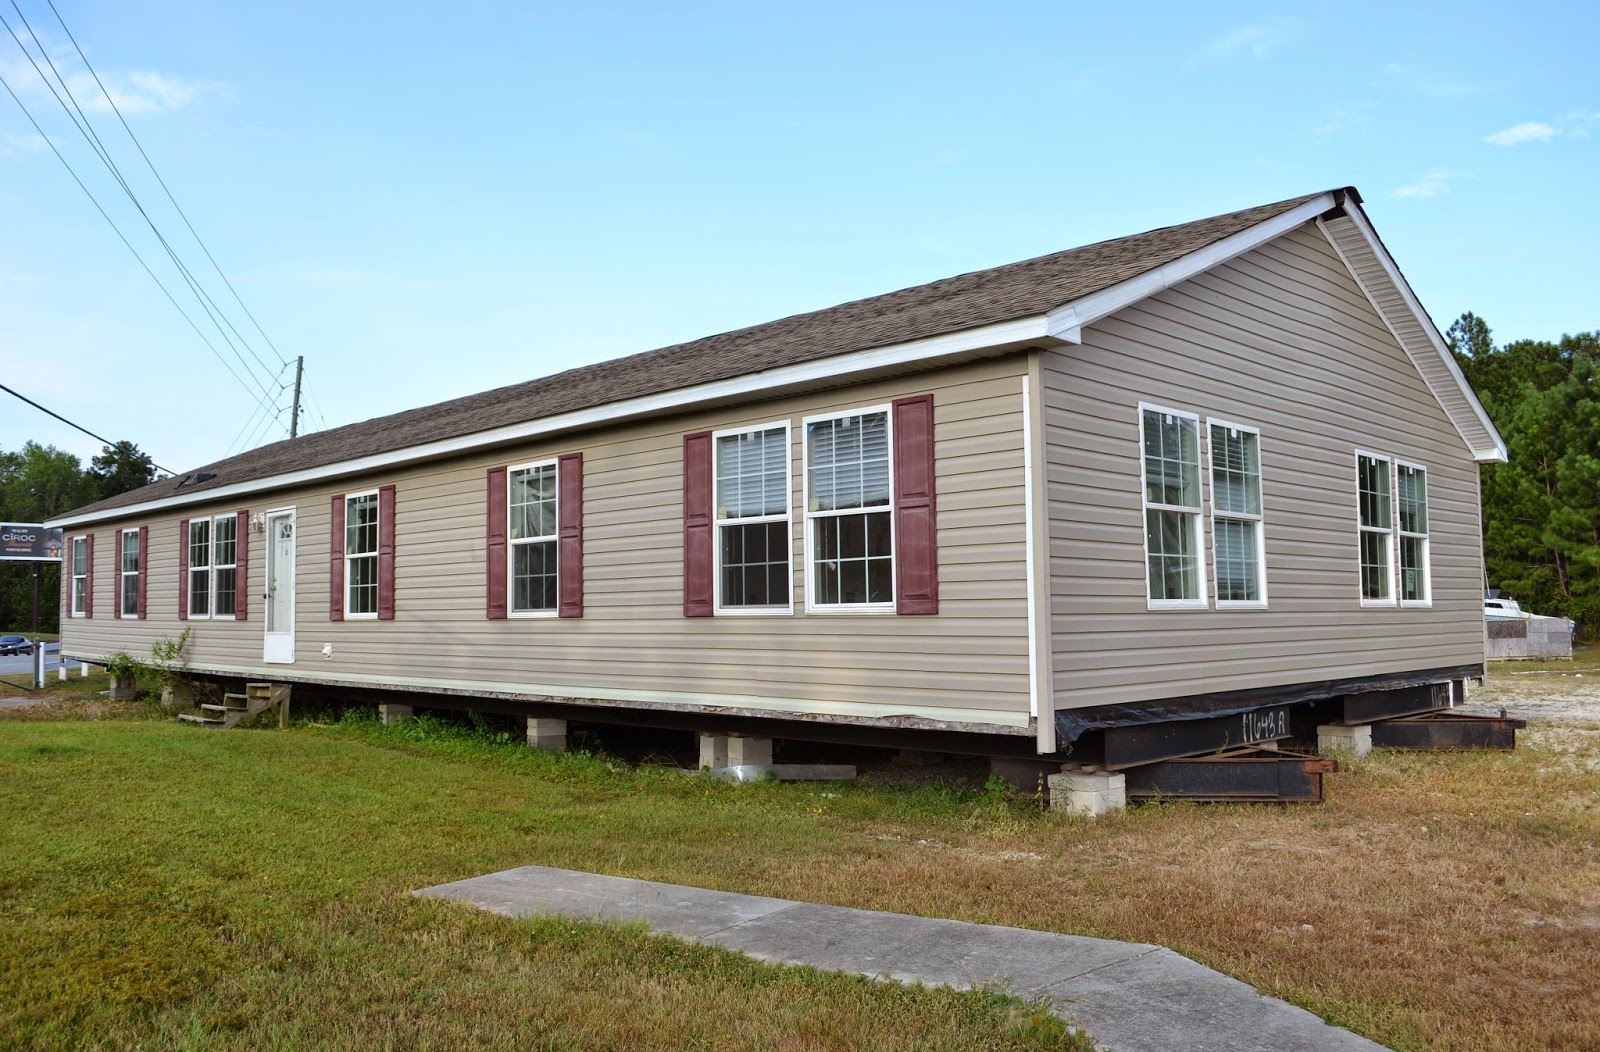
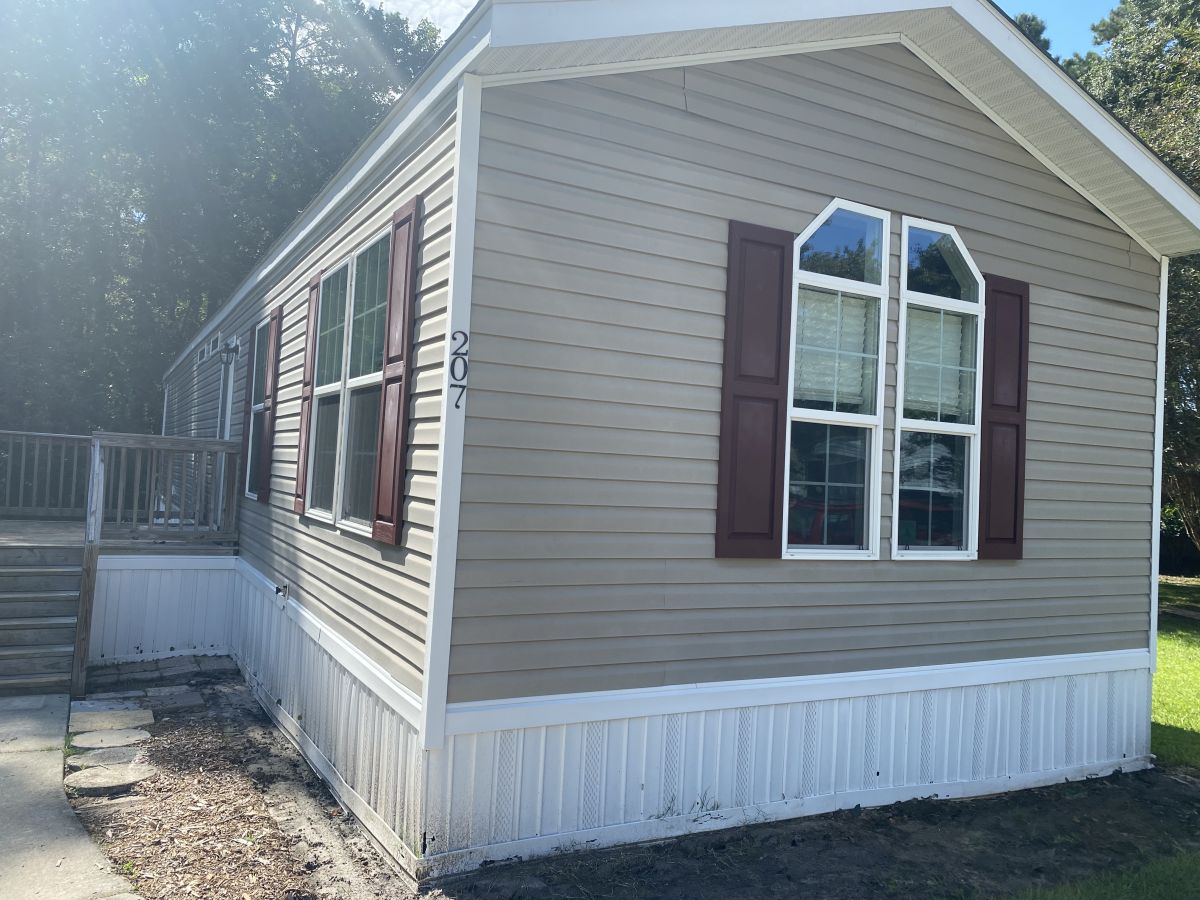
Navigating the real estate market for a used mobile home in Summerville, South Carolina requires a strategic approach that blends local knowledge, structural inspection protocols, and financing awareness. As the lowcountry real estate landscape evolves through 2026, Summerville—spanning Dorchester, Berkeley, and Charleston counties—remains a prime destination for affordable housing. Buyers are increasingly turning to manufactured and mobile homes to bypass the soaring costs of traditional site-built construction. However, purchasing a pre-owned manufactured home involves distinct regulatory, logistical, and technical considerations that differ significantly from standard stick-built real estate transactions.
Understanding the Summerville, SC Housing Market for Pre-Owned Manufactured Homes
The regional housing market in Summerville offers diverse settings for pre-owned mobile homes, ranging from established land-lease communities to private acreage tracts. Buyers must first determine whether they are purchasing a home-only transaction (where the mobile home is situated in a rental park) or a real property transaction (where the home is permanently affixed to land owned by the seller).
Key Regional Micro-Markets Around Summerville
- Dorchester County Sector: Features numerous communities along the Highway 78 and Central Avenue corridors, offering close proximity to historic downtown Summerville and local employment hubs.
- Berkeley County Sector: Extends toward the Carnes Crossroads and Bonneau areas, providing larger rural or semi-rural lots suitable for older or double-wide homes.
- Charleston County Fringe: Areas touching North Charleston and outer Summerville where zoning laws regarding manufactured housing have specific historical compliance mandates.
Selecting the right location directly impacts your monthly expenses, property tax classifications, and long-term appreciation potential. Land-lease arrangements require lot rent payments that typically cover community amenities, water, and trash, whereas owning the underlying land provides total autonomy over property use.
Technical Specifications and Structural Inspection Protocols
Evaluating a used mobile home demands rigorous physical scrutiny. Unlike traditional homes built on site, manufactured homes are constructed to Department of Housing and Urban Development (HUD) code standards established in June 1976. Homes built prior to this date are classified as mobile homes and face severe financing restrictions.
Essential Inspection Checklist for Pre-Owned Homes
- HUD Certification Label and Data Plate: Locate the red metal certification label on the exterior tail-end of each section and the indoor data plate (usually located on a kitchen cabinet or utility closet wall) to verify build year, wind zone compliance, and original manufacturer specifications.
- Underbelly and Crawlspace Integrity: Inspect the moisture barrier, insulation condition, and framing beneath the home. Look for signs of sagging, rodent intrusion, or water damage from plumbing leaks.
- Chassis and Pier Foundation: Verify that the steel I-beam frame is free of excessive rust and that the piers, anchors, and tie-downs meet South Carolina wind zone requirements for Hurricane Zone II compliance.
- Roofing and HVAC Systems: Assess the lifespan of shingle or metal roofs. Check for pooling water on flat sections and test the heating, ventilation, and air conditioning compressor functionality.
Expert Inspector Tip: Always hire a licensed home inspector who holds specific certification or extensive experience with HUD-code manufactured housing. Standard home inspectors may overlook structural anchoring anomalies unique to double-wide and single-wide setups.
Financial Realities: Financing, Insurance, and Titling in South Carolina
Securing funds for a used mobile home depends entirely on whether the home is classified as personal property (chattel) or real estate. In South Carolina, a mobile home is titled through the Department of Motor Vehicles (DMV) unless it has been permanently converted to real property by filing an affidavit of affixture with the county register of deeds.
| Financing Type | Property Status | Typical Interest Rates | Down Payment Requirements |
|---|---|---|---|
| Chattel Loan | Home-only in a park | Higher (varies by credit) | 10% to 20% |
| FHA Title I / Conventional | Home-only or land-home | Competitive market rates | 3.5% to 5% |
| FHA / VA / USDA | Home + Land (Real Property) | Standard mortgage rates | 0% (VA/USDA) to 3.5% (FHA) |
Insurance policies for pre-owned manufactured homes also require specialized carriers. Because older materials can present higher replacement costs, securing HO-7 (modified coverage for mobile homes) or specialized manufactured home insurance requires clear documentation of upgrades, such as a recent roof replacement or updated electrical panels.
Step-by-Step Acquisition Workflow for Buyers
Executing a smooth purchase requires following a structured timeline from initial search to final key handover.
- Step 1: Budget and Pre-Approval: Determine your total purchasing power, factoring in lot rent or property taxes, insurance premiums, and potential moving or setup costs if relocating the unit.
- Step 2: Neighborhood and Park Vetting: If placing the home in a community, review all park rules, application fees, background check requirements, and monthly fee escalation histories.
- Step 3: Comprehensive On-Site Inspection: Walk through the home with a qualified inspector to generate a detailed repair estimate for any deferred maintenance items.
- Step 4: Title and Lien Search: Ensure the current owner holds a clear title free of DMV liens, county tax encumbrances, or unpaid park fees.
- Step 5: Closing and Conversion: Execute the bill of sale, transfer the title at the South Carolina DMV, or record the deed and affixture paperwork if purchasing the land simultaneously.
Pros and Cons of Buying a Pre-Owned Mobile Home
Evaluating the strategic advantages against potential drawbacks ensures an informed investment decision.
Advantages
- Affordability: Significantly lower cost per square foot compared to stick-built homes in Dorchester and Berkeley counties.
- Flexibility: Option to place the home on private family land or within established community neighborhoods.
- Modern Amenities: Many pre-owned models built after the 2000s feature drywall interiors, open-concept floor plans, and modern kitchen appliances.
Disadvantages
- Depreciation Risks: Unlike traditional real estate, older mobile homes acting solely as personal property may depreciate over time rather than appreciate.
- Park Rent Volatility: Rent increases in leased-land communities can impact your ongoing operational budget.
- Stricter Lending Criteria: Lenders often impose age restrictions on the home (e.g., refusing to finance homes older than 15-20 years).
Frequently Asked Questions
Can I move an older used mobile home to a vacant lot in Summerville?
Local municipal and county zoning laws impose strict age, size, and foundation requirements on relocating older mobile homes. You must verify local setback rules and zoning overlays with Dorchester or Berkeley County planning departments before purchasing a transportable unit.
Are pre-owned mobile homes in South Carolina subject to property taxes?
Yes, but the tax calculation depends on classification. If classified as personal property, they are taxed via the county auditor using vehicle-style assessment rates; if converted to real property alongside land, they are taxed as traditional real estate.
What is the minimum build year most lenders will finance?
Most conventional and government-backed lenders prefer manufactured homes built after June 15, 1976 (post-HUD code), with many chattel lenders capping home age at 15 to 20 years old for loan approval.
How do I verify if a used mobile home has a clear title in South Carolina?
You must check the serial numbers or HUD label numbers against the South Carolina Department of Motor Vehicles database to ensure the title matches the seller of record and carries no active liens.
What should I look for regarding flood zones in the Summerville area?
Certain low-lying parts of Summerville near swamp basins and tidal creeks fall into Special Flood Hazard Areas. Always check the FEMA flood map for the specific parcel or community address to determine if mandatory flood insurance will be required.
Securing Your Lowcountry Manufactured Home Investment
Navigating the pre-owned mobile home market in Summerville, SC requires careful attention to regulatory compliance, structural soundness, and financial structuring. By partnering with local title professionals, experienced manufactured home inspectors, and knowledgeable real estate specialists, you can secure a comfortable, cost-effective home tailored to your lifestyle. Begin your due diligence today by verifying park guidelines, inspecting structural chassis components, and securing pre-approval from a lender experienced in South Carolina manufactured housing transactions.