Lowe's credit products provide various financing solutions tailored for both everyday DIY homeowners and large-scale commercial contractors. Managing these accounts effectively involves understanding application criteria, interest rates, promotional financing windows, and digital account management tools to maximize savings on home improvement projects.
Understanding Lowe's Credit Portfolio
Lowe's offers a diversified portfolio of financial products issued in partnership with Synchrony Bank. These products are engineered to cater to distinct consumer profiles, separating residential retail buyers from professional contractors and business entities. Recognizing the structural differences between these options is the first step toward selecting the right financial tool for a project.
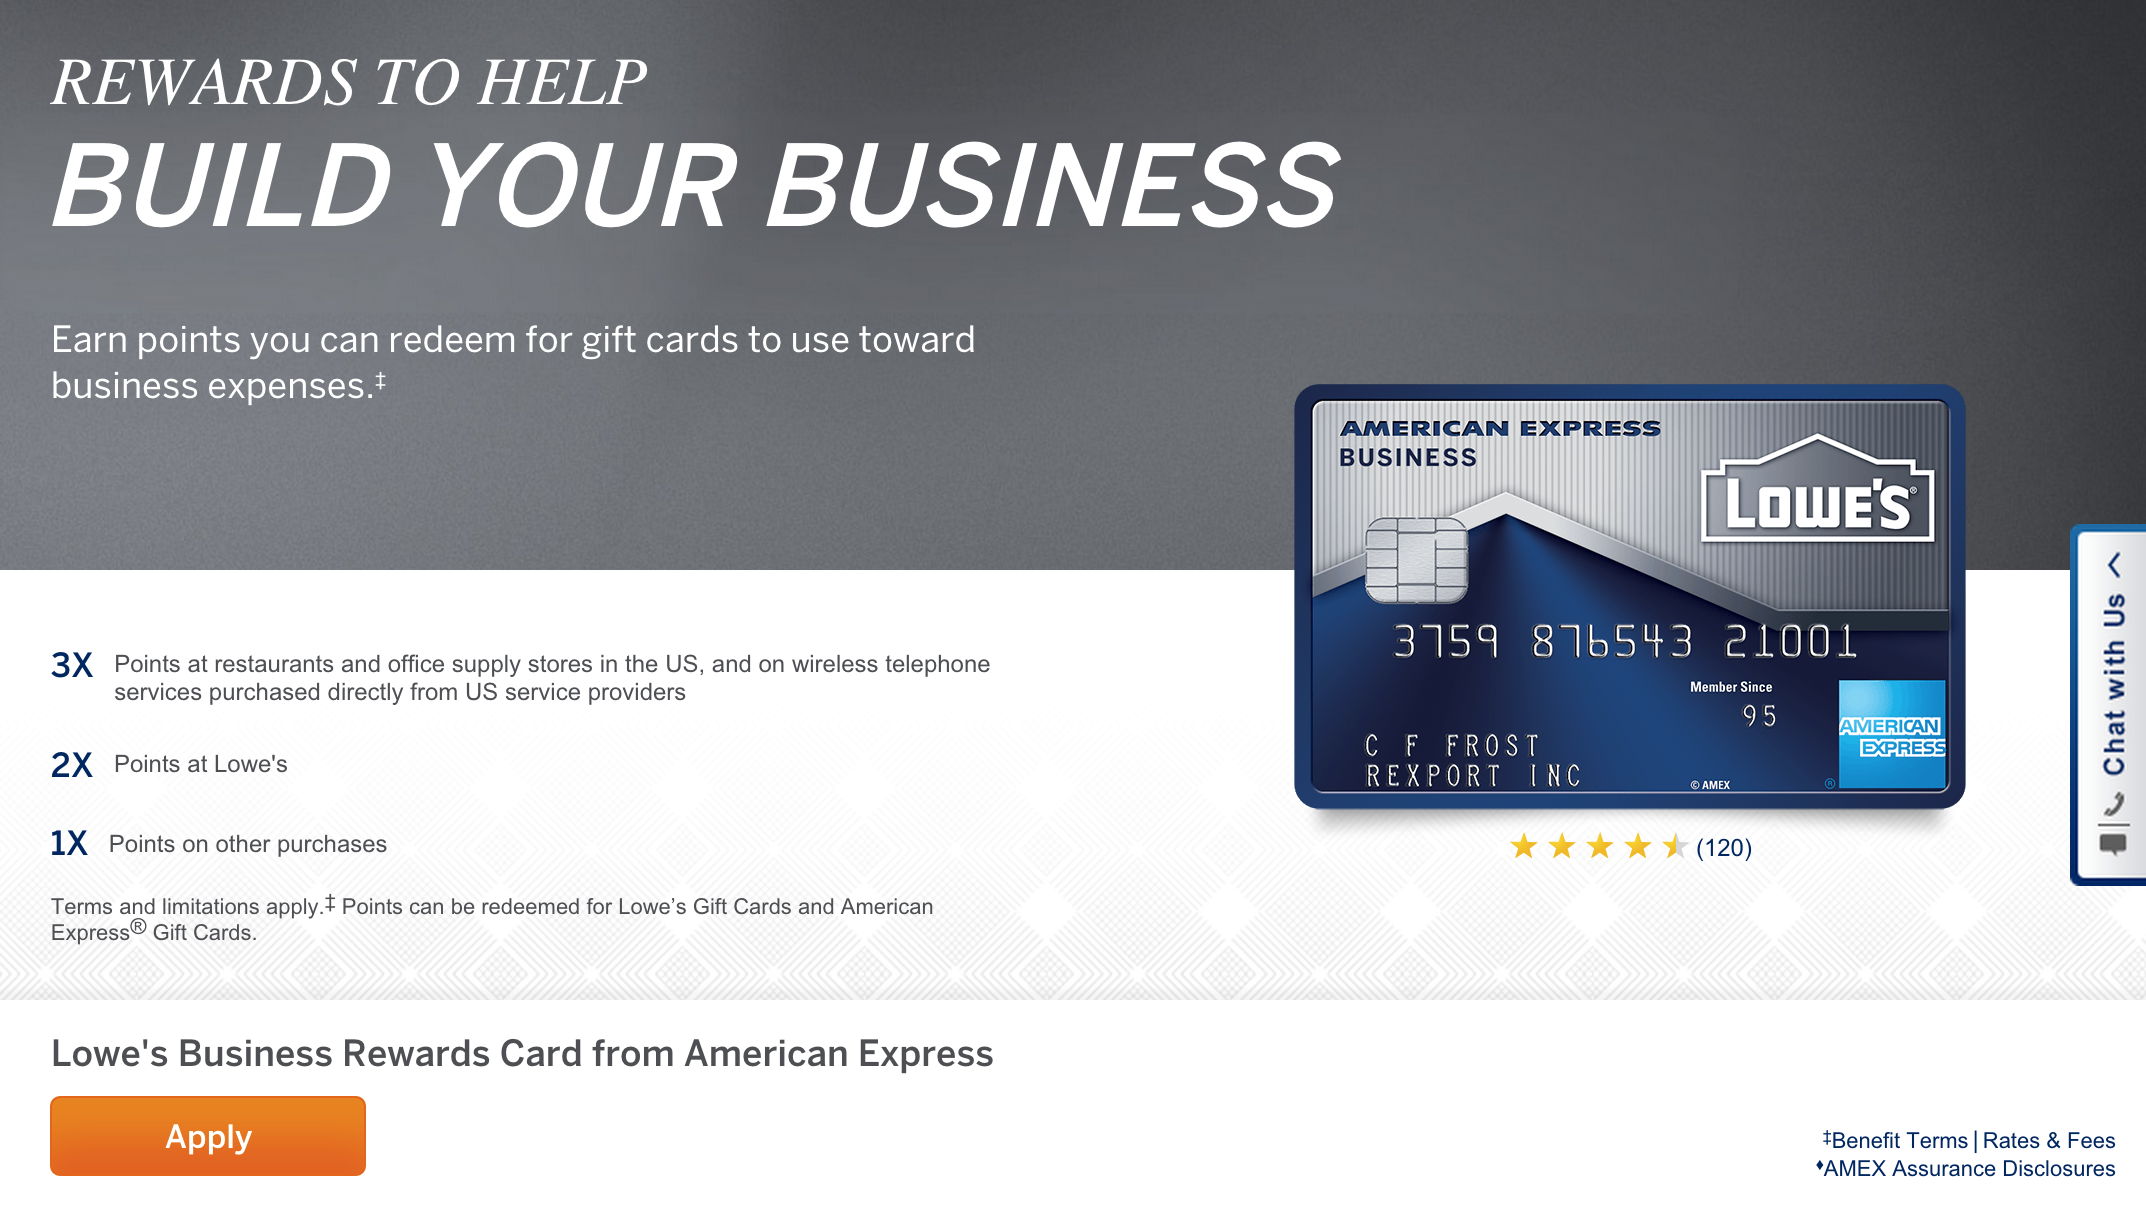
The primary consumer offering is the Lowe's Advantage Credit Card, which is designed for retail shoppers tackling home renovation, landscaping, or interior design projects. For commercial operations, builders, and property managers, Lowe's provides specialized commercial accounts, including the Lowe's Business Credit Account and the Lowe's Accounts Receivable (LAR) Program. Each program carries distinct underwriting standards, rewards structures, and payment terms.
When evaluating these programs, applicants must consider whether they need revolving credit for ongoing project expenses or specialized commercial lines that accommodate higher credit limits and multi-user employee cards. Selecting the appropriate account prevents unnecessary credit inquiries and aligns payment capabilities with cash flow requirements.
The Lowe's Advantage Credit Card: Features and Everyday Savings
The Lowe's Advantage Credit Card is a consumer revolving credit card that provides a permanent discount structure alongside rotating promotional financing offers.
Everyday 5% Off Discount
The core value proposition of the Lowe's Advantage card is the 5% everyday discount on eligible purchases made at Lowe's stores or online at Lowes.com. This discount is applied directly at the register or checkout screen, reducing the pre-tax subtotal of qualifying merchandise.
It is vital to note that certain exclusions apply to this discount. It cannot typically be combined with other promotional discounts, price matches, specific clearance events, contractor packs, or purchases of gift cards, extended protection plans, and specific manufacturer-restricted brands. Cardholders must review their receipt or online cart to verify that the 5% reduction has been correctly applied.
Promotional Financing Offers
In lieu of the 5% everyday discount, cardholders can frequently select special promotional financing terms on purchases meeting specific monetary thresholds. These options typically include:
- Special Financing (Deferred Interest): No interest if paid in full within 6, 12, or 24 months on qualifying purchases. If the balance is not paid in full by the promotional expiration date, interest is assessed from the original purchase date at the card's standard Annual Percentage Rate (APR).
- Low Monthly Payment Options: Reduced APR financing structures for larger installations, such as HVAC systems, roofing, or major kitchen renovations.
Commercial Financing Options for Contractors and Businesses
For professional contractors, handymen, and commercial property owners, consumer credit cards rarely provide sufficient credit limits or multi-user functionality. Lowe's addresses this sector through business-specific financial products.
Lowe's Business Credit Account
The Lowe's Business Credit Account operates as a revolving line of credit specifically for registered businesses. It features online account management, detailed itemized statements for expense tracking, and the ability to issue authorized buyer cards to trusted employees. This account also grants access to competitive volume pricing and specialized contractor support desks inside Lowe's retail locations.
Lowe's Accounts Receivable (LAR) Program
The Lowe's Accounts Receivable program is structured for larger commercial enterprises that require flexible payment terms. Unlike standard revolving cards, LAR accounts often operate on net-30 terms, allowing businesses to pay for materials after completing client projects and receiving payment. This program requires stricter credit underwriting and financial documentation compared to retail consumer cards.
Comparison of Lowe's Credit Programs
The following table outlines the structural differences, target audiences, and primary benefits of the primary Lowe's credit products.
| Credit Program | Target Audience | Primary Benefit | Standard Financing Structure |
|---|---|---|---|
| Lowe's Advantage Credit Card | Consumer DIY Shoppers | 5% everyday discount or deferred interest promos | Revolving consumer credit line |
| Lowe's Business Credit Account | Small Business / Contractors | Itemized tracking and multi-user cards | Revolving commercial credit line |
| Lowe's Accounts Receivable (LAR) | Large Contractors / Commercial | Extended payment terms (e.g., Net-30) | Commercial charge account |
Application Process, Eligibility, and Requirements
Applying for a Lowe's credit account requires meeting specific financial criteria and providing personal or business verification details.
Consumer Application Requirements
To apply for the Lowe's Advantage Credit Card, applicants must:
- Be at least 18 years of age (19 in select states).
- Provide a valid government-issued photo ID.
- Submit a Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN).
- Demonstrate a stable source of income and acceptable credit history.
Applications can be completed online via the official Lowe's website, inside any retail store at the customer service desk, or via mobile checkout devices. Synchrony Bank evaluates the applicant's credit score, debt-to-income ratio, and recent credit history to determine approval and credit limits.
Business Application Requirements
Commercial applicants must provide documentation verifying their business entity, such as:
- Federal Employer Identification Number (EIN).
- Business legal name, address, and telephone number.
- Owner or corporate officer personal guarantee details.
Digital Account Management and Online Portals
Once a Lowe's credit account is established, cardholders can manage their finances through dedicated online portals. Synchrony Bank administers the consumer Lowe's Advantage card portal, while commercial accounts utilize specialized business management platforms.
Key Digital Features
- Online Bill Pay: Schedule one-time payments or set up auto-pay to avoid missed payment deadlines and late fees.
- Paperless Statements: Access up to 24 months of historical statements for tax preparation and project budgeting.
- Alerts and Notifications: Configure text or email reminders for payment due dates and balance thresholds.
- Authorized User Management: Commercial account holders can add, modify, or deactivate employee purchasing cards in real time.
Financial Risks, Interest Rates, and Deferred Interest Traps
While Lowe's credit products provide valuable purchasing power and discounts, cardholders must navigate potential financial pitfalls, particularly regarding deferred interest promotions.
Understanding Deferred Interest
When utilizing a "No Interest if Paid in Full within X Months" promotion, the cardholder must ensure the entire promotional balance is cleared before the promotional period expires. Under deferred interest terms, if even a small fraction of the original balance remains unpaid on the final day of the promotional window, all accumulated interest from the original purchase date is retroactively applied to the account. This can result in substantial finance charges.
Standard APR and Fees
For balances not covered by promotional financing, standard variable APRs apply. These rates fluctuate based on the Prime Rate. Cardholders should review the Schumer box disclosures provided during account opening to understand exact penalty fees, late payment charges, and returned payment penalties. Maintaining a low credit utilization ratio and paying balances in full each month prevents unnecessary interest expenses.
Frequently Asked Questions
Can I use the Lowe's 5% everyday discount on clearance items?
The 5% everyday discount generally applies to eligible everyday and sale-priced merchandise. However, it typically excludes specific clearance markdowns, price-matched items, and items subject to manufacturer pricing restrictions. Checking the specific terms on your receipt or online cart clarifies how the discount applies to marked-down inventory.
What happens if I do not pay off a deferred interest promotional balance in time?
If a deferred interest balance is not paid in full by the expiration date, interest is calculated retroactively from the purchase date at the card's standard variable APR. This means you will owe interest for the entire duration of the promotional period, significantly increasing your total cost.
How do I check the status of a Lowe's credit application?
If an online application is not instantly approved, it may enter a pending review status. Applicants can contact Synchrony Bank customer service directly or check application status lines using the reference number provided at the time of submission.
Can authorized users make changes to a Lowe's Business Credit Account?
Authorized users can make purchases using their assigned cards, but account administration rights—such as changing billing addresses, requesting credit limit increases, or closing the account—are restricted to the primary account holder or designated corporate officers.
Is the Lowe's Advantage card accepted for online purchases at Lowes.com?
Yes, the Lowe's Advantage Credit Card can be saved to your Lowes.com profile and used for online checkouts, scheduled deliveries, and in-store pickup orders. The 5% everyday discount or applicable promotional financing options remain available for online transactions.
Conclusion and Next Actions
Choosing the right Lowe's credit product depends on whether you are managing personal home improvement projects or commercial contracting operations. To maximize your financial benefits, evaluate your project timeline, calculate whether the 5% everyday discount or deferred interest financing provides better savings, and always set up automated payment reminders to avoid interest charges and protect your credit score.