Accessing Royal Bank and online banking services allows you to manage accounts, pay bills, transfer funds, and monitor investments through digital platforms. This guide details how to sign in, set up your profile, secure your credentials, and resolve common technical barriers when banking online.
Understanding Royal Bank and Online Banking Infrastructure
Digital banking platforms operated by major financial institutions, such as the Royal Bank of Canada (RBC), serve as the primary interface for everyday consumer and commercial finance. Online banking replaces traditional branch visits for routine tasks, providing round-the-clock access via web browsers and dedicated mobile applications. Understanding how this infrastructure functions helps account holders navigate features efficiently while mitigating common digital risks.
The architecture of a modern banking portal relies on multi-tiered authentication, encrypted data transmission, and real-time ledger synchronization. When a user submits login credentials, the system cross-references those details against secure databases using secure socket layer (SSL) or transport layer security (TLS) protocols. Once verified, the dashboard fetches current account balances, pending transactions, and authorized credit products instantly.
The Evolution of Digital Financial Services
Over the past two decades, banking portals have transitioned from simple balance-checking web pages to comprehensive financial ecosystems. Early online banking required desktop computers and dial-up or early broadband connections, limiting functionality to statement viewing and basic internal transfers.
Today, digital platforms incorporate features such as:
- Mobile check deposits using smartphone cameras.
- Real-time peer-to-peer money transfers.
- Automated savings tools and budgeting analytics.
- Instant credit score monitoring and pre-approved loan applications.
These advancements require users to maintain updated software on their personal devices to ensure compatibility with modern banking encryption standards.
Prerequisites and Account Registration Requirements
Before accessing online banking services, new clients must establish a valid banking relationship with the institution. Registration requires specific verification documents and personal identification data to comply with federal regulations, anti-money laundering (AML) laws, and know-your-customer (KYC) mandates.
Essential Information Needed for Enrollment
To enroll in online banking services, ensure you have the following information prepared:
- Active Account Identifier: A checking account, savings account, credit card, or client card number.
- Personal Identification: Social Insurance Number (SIN) or equivalent tax identification, date of birth, and legal name.
- Contact Details: A verified mobile phone number capable of receiving SMS text messages and an active email address.
- Temporary Authentication Codes: Verification codes provided during initial branch setup or telephone banking registration.
Step-by-Step Enrollment Process
The registration sequence establishes your unique username (often a client card number or custom user ID) and a secure password.
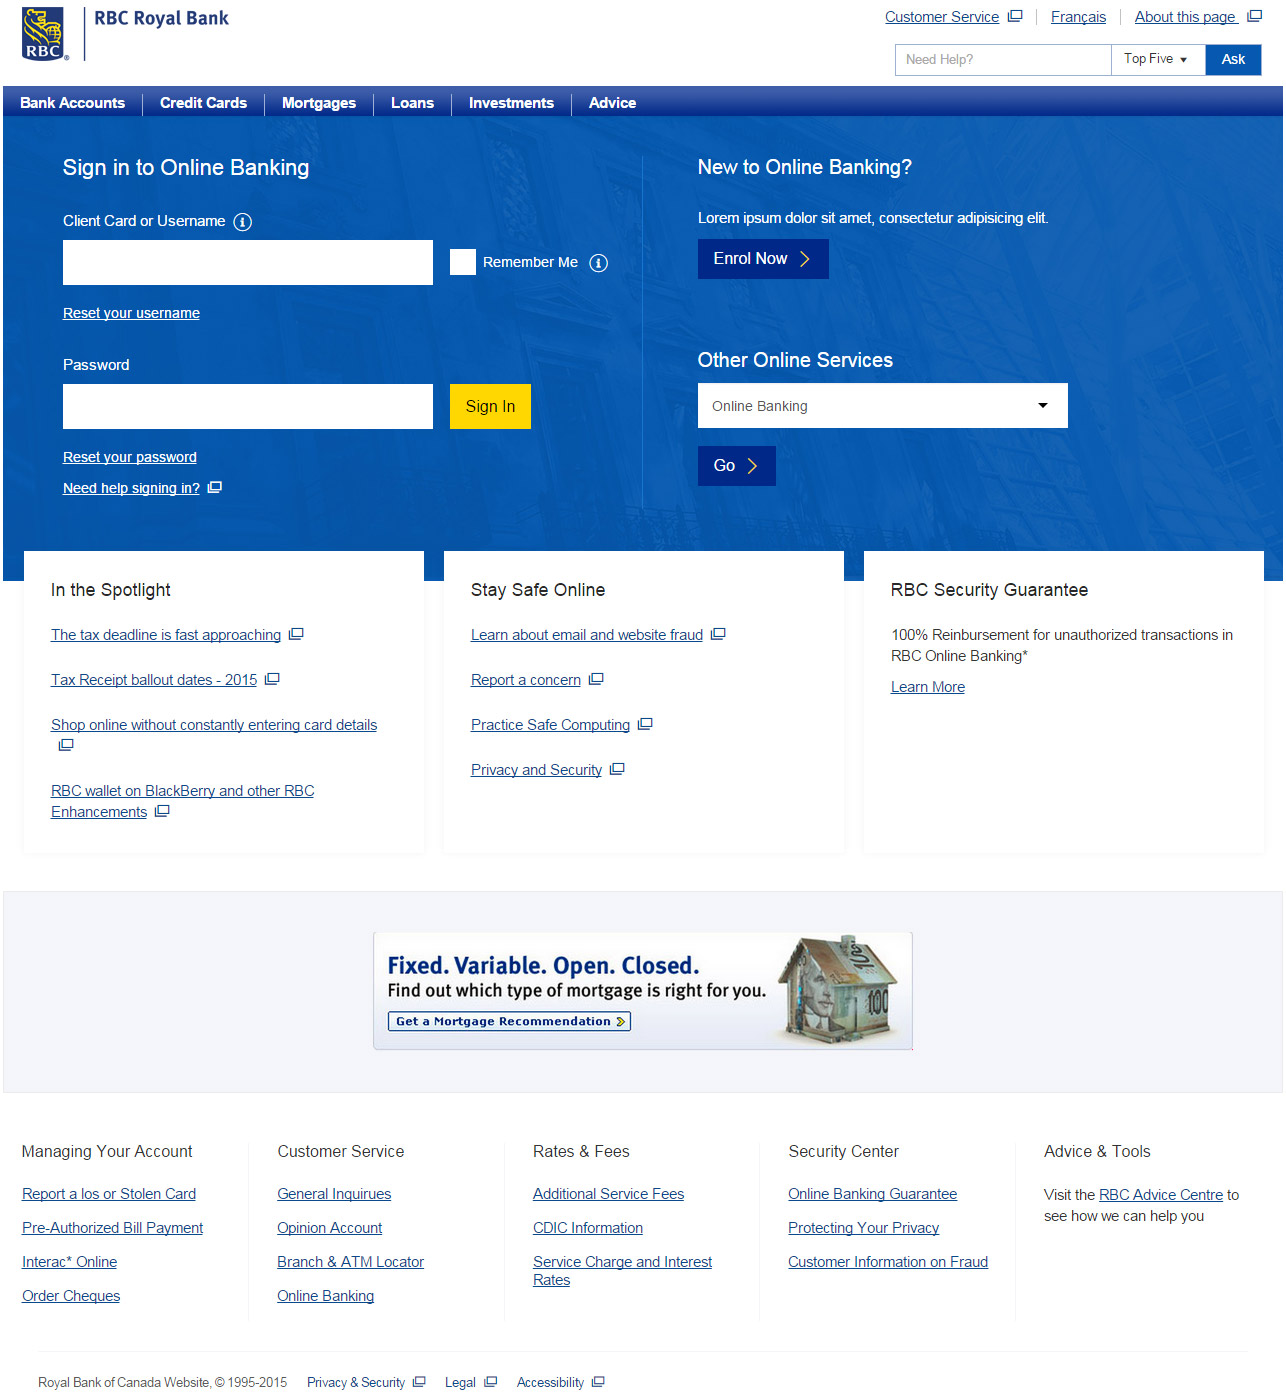
- Navigate to the Official Portal: Access the legitimate banking login page via a secure web browser or official mobile application downloaded from an authorized app store. Avoid clicking links in unsolicited emails or text messages.
- Select Enrollment Options: Click on the "Enroll" or "Create Login" button to begin the guided setup wizard.
- Input Account Credentials: Enter your client card number or eligible account number along with your personal details for verification.
- Verify Identity: Complete the two-factor authentication (2FA) challenge sent to your registered mobile number or email address.
- Create Security Credentials: Establish a strong, unique password and select security questions that cannot be easily guessed or researched via social media.
- Accept Terms and Conditions: Review the electronic service agreement, privacy policies, and fee schedules before finalizing registration.
Core Features and Functional Capabilities
Once logged into a Royal Bank online banking portal, users encounter a structured dashboard designed for rapid navigation. Understanding the layout and available features ensures you can execute transactions accurately without incurring unnecessary delays or fees.
Overview of Digital Banking Functions
| Feature Category | Primary Function | Typical Processing Time | Associated Considerations |
|---|---|---|---|
| Internal Transfers | Moving funds between your own checking, savings, and credit accounts. | Instant | Available 24/7; zero transaction fees. |
| Interac e-Transfer | Sending money to external recipients using an email address or mobile number. | Minutes to hours (depending on recipient bank) | Daily and weekly transfer limits apply. |
| Bill Payments | Settling utility, credit card, or municipal bills via payee directories. | 1 to 3 business days | Verify payee account numbers carefully. |
| Mobile Check Deposit | Depositing physical checks by capturing images of the front and back. | Funds held per standard institutional policy | Keep physical check for 14 days before destruction. |
| Statement Access | Viewing, downloading, and printing electronic tax and account statements. | Instant (PDF format) | Requires a PDF reader application. |
Managing Everyday Transactions
Executing day-to-day transactions requires attention to cut-off times and daily limits. For instance, bill payments initiated after standard business hours or on weekends often process on the next business day. Similarly, electronic money transfers adhere to strict threshold limits designed to protect account holders from unauthorized large-scale withdrawals. Users can request temporary or permanent adjustments to these limits through customer service channels if higher transaction volumes are required.
Security Practices and Risk Mitigation
Digital banking security is a shared responsibility between the financial institution and the account holder. While banks deploy advanced firewalls, encryption algorithms, and fraud detection monitoring, users must secure their endpoints—such as smartphones, tablets, and computers—against malicious actors.
Recognizing and Avoiding Common Digital Threats
Online banking users frequently encounter sophisticated cyber threats. Protecting personal assets requires vigilance against specific attack vectors:
- Phishing Scams: Fraudulent emails or text messages designed to mimic official bank communications, tricking users into revealing passwords, PINs, or verification codes. Banks will never ask for your password via email or text.
- Credential Stuffing: Automated attacks using lists of leaked username and password combinations from unrelated data breaches. Reusing passwords across multiple websites significantly increases vulnerability to this technique.
- Malware and Spyware: Malicious software installed on personal devices that records keystrokes or intercepts session tokens. Keeping operating systems and antivirus software updated helps prevent infections.
Best Practices for Account Protection
- Enable Multi-Factor Authentication (MFA): Always activate biometric login (fingerprint or facial recognition) or app-based verification codes where available.
- Use Secure Networks: Avoid accessing online banking portals over public, unsecured Wi-Fi networks in airports, cafes, or hotels unless using a trusted Virtual Private Network (VPN).
- Monitor Account Activity Regularly: Set up real-time text or email alerts for transactions exceeding specific dollar thresholds, international charges, or password changes.
- Log Out Completely: Always click the official "Sign Out" button and close your browser window when finished, particularly on shared or public computers.
Troubleshooting Common Online Banking Issues
Technical hurdles can occasionally disrupt access to online banking services. Knowing how to diagnose and resolve minor errors saves time and reduces frustration.
Login Failures and Password Resets
If you are locked out of your account due to consecutive incorrect password attempts, the system automatically suspends access to protect your funds.
- Resolution Steps: Select the "Forgot Password" or "Reset Password" link on the login page. You will need to verify your identity using your client card, personal information, and a secure verification code sent to your registered mobile device. If verification fails, contact telephone support for manual identity confirmation.
Browser Compatibility and Cache Errors
Outdated web browsers or corrupted cache files can cause pages to load incorrectly or prevent login buttons from responding.
- Resolution Steps: Clear your browser's cache and cookies, ensure your browser is updated to the latest stable version, or attempt logging in using an alternative supported browser (such as Chrome, Safari, Firefox, or Edge). Disable aggressive ad-blockers or script-blockers that may interfere with banking portal scripts.
App Crashes and Connectivity Errors
Mobile banking applications may experience freezing or connectivity failures during server updates or poor network signals.
- Resolution Steps: Toggle your device's airplane mode on and off to reset network connections. Check your device's app store for pending updates to the banking application. If problems persist, restart your mobile device entirely or switch from cellular data to a stable home Wi-Fi network.
Frequently Asked Questions
What should I do if I suspect unauthorized transactions on my account?
Contact the bank's fraud department immediately to report the unauthorized activity, freeze your debit or credit cards, and secure your online profile. Review your transaction history carefully to compile a list of disputed charges. Prompt reporting limits your liability under consumer protection regulations.
Can I access Royal Bank online banking while traveling internationally?
Yes, digital banking portals are accessible globally via internet connections. However, automated fraud detection systems may flag sudden foreign logins as suspicious. It is advisable to notify your bank of your travel dates and destinations through the mobile app or customer service before departure.
Are there any fees associated with using online banking services?
Basic online banking features—such as viewing statements, checking balances, and making internal transfers—are typically free. However, specific transactions like wire transfers, expedited bill payments, or exceeding monthly transaction limits on certain account tiers may incur service charges as outlined in your account fee schedule.
How do I update my phone number or email address for security codes?
You can update your contact information directly within the security settings of your online profile or mobile app. For security reasons, changing primary phone numbers or email addresses may require secondary verification via a temporary code sent to your existing contact method or a video confirmation with a customer service representative.
What is the difference between a personal client card number and an online username?
A client card number is a permanent physical identifier printed on your debit card. Many modern banking portals allow or require you to create a personalized, alphanumeric username for added security, eliminating the need to type your physical card number into login fields repeatedly.
Next Actions and Practical Recommendations
To maintain secure and efficient control over your finances, audit your online banking profile today. Verify that your registered mobile phone number and email address are current, enable transaction push notifications for immediate spending alerts, and ensure your mobile banking application is updated to the latest version available in your device's official app store.