A Health Reimbursement Arrangement (HRA) is an employer-funded, tax-advantaged employer health benefit plan that reimburses employees for out-of-pocket medical expenses and, in many cases, individual health insurance premiums. Unlike traditional group health insurance where the employer purchases a master policy, an HRA allows employers to set aside a specific pool of money for employees to use on qualified healthcare costs.
What Is an HRA and How Does It Function?
To understand how an HRA operates, it is helpful to look past common misconceptions. Many people search for "HRA insurance" as if it were a standalone health insurance policy they can purchase independently on an individual marketplace. In reality, an HRA is not insurance at all. Instead, it is an employer-sponsored account-based benefit designed to work alongside or in lieu of traditional group health coverage.
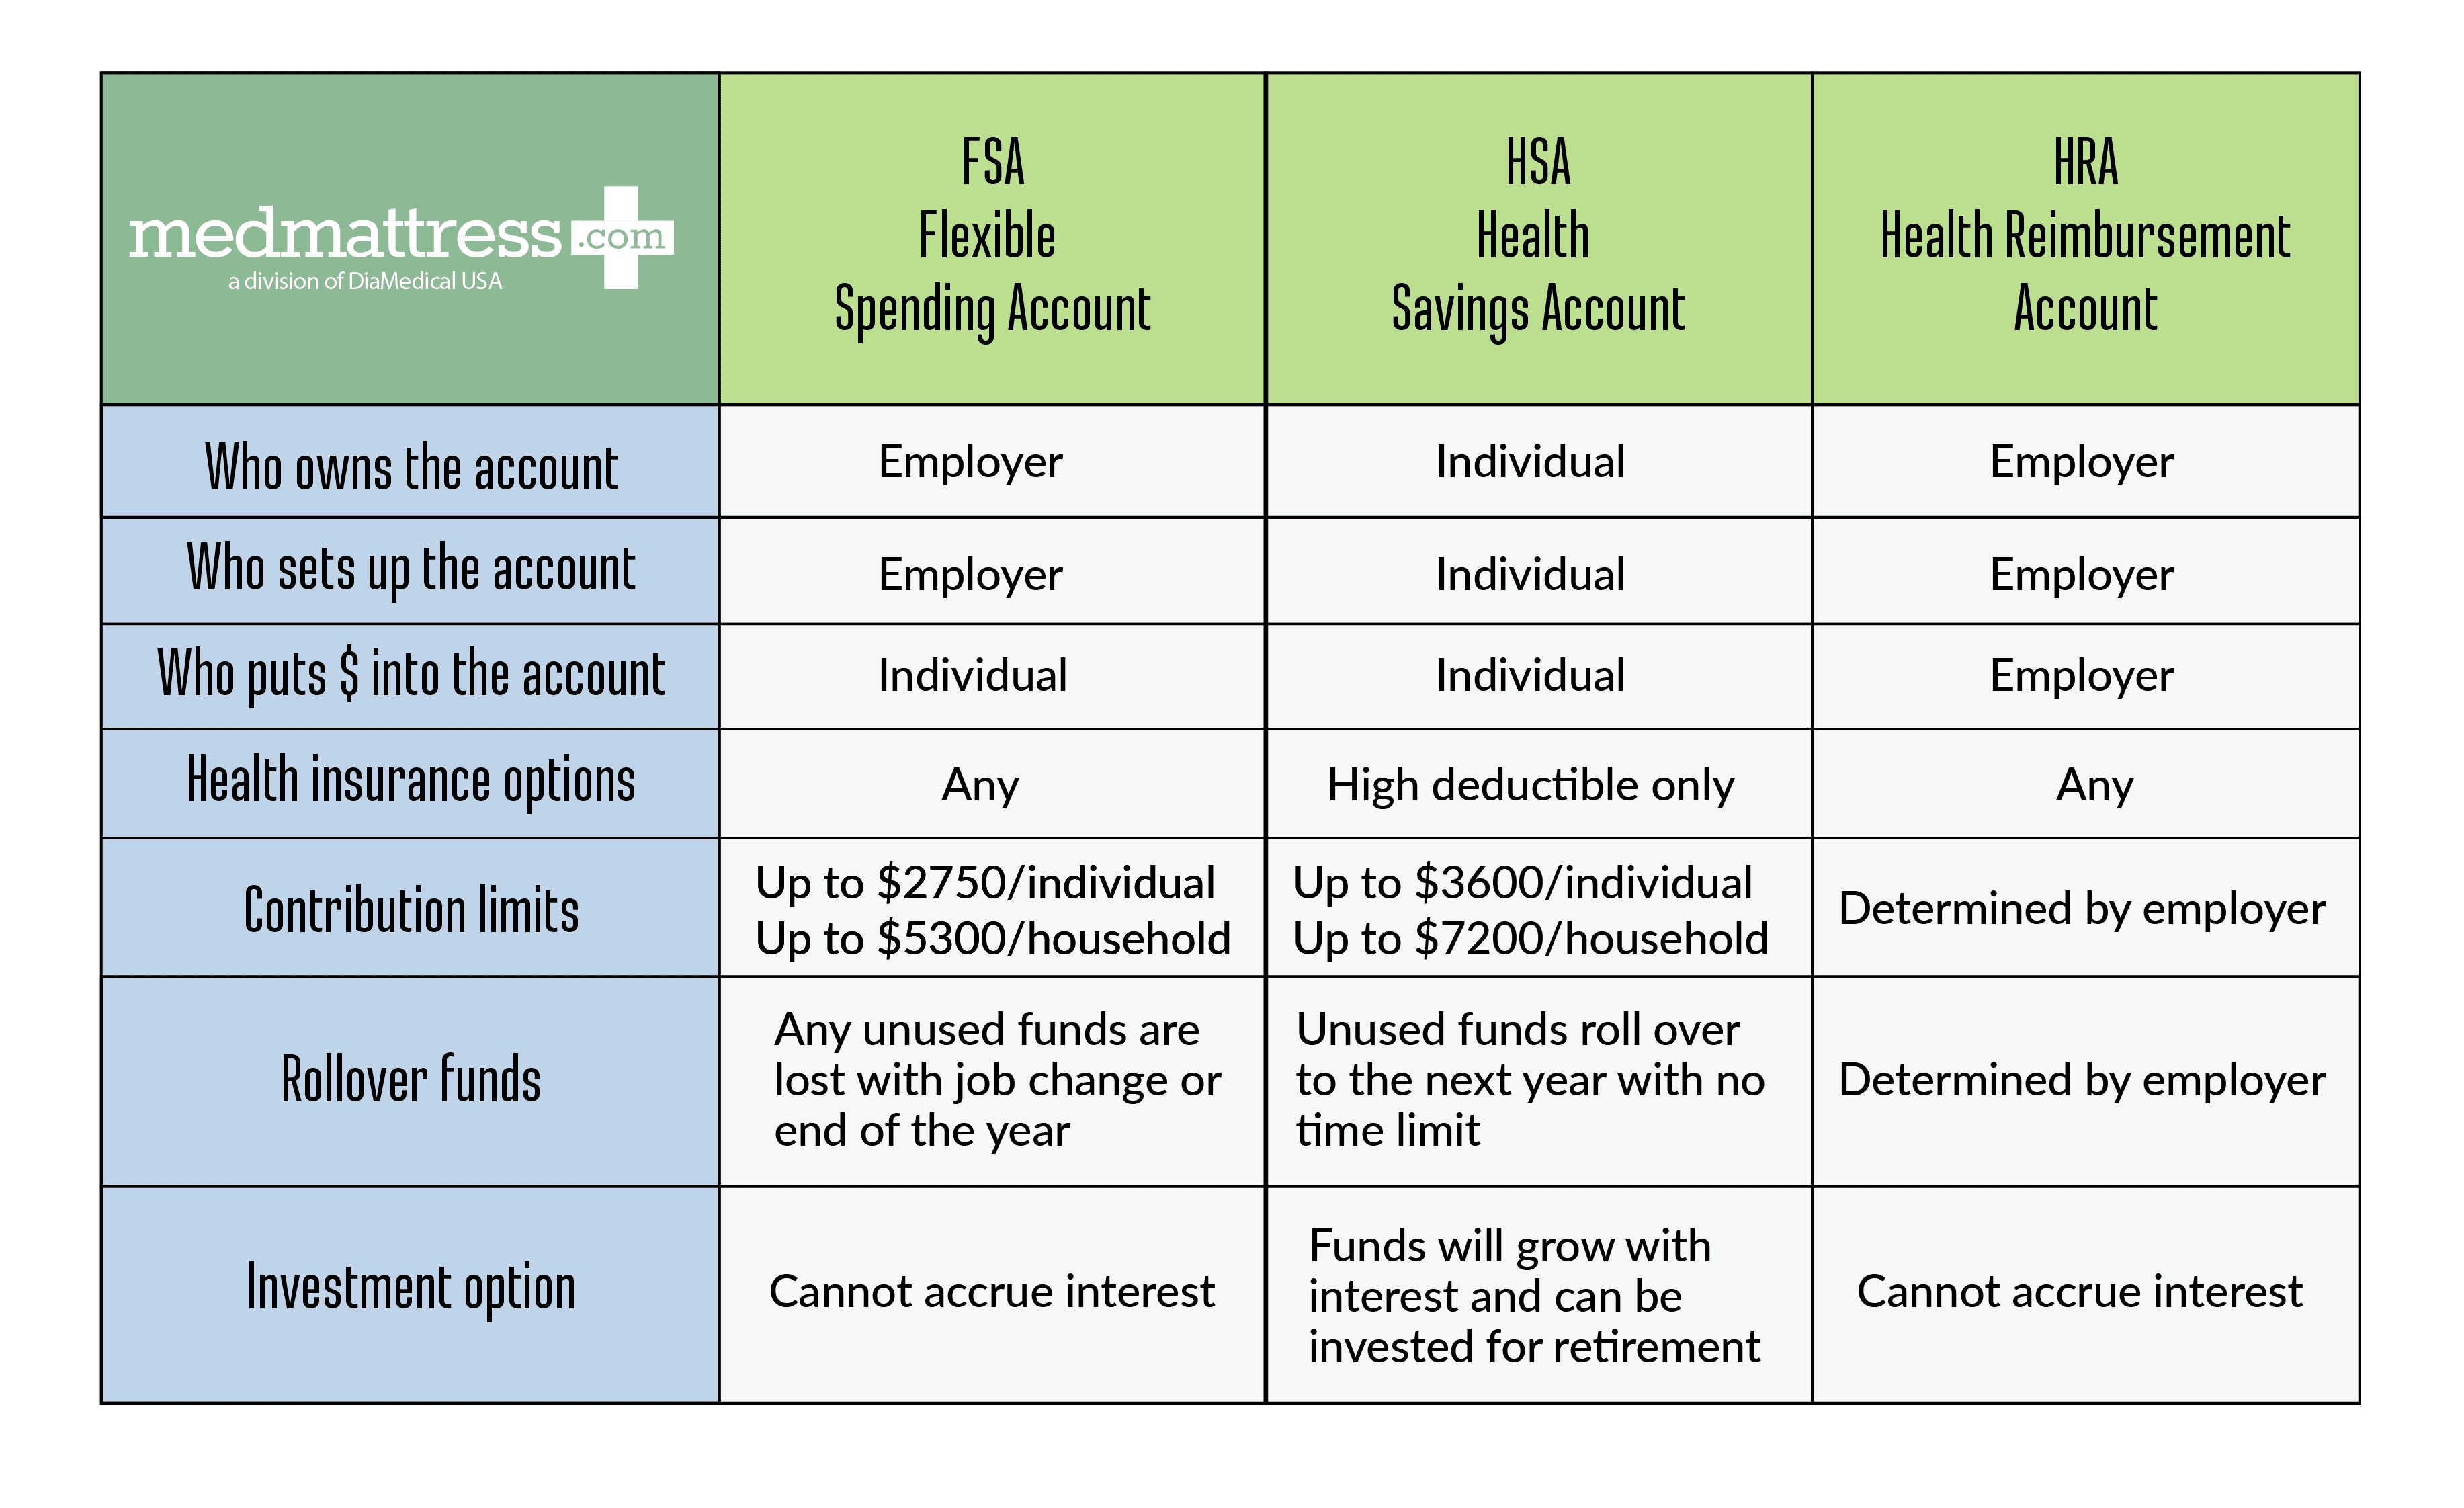
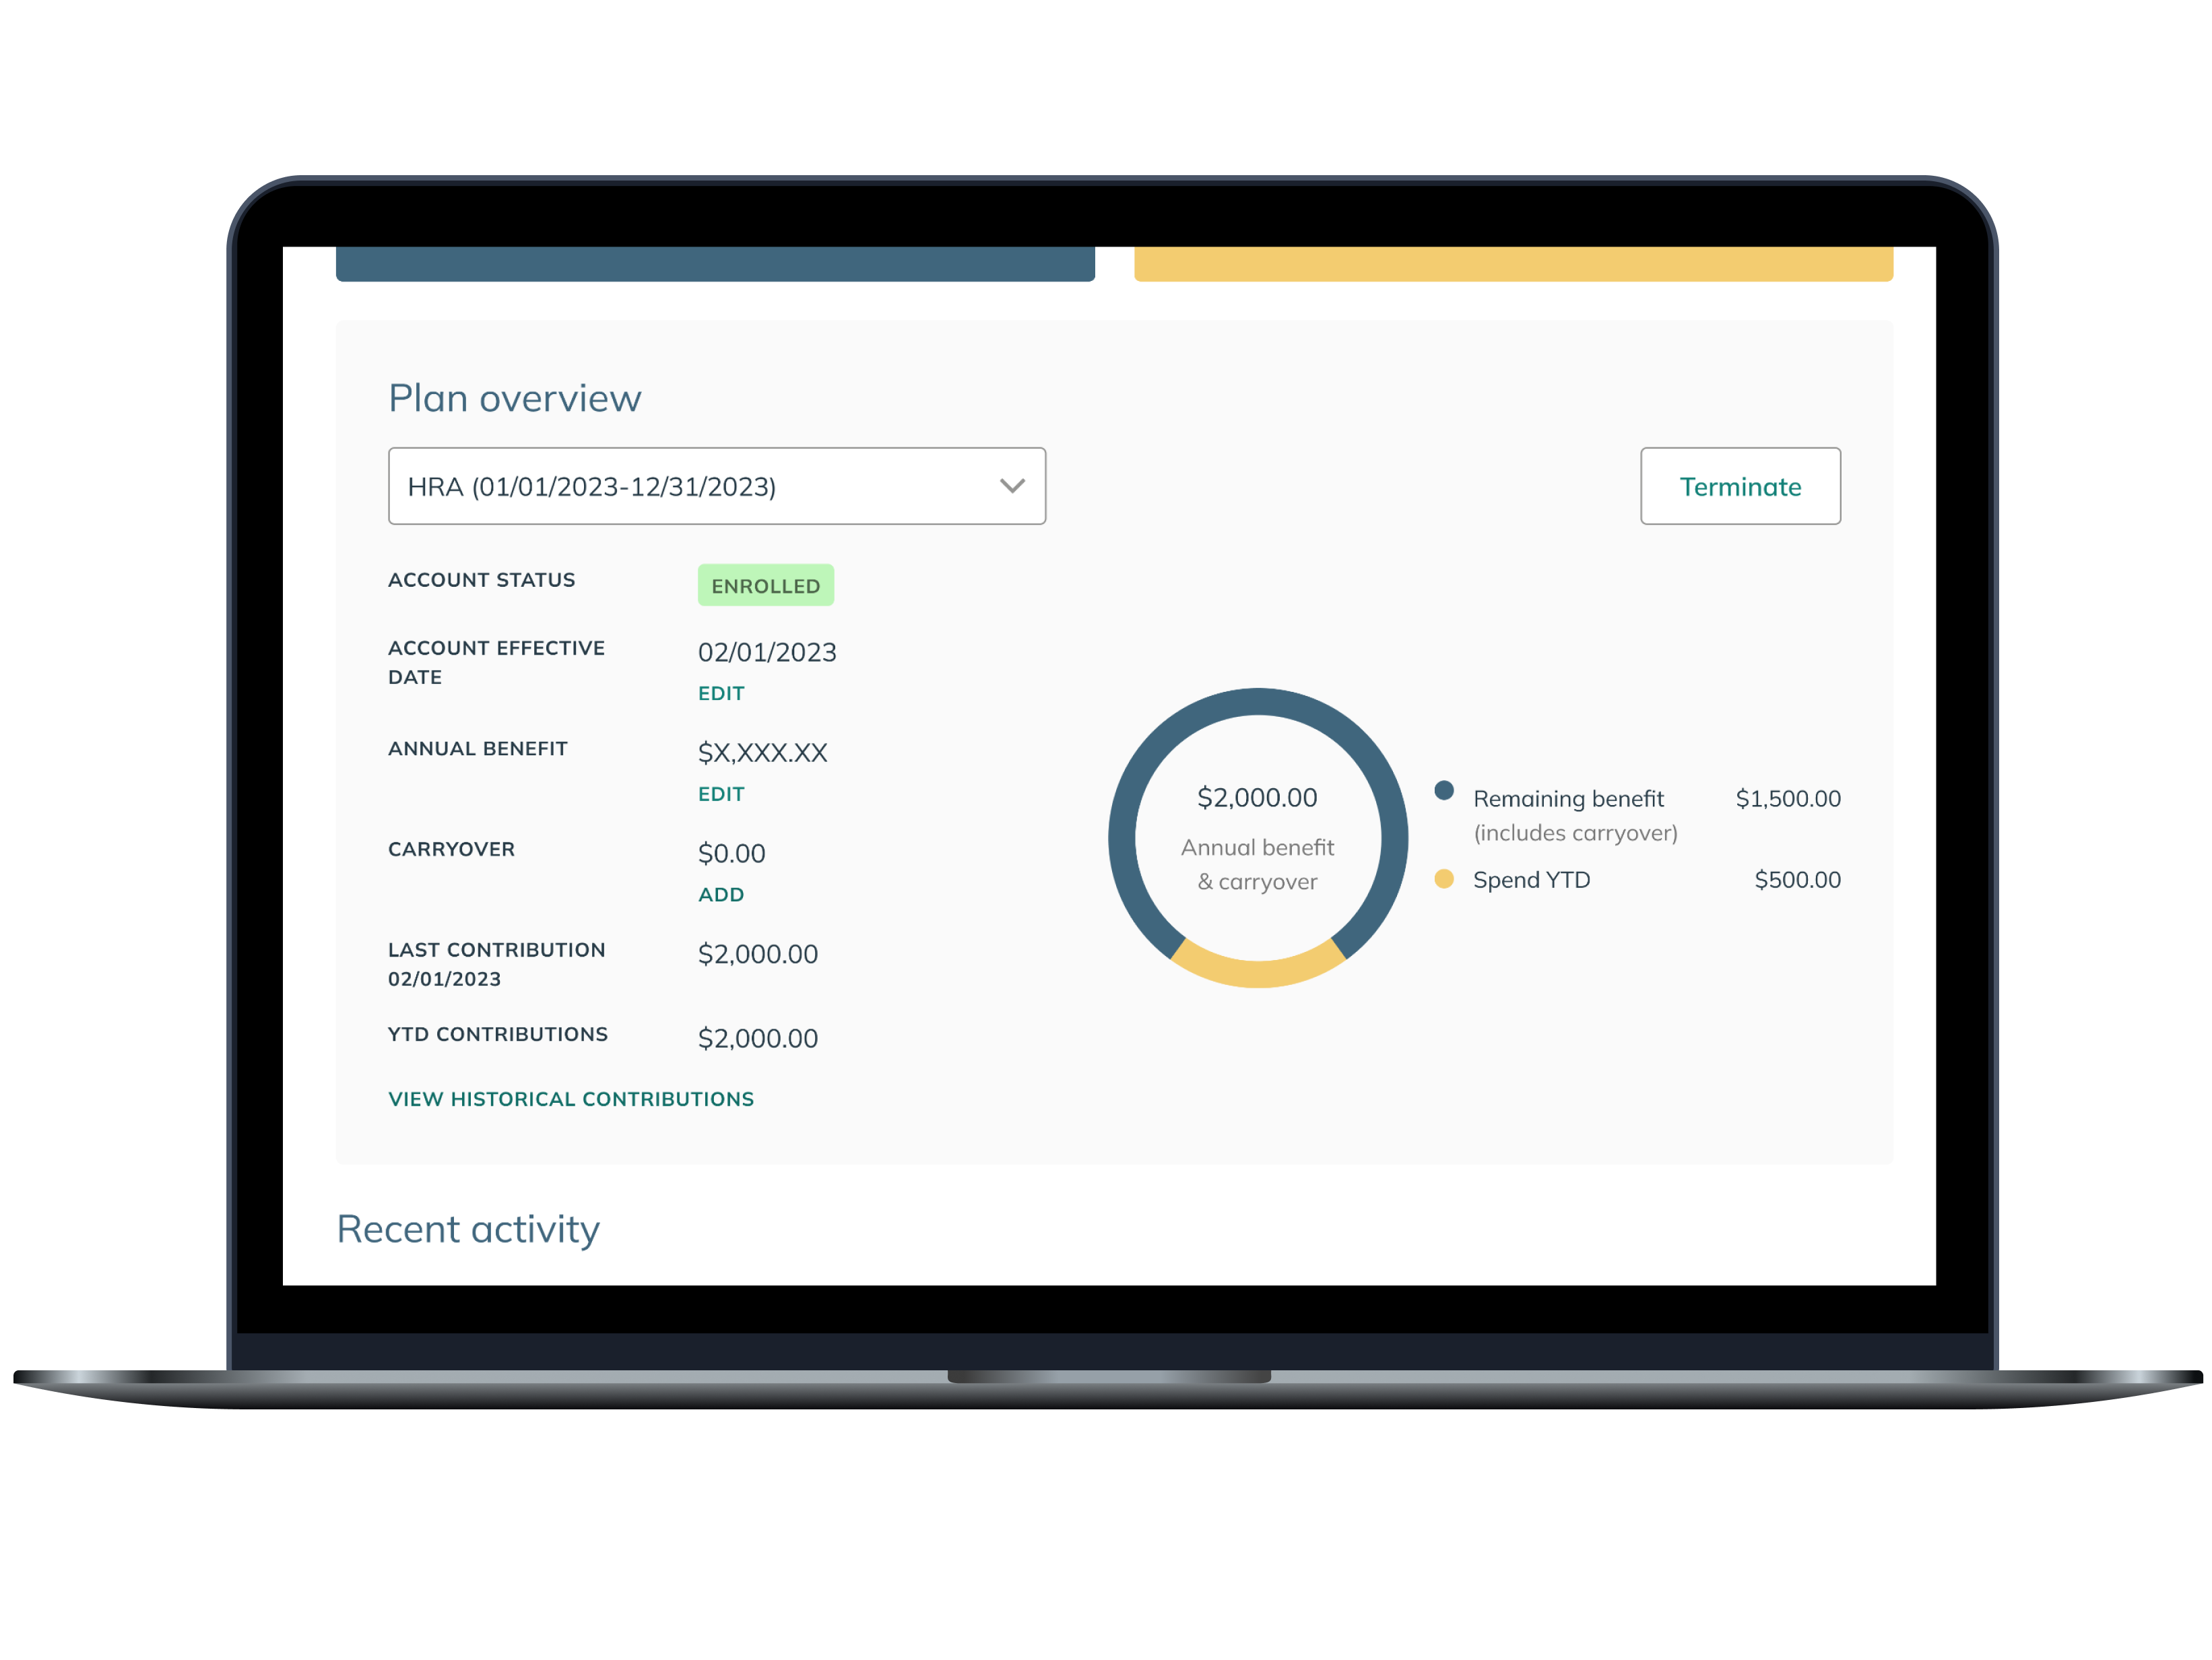
Under Internal Revenue Service (IRS) regulations, HRAs are fully funded by the employer. Employees cannot make pre-tax salary reduction contributions to an HRA, which separates it structurally from a Flexible Spending Account (FSA). The employer establishes the plan, determines the annual allocation amount, and sets the rules for which medical expenses qualify under IRS guidelines (typically matching Section 213(d) of the Internal Revenue Code). When an employee incurs a qualified medical expense, they pay for it out of pocket or use a linked reimbursement mechanism, submit proof of the expense to the employer or a third-party administrator (TPA), and receive a tax-free reimbursement check or direct deposit.
Because the funds belong to the employer until they are distributed to reimburse a verified expense, unused balances generally stay with the employer when an employee leaves the company, unless the employer has designed the plan to allow for specific carryover provisions. This dynamic makes HRA arrangements distinct from Health Savings Accounts (HSAs), which are individually owned and portable.
Core Types of Health Reimbursement Arrangements
Employers can implement several distinct types of HRAs, each governed by specific regulatory frameworks, contribution limits, and operational rules. Choosing the right structure depends on business size, workforce demographics, and strategic employee benefits goals.
- Individual Coverage HRA (ICHRA)
- Integrates with individual market or ACA policies
- Qualified Small Employer HRA (QSEHRA)
- Strictly for businesses with fewer than 50 full-time staff
- Group Coverage HRA (GCHRA)
- Pairs with a traditional group health plan
- Excepted Benefit HRA (EBHRA)
- Limited to dental, vision, or short-term limited duration
Individual Coverage HRA (ICHRA)
Introduced by federal regulatory updates in 2020, the Individual Coverage HRA allows employers of any size to reimburse employees tax-free for individual health insurance policies purchased through the Affordable Care Act (ACA) health insurance marketplace or off-exchange, as well as for Medicare coverage. ICHRA offers immense flexibility because employers can tailor allowance amounts based on employee classes—such as full-time, part-time, salaried, hourly, or geographic location—provided certain minimum class size rules are met.
Qualified Small Employer HRA (QSEHRA)
Designed specifically for small businesses with fewer than 50 full-time equivalent (FTE) employees that do not offer a traditional group health plan, the QSEHRA allows businesses to provide tax-free reimbursements for medical expenses and individual health insurance premiums. Unlike ICHRA, QSEHRAs feature strict statutory contribution limits set annually by the IRS and require the benefit to be provided on the same terms to all eligible employees.
Group Coverage HRA (Traditional HRA / GCHRA)
Often called a traditional HRA, the Group Coverage HRA is designed to be paired exclusively with an employer-sponsored group health plan, usually a high-deductible health plan (HDHP). It helps employees cover out-of-pocket costs that count toward their health plan's deductible, coinsurance, or copayments.
Excepted Benefit HRA (EBHRA)
An Excepted Benefit HRA allows employers that offer a traditional group health plan to provide additional tax-free funds specifically for "excepted benefits," such as dental and vision care, short-term limited-duration insurance (STLDI), or COBRA premiums. Employers can offer an EBHRA regardless of whether the employee enrolls in the primary group health plan, up to statutory annual contribution limits.
Comparing HRA Variations: Key Operational Differences
| Feature | ICHRA | QSEHRA | Traditional HRA (GCHRA) | Excepted Benefit HRA |
|---|---|---|---|---|
| Eligible Employer Size | Any size (All businesses) | Under 50 FTEs | Any size | Any size |
| Must Offer Group Plan? | No | Cannot offer group plan | Yes (Must pair with group plan) | Optional |
| Contribution Limits | No statutory limit | Capped annually by IRS | No statutory limit | Capped annually by IRS |
| Permits Premium Reimbursement | Yes (Individual market & Medicare) | Yes (Individual market) | Generally No | Limited (COBRA, dental/vision) |
| Employee Eligibility Classes | Allowed based on job criteria | Must be uniform for all | Allowed based on job criteria | Must be uniform for all |
Eligibility, Establishment, and Compliance Requirements
Setting up an HRA requires strict adherence to federal labor and tax laws, including the Employee Retirement Income Security Act (ERISA), the Internal Revenue Code, and ACA market reforms.
Employer and Plan Document Prerequisites
An HRA cannot be implemented informally. Employers must draft and execute a formal written plan document that outlines eligibility rules, eligible expenses, reimbursement schedules, and claim submission deadlines. For businesses with 100 or more participants, Form 5500 filings may be required under ERISA guidelines. Furthermore, employers must provide participants with a Summary Plan Description (SPD) detailing their rights and obligations under the arrangement.
Employee Eligibility and Substantiation Rules
To receive tax-free reimbursements under an ICHRA, an employee and any covered dependents must maintain qualifying health coverage—such as an individual market plan, Medicare Parts A and B, or Medicaid—for every month they receive the HRA benefit.
Under IRS rules, every reimbursement claim must be substantiated. Employees cannot simply receive a flat monthly stipend without proving an incurred medical expense or verifying active individual health insurance enrollment. Proof typically includes itemized receipts, medical bills, Explanation of Benefits (EOB) statements from insurers, or monthly premium invoices.
Financial Mechanics: Taxation, Funding, and Cost Control
The primary attraction of an HRA lies in its tax advantages for both employers and employees, coupled with predictable budgeting for organizational healthcare spending.
Tax Treatment for Employers and Employees
- Employer Benefits: Reimbursed funds are generally 100% tax-deductible as a business expense. Furthermore, employer contributions to an HRA are exempt from federal payroll taxes (FICA and FUTA), reducing overall labor costs compared to raw salary increases.
- Employee Benefits: All reimbursements received by employees for qualified medical expenses and eligible insurance premiums are entirely excluded from their gross income for federal, state, and local income tax purposes.
Budget Predictability and Cost Containment
Traditional group health insurance renewals often bring unpredictable, double-digit premium hikes driven by group claims history. HRAs decouple employer contributions from group risk pools. By establishing a fixed monthly allowance—such as a specific dollar amount for single employees versus family coverage—employers retain total control over their healthcare expenditure budget year over year.
Advantages and Disadvantages of HRA Utilization
Evaluating whether an HRA is the right mechanism requires weighing operational benefits against administrative complexities.
Major Benefits
- Personalized Coverage: With ICHRA and QSEHRA, employees choose the exact individual health insurance plan that fits their personal doctors, prescription needs, and financial risk tolerance.
- Cost Control: Fixed employer contributions prevent runaway premium spikes typical of traditional fully insured group plans.
- Tax Efficiency: Both parties enjoy substantial tax savings through pre-tax reimbursement flows.
- Scalability: Businesses of any size can provide structured health benefits without the prohibitive costs of traditional group underwriting.
Operational Limitations and Drawbacks
- Administrative Burden: Processing reimbursement claims, verifying monthly minimum essential coverage (MEC), and managing compliance documentation require dedicated administrative software or a specialized TPA.
- Individual Market Friction: In certain geographic regions, individual health insurance market options may be limited, expensive, or lack robust provider networks.
- Advance Funding vs. Reimbursement Confusion: Employees must have the upfront liquidity to pay for medical services or monthly premiums before receiving their tax-free reimbursement check.
Frequently Asked Questions About HRA Insurance
Can I buy health insurance directly with HRA funds?
Yes, if your employer offers an Individual Coverage HRA (ICHRA) or a Qualified Small Employer HRA (QSEHRA). These arrangements specifically permit employers to reimburse you tax-free for individual health insurance premiums purchased on or off the public ACA marketplace, as well as Medicare. Traditional group HRAs generally cannot be used to pay for individual market premiums.
What happens to unused HRA money when I leave my job?
Because HRAs are employer-owned benefit accounts, unused funds generally remain with the employer when your employment terminates. Unlike a Health Savings Account (HSA), HRA balances are not portable. However, depending on the employer's plan document and applicable continuation rules like COBRA, you may be able to access remaining funds for expenses incurred prior to your termination date.
Are HRA reimbursements considered taxable income?
No. Under Section 105 and Section 106 of the Internal Revenue Code, all reimbursements disbursed through a compliant HRA for qualified medical expenses or eligible health insurance premiums are 100% tax-free for the employee and tax-deductible for the employer.
Can an HRA be combined with a Health Savings Account (HSA)?
Generally, combining a traditional HRA with an HSA creates eligibility conflicts unless the HRA is specifically structured as a "limited-purpose HRA" (restricted to dental, vision, or preventive care) or a "post-deductible HRA" that only begins paying out after the IRS minimum high-deductible health plan deductible has been met. ICHRA rules also have strict alignment requirements regarding HSA compatibility.
Who handles the processing of HRA claims and verification?
While small employers sometimes manage simple QSEHRAs internally, most organizations partner with third-party administrators (TPAs) or specialized HRA software platforms. These providers automate the verification of individual insurance coverage, review medical receipts against IRS rules, and handle direct deposits securely while ensuring regulatory compliance.
Practical Next Steps for Employers and Employees
If you are an employer looking to implement an HRA, begin by assessing your workforce demographics, reviewing local individual insurance market stability, and consulting with a qualified benefit advisor or tax professional to draft a compliant plan document. If you are an employee exploring your options, review your employer’s Summary Plan Description to identify which specific HRA class you fall under, verify your monthly allowance limits, and ensure you maintain qualifying individual coverage to unlock tax-free reimbursements.