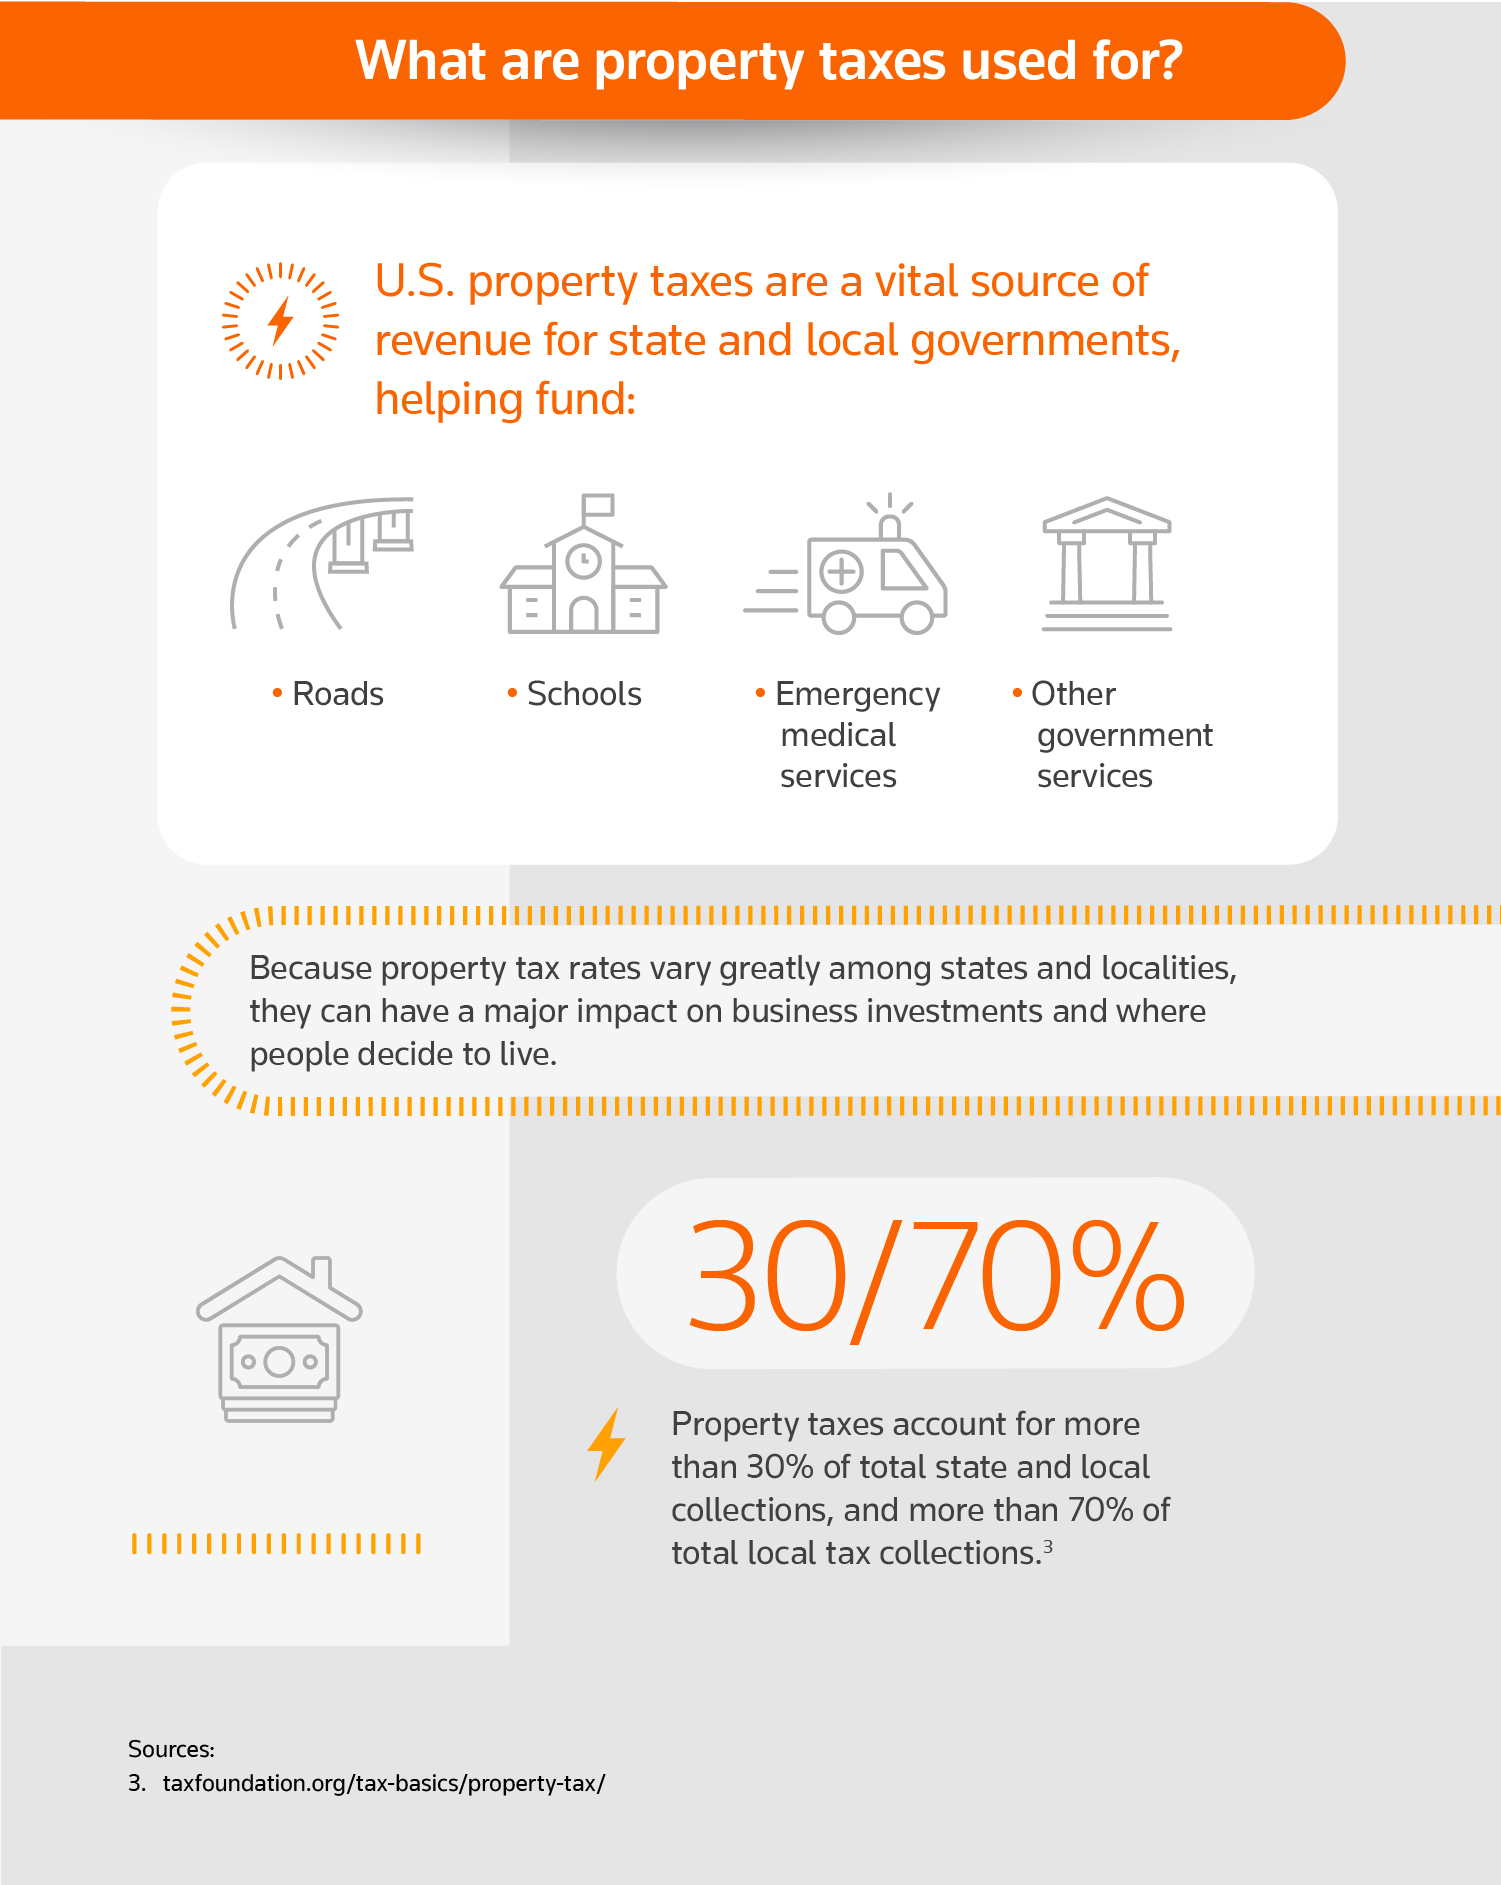
Property tax is a recurring ad valorem tax levied by local government jurisdictions on real estate owners. The tax amount is determined by multiplying the property's assessed value by the local millage rate. These funds are primarily used to finance essential community services, including public schools, infrastructure, law enforcement, and emergency response systems.
Property tax, often referred to in administrative contexts as "tax property" valuation, represents one of the most significant ongoing costs of homeownership and real estate investment. Unlike income or sales taxes, which are transaction-based, property taxes are wealth-based levies on the value of the physical assets you own. As we navigate the fiscal landscape of 2026, understanding the nuances of how these taxes are assessed, the legal mechanisms for exemptions, and the procedures for challenging an unfair valuation is critical for maintaining financial health.
The Foundational Mechanics of Property Taxation
To manage property tax obligations effectively, one must first understand the distinction between the entities involved in the process. Generally, three distinct bodies govern your tax bill: the legislative body that sets the budget (such as a City Council or School Board), the Tax Assessor’s office which determines the value of the property, and the Tax Collector’s office which processes the payments.
The Ad Valorem Principle
Property tax is an ad valorem tax, a Latin phrase meaning "according to value." This means the tax is not a flat fee but is proportional to the estimated worth of the real estate. If your property value increases due to market trends or significant renovations, your tax liability will likely increase accordingly, provided the local tax rate remains stable.
Jurisdiction and Funding
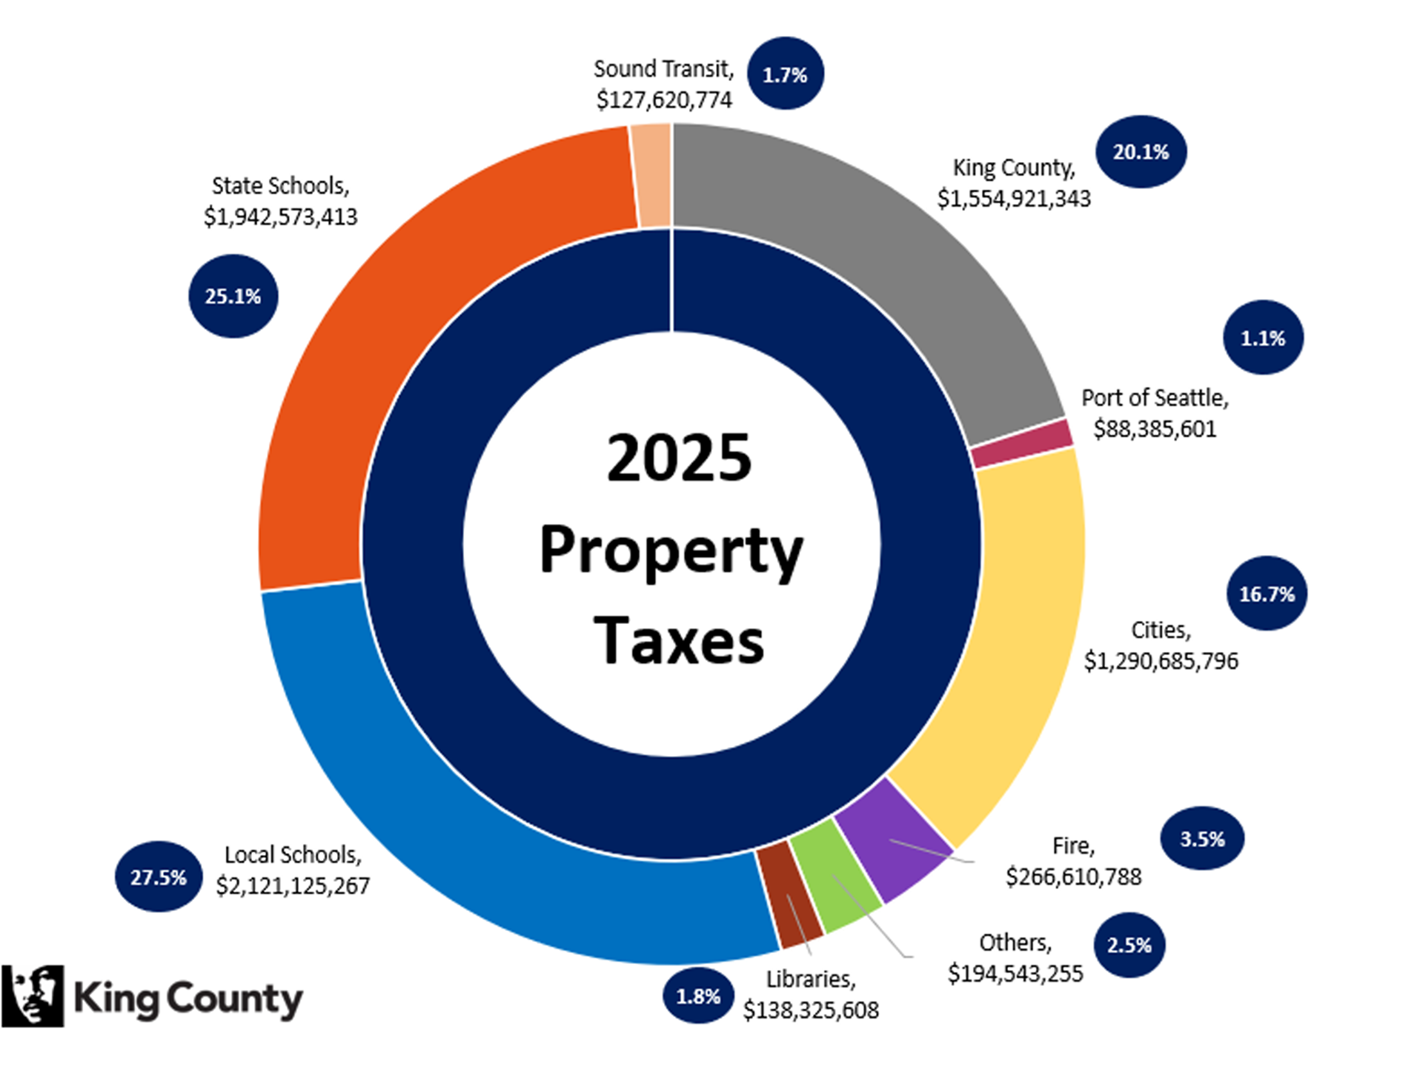
Property taxes are almost exclusively local. While state governments may provide the legal framework and oversight for how assessments are conducted, they rarely collect the revenue. Instead, the funds stay within the county, municipality, or special taxing district. For most homeowners in 2026, the largest portion of their tax bill—often exceeding 50%—is directed toward the local public school district. The remainder supports:
- Public Safety: Funding for police, fire departments, and EMS.
- Infrastructure: Road maintenance, bridge repairs, and public transportation.
- Libraries and Parks: Operational costs for community recreational spaces.
- General Administration: The salaries of local government employees and the maintenance of public records.
How Your Property Tax Bill is Calculated
The formula for property tax seems simple on the surface: Assessed Value × Tax Rate = Total Tax. However, each variable in this equation contains complexities that can significantly alter the final amount due.
1. Determining Market Value
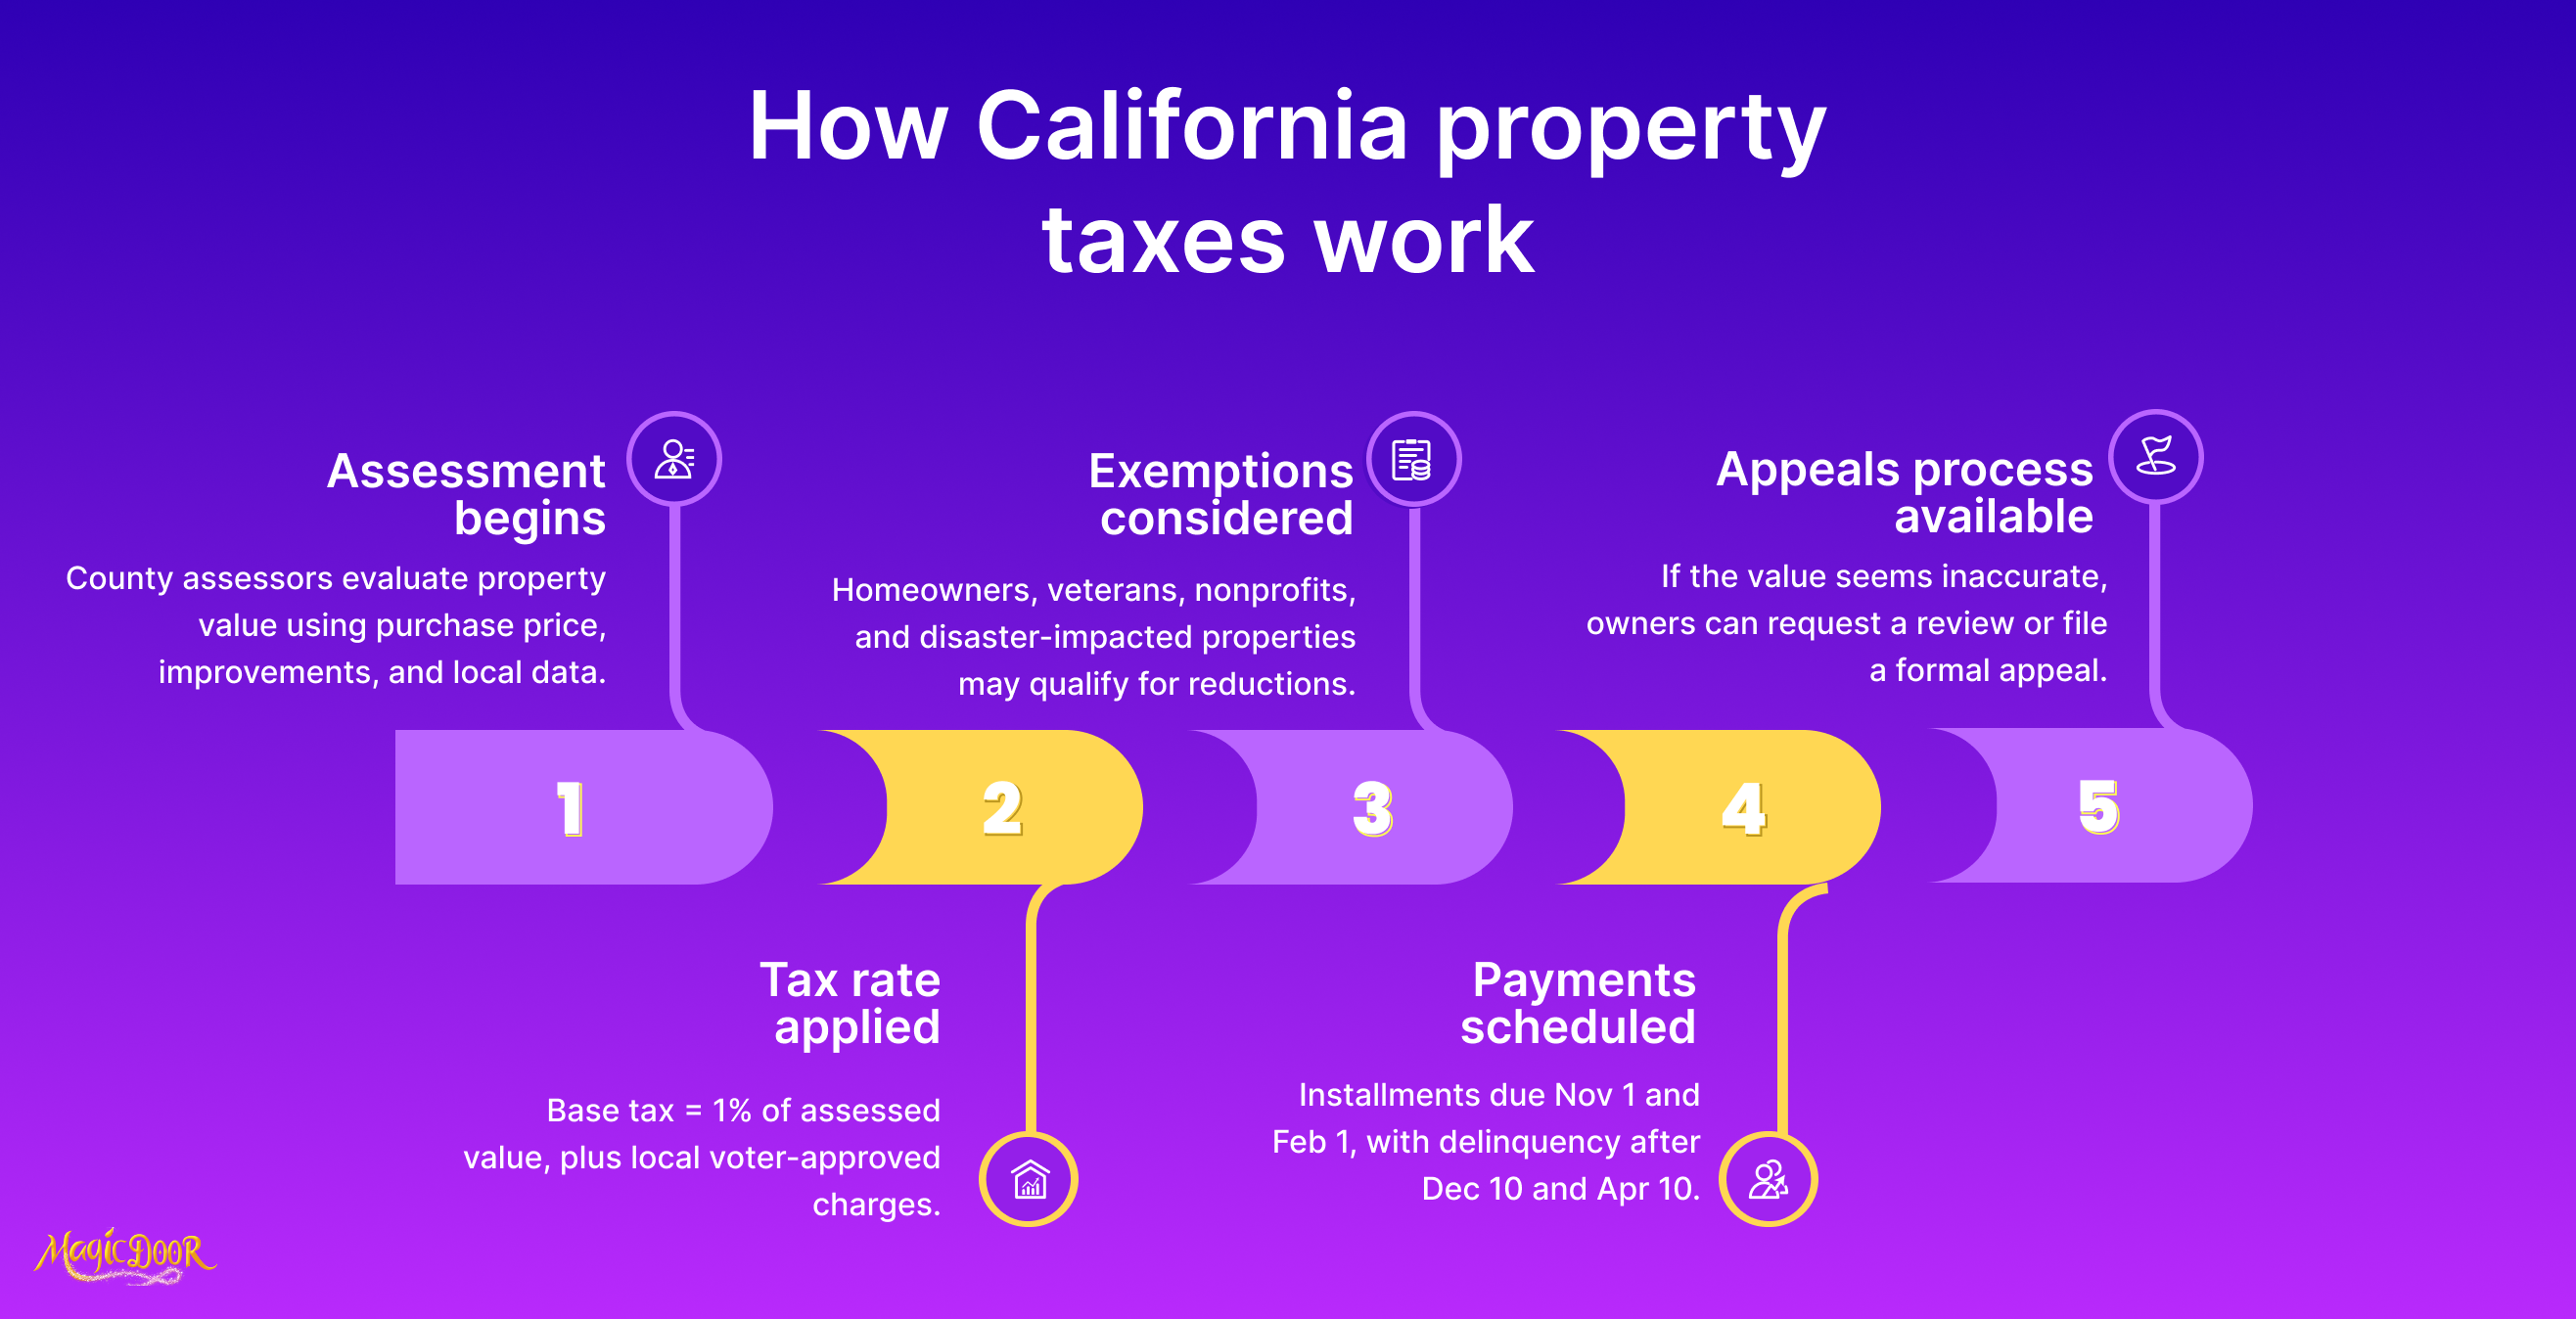
The process begins with the Tax Assessor determining the "Fair Market Value" of the property. This is the price at which the property would change hands between a willing buyer and a willing seller in an open market. In 2026, assessors rely heavily on Computer-Assisted Mass Appraisal (CAMA) systems, which analyze recent sales of comparable properties ("comps"), construction costs, and localized economic trends.
2. The Assessment Ratio
Not all jurisdictions tax 100% of the market value. Many states use an assessment ratio. For example, if your home has a market value of $500,000 and the state’s assessment ratio is 80%, your "Assessed Value" for tax purposes is $400,000.
3. Applying the Millage Rate
The tax rate is expressed in "mills." One mill represents $1 of tax for every $1,000 of assessed value. To calculate the decimal equivalent, you divide the millage rate by 1,000.
Example Calculation:
- Market Value: $450,000
- Assessment Ratio: 100%
- Total Millage Rate: 15 mills (0.015)
- Calculation: $450,000 × 0.015 = $6,750 Annual Tax
The Role of the Property Tax Assessor
The tax assessor is a public official responsible for discovering, listing, and valuing all taxable property within a jurisdiction. It is a common misconception that the assessor sets the tax rate; in reality, their sole job is to ensure that the "tax burden" is distributed fairly based on property wealth.
Valuation Cycles
Assessment schedules vary by location. Some jurisdictions conduct annual revaluations, while others may only reassess property every three to five years. In 2026, many regions have moved toward "rolling assessments," where a portion of the county is re-evaluated each year to prevent the "sticker shock" of a massive jump in value after a long period of stagnation.
Physical Inspections vs. Data Analysis
While assessors have the right to perform physical inspections, the sheer volume of properties usually makes this impossible for every tax cycle. Most assessments are "desk appraisals" based on:
- Permit Data: New decks, finished basements, or additions recorded with the building department.
- Aerial Imagery: High-resolution satellite and drone photography used to detect unregistered improvements.
- Market Trends: Price-per-square-foot data from the local Multiple Listing Service (MLS).
Common Exemptions and Tax Relief Programs
To mitigate the burden on certain populations, local and state governments offer various exemptions. These do not necessarily lower the tax rate but instead reduce the taxable value of the property.
| Exemption Type | Typical Eligibility | Impact on Tax Bill |
|---|---|---|
| Homestead Exemption | Primary residences only | Deducts a flat amount (e.g., $25,000) from assessed value or caps annual increases. |
| Senior Citizen | Owners aged 65+ with income limits | Significant reduction or "freeze" on the assessed value. |
| Veterans / Disabled Veterans | Former military personnel | Varies by disability rating; can range from partial to 100% exemption. |
| Disability Exemption | Individuals with permanent disabilities | Reductions similar to senior exemptions. |
| Agricultural (Greenbelt) | Land used for active farming/timber | Assessed based on "use value" rather than "market value." |
| Religious/Non-Profit | Property owned by charitable orgs | Often 100% exempt if used for charitable purposes. |
The Homestead Cap
One of the most vital protections for homeowners in 2026 is the "assessment cap." In many states, once a property is designated as a primary homestead, the assessor is legally barred from increasing the assessed value by more than a certain percentage (e.g., 3% or the rate of inflation) per year, regardless of how much the market value has soared. This provides vital stability for long-term residents.
The Appeals Process: Challenging Your Assessment
If you believe your property tax assessment is inaccurate, you have the legal right to appeal. An appeal is not a protest against high taxes or government spending; it is a technical challenge to the valuation of your property.
Grounds for Appeal
To win an appeal, you must prove one of the following:
- Inaccurate Data: The assessor’s records show four bedrooms when you only have three, or they have overestimated your square footage.
- Lack of Uniformity: Your property is valued significantly higher than nearly identical properties in your immediate neighborhood.
- Market Overvaluation: The assessed value is higher than what you could reasonably sell the home for in the current 2026 market.
Steps to File an Appeal
- Review the Property Card: Request the official record of your property from the assessor's office and check for clerical errors.
- Observe Deadlines: Most jurisdictions provide a very narrow window—typically 30 to 90 days after receiving your assessment notice—to file an appeal.
- Gather Evidence: Collect recent sales data of at least three comparable homes. In 2026, professional independent appraisals are highly persuasive but come with an out-of-pocket cost.
- Informal Meeting: Many disputes are settled in an informal "walk-in" meeting with a staff appraiser.
- Formal Hearing: If the informal meeting fails, you will present your case before a Board of Equalization or a similar quasi-judicial body.
Payment Logistics and Escrow Accounts
For the majority of American homeowners, property taxes are not paid directly to the county in a lump sum. Instead, they are managed through an escrow account (or impound account) handled by the mortgage servicer.
How Escrow Works
Each month, a portion of your mortgage payment is set aside in a non-interest-bearing account. When the tax bill arrives, the lender pays it on your behalf. This ensures that the lender’s collateral (the home) is protected from tax liens.
If you own your home "free and clear" (without a mortgage), you are responsible for paying the bill directly to the Tax Collector. Failure to pay can lead to:
- Interest and Penalties: Often accruing at rates as high as 18% annually.
- Tax Lien Certificate Sales: The local government sells the debt to an investor.
- Tax Foreclosure: The ultimate loss of the property to the government or a lien-holder.
Property Tax Trends in 2026
As we move through 2026, several key trends are shaping the landscape of property taxation. The widespread adoption of AI-driven valuation models has increased the accuracy of assessments but has also led to more frequent challenges regarding "algorithmic bias" or errors in data scraping.
Additionally, many states are seeing a push for "circuit breaker" tax credits. These are programs that provide a tax refund or credit if the property tax exceeds a certain percentage of the household's total income, protecting low-income homeowners from being "taxed out" of rapidly gentrifying neighborhoods.
For more information on federal tax implications related to property, the Internal Revenue Service (IRS) Publication 530 provides guidance on what property taxes are deductible for those who itemize their federal returns. Note that the SALT (State and Local Tax) deduction cap, a major factor in tax planning, remains a point of legislative focus in 2026.
Frequently Asked Questions
Does a new assessment mean my taxes will definitely go up?
Not necessarily. If the local government lowers the millage rate while assessments rise, your tax bill could stay the same or even decrease. This often happens during "revenue neutral" years where the municipality adjusts the rate to ensure they don't collect a massive surplus just because market values spiked.
Can I appeal my property tax because I think the tax rate is too high?
No. An assessment appeal only addresses the value of your property. If you believe the tax rate (the millage) is too high, you must address this through the political process—attending budget hearings, voting on bond referendums, and electing different local officials.
What happens to my property taxes if I renovate my home?
Generally, any renovation that requires a building permit will eventually trigger a reassessment. While minor cosmetic changes like painting or new flooring won't usually affect your taxes, major projects like adding a bedroom, finishing a basement, or installing a pool will increase the "Fair Market Value" and subsequently your tax bill.
Is property tax deductible on federal income taxes in 2026?
Yes, but with limitations. As of 2026, homeowners who itemize their deductions can deduct their state and local real estate taxes. However, the total deduction for all state and local taxes (including income or sales tax) is subject to the federal SALT cap. You should consult a tax professional to see if itemizing is more beneficial than taking the standard deduction.
How do property taxes differ between residential and commercial property?
In many jurisdictions, commercial properties are assessed at a higher ratio than residential properties. Furthermore, commercial valuations are often based on the Income Approach (how much revenue the property generates) rather than just comparable sales, which can make the "tax property" calculation significantly more complex for business owners.
What is a "Tax Lien" and how can I avoid one?
A tax lien is a legal claim placed on a property by the government when taxes are unpaid. It prevents the owner from selling or refinancing the property until the debt is cleared. The best way to avoid a lien is to ensure your contact information is updated with the Tax Collector and to utilize an escrow account if you have difficulty saving for large annual payments.
Practical Recommendation for Homeowners
To ensure you are not overpaying on your property taxes in 2026, perform an annual tax audit. Start by verifying that every exemption you are entitled to—especially the Homestead Exemption—is currently applied to your account. Check your property record card for errors in square footage or "improvements" that do not exist. Finally, monitor the "Notice of Proposed Property Taxes" (often called a TRIM notice) that arrives in the late summer or early fall. This document is your roadmap for the coming year's expenses and provides the specific instructions and deadlines for filing an appeal if the valuation is incorrect.