State Farm’s B2B ecosystem facilitates critical interactions between the insurer and two primary groups: business owners seeking specialized commercial coverage and third-party vendors—such as repair shops and claims adjusters—utilizing the dedicated B2B portal. In 2026, these services prioritize integrated digital claims processing and localized agent support to manage commercial risks and operational partnerships efficiently.
Understanding the Two Pillars of State Farm B2B
To navigate the "b2b statefarm" landscape, one must distinguish between the two distinct ways businesses interact with the organization. The first is as a commercial policyholder, where a business purchases insurance products to protect its assets, employees, and reputation. The second is as a business partner or vendor, where a company provides services to State Farm or its policyholders (such as a glass repair shop or an independent medical examiner) and requires access to State Farm’s internal B2B systems.
In 2026, the convergence of these two pillars is driven by State Farm’s "Good Neighbor" philosophy, which has transitioned into a "Good Digital Neighbor" framework. This approach emphasizes that whether you are buying a policy or fulfilling a claim as a vendor, the interface should be seamless, data-secure, and backed by the massive financial stability of a mutual insurance company.
The Policyholder Perspective: Business-to-Business Insurance
For small to medium-sized enterprises (SMEs), State Farm acts as a primary B2B service provider. Unlike generic online insurers, State Farm utilizes a captive agent model. This means business owners work with a dedicated local representative who understands the specific economic climate of their region. This localized B2B relationship is designed to mitigate the complexities of commercial underwriting, which often involves nuanced risk assessments that automated algorithms might overlook.
The Vendor Perspective: The B2B Portal
The "b2b.statefarm.com" portal is the heartbeat of State Farm’s external partner operations. This secure gateway allows authorized third-party vendors to exchange data, submit invoices, and track claims progress in real-time. This system is essential for maintaining the speed of the "claims-to-resolution" pipeline, ensuring that when a policyholder suffers a loss, the B2B network of service providers can respond without administrative friction.
Comprehensive Small Business Insurance Solutions
State Farm’s B2B insurance portfolio is structured to provide foundational protection while allowing for industry-specific endorsements. In 2026, the focus has shifted toward addressing evolving risks like cyber threats and remote workforce liabilities.
Business Owners Policy (BOP)
The Business Owners Policy is the most common entry point for B2B coverage. It functions as a bundled solution, typically combining general liability insurance and property insurance into a single contract.
- General Liability: Protects the business against claims of bodily injury or property damage caused by business operations. In a B2B context, this is often a prerequisite for signing contracts with larger corporations or government entities.
- Commercial Property: Covers the physical assets of the business, including buildings, equipment, and inventory. For 2026, State Farm has expanded definitions of "business property" to include specialized tech hardware used in mobile or hybrid work environments.
- Loss of Income: If a covered peril (like a fire) forces the business to close temporarily, this coverage helps replace lost revenue and pay for ongoing expenses like rent and payroll.
Professional Liability (Errors & Omissions)
For service-based businesses—such as consultants, accountants, and architects—State Farm offers Professional Liability insurance. This B2B product protects against claims of negligence, misrepresentation, or inaccurate advice. As the service economy continues to expand in 2026, this coverage has become essential for maintaining "professional standing" in competitive B2B marketplaces.
Commercial Auto and Fleet Management
Businesses that operate vehicles, whether a single delivery van or a fleet of service trucks, require commercial auto insurance. State Farm’s B2B auto policies differ from personal policies by accounting for higher liability limits and the specific risks associated with employee drivers. State Farm’s 2026 updates include enhanced telematics integration, allowing businesses to potentially lower premiums by demonstrating safe driving habits across their fleet.
The State Farm B2B Partner Portal: Access and Requirements
For vendors looking to collaborate with State Farm, the B2B portal is the mandatory point of entry. Access is not open to the general public; it requires a formal business relationship and rigorous credentialing.
Registration and Eligibility
To become an authorized user of the State Farm B2B portal, a company must usually be part of an established vendor program. This includes:
- Select Service Shops: Auto body shops that have met State Farm’s quality and equipment standards.
- Lenders and Lienholders: Financial institutions that need to verify insurance coverage for mortgaged properties or financed vehicles.
- Medical Providers: Clinics and physicians handling workers' compensation or personal injury protection (PIP) claims.
- Independent Adjusters: Third-party specialists hired to assess large-scale catastrophe losses.
Technical Prerequisites for the B2B Portal
The portal (b2b.statefarm.com) utilizes high-level encryption and multi-factor authentication (MFA). In 2026, users must ensure their systems are compatible with the latest security protocols to prevent data breaches that could compromise policyholder information.
- Browser Requirements: The portal is optimized for modern, Chromium-based browsers and Safari, with legacy support for Internet Explorer having been fully phased out years ago.
- Identity Management: Users are assigned specific roles (e.g., "Billing Clerk" vs. "Manager") to ensure the principle of least privilege is maintained within the B2B ecosystem.
Comparison of State Farm B2B Coverage Types
Choosing the right B2B insurance requires understanding the specific protections offered by different policy types. The following table outlines the core products available in 2026.
| Policy Type | Primary Target | Core Protection | Typical 2026 Use Case |
|---|---|---|---|
| Business Owners Policy (BOP) | Retailers, Small Offices | Property & General Liability | Small brick-and-mortar shops or home-based businesses with inventory. |
| Commercial Auto | Delivery Services, Contractors | Vehicle Liability & Physical Damage | Plumbers, HVAC technicians, and local delivery fleets. |
| Workers' Compensation | Any Business with Employees | Medical costs and lost wages for work injuries | Mandatory in most states for businesses with one or more employees. |
| Professional Liability | Consultants, Lawyers, MDs | Errors, Omissions, Negligence | Protecting a consultant against a lawsuit from a dissatisfied B2B client. |
| Cyber Liability | E-commerce, Tech Firms | Data breach recovery & notification costs | Recovering from a ransomware attack or accidental data leak. |
| Employment Practices Liability (EPLI) | Growing Businesses | Protection against wrongful termination or harassment claims | Managing risks associated with hiring and firing in a complex legal landscape. |
Navigating the B2B Relationship: The Role of the Agent
One of the most significant advantages of the State Farm B2B model is the human intermediary. While many competitors have moved to a direct-to-consumer digital model, State Farm maintains that B2B transactions are too complex for a "one-size-fits-all" website.
Personalized Risk Assessment
A State Farm agent performs a "Business Insurance Review." This is a consultative process where the agent analyzes the specific workflow of the business to identify gaps. For example, a business might have property insurance but realize they lack "Bailee's Coverage," which protects customer property left in their care—a common oversight for repair businesses.
Claims Advocacy
When a business-to-business claim occurs, the agent acts as an advocate. Because the agent lives and works in the same community, they have a vested interest in the business's recovery. This localized support is a cornerstone of the B2B value proposition, particularly during regional catastrophes where national call centers may be overwhelmed.
Compliance and Security in B2B Operations
In 2026, B2B interactions are heavily regulated by state and federal laws, including the National Association of Insurance Commissioners (NAIC) guidelines. State Farm’s B2B infrastructure is designed to help businesses remain compliant.
- Data Privacy: State Farm adheres to strict privacy standards, ensuring that B2B partners who access the portal are not compromising sensitive policyholder data. This is governed by the Gramm-Leach-Bliley Act (GLBA) and various state-level privacy acts.
- Certificate of Insurance (COI) Management: For many B2B contracts, a business must prove they have insurance. State Farm’s B2B portal allows for the rapid generation of COIs, which are digital documents that verify coverage limits to third-party vendors or landlords.
- Financial Stability: State Farm consistently maintains high ratings from agencies like A.M. Best, which is a critical factor for B2B partners. Large corporations often refuse to work with vendors whose insurers do not meet a certain financial strength rating.
Common Challenges and Troubleshooting in State Farm B2B
Even with robust systems, businesses may encounter hurdles when interacting with State Farm’s B2B services.
Portal Access Issues
The most frequent issue reported by vendors is "Account Lockout" or "MFA Failure." Because the B2B portal contains sensitive financial and personal data, security triggers are sensitive.
- Solution: Ensure that your business's IT department has whitelisted State Farm’s domains and that your "Security Coordinator" (the person at your company who manages portal access) has updated your user permissions.
Underwriting Delays
Business owners often find that commercial policies take longer to issue than personal ones. This is because B2B insurance requires "manual underwriting" for specialized risks.
- Solution: Provide complete documentation—including three years of loss runs (claims history) and detailed equipment inventories—at the start of the application process to expedite approval.
Integration with Accounting Software
Many businesses in 2026 want their B2B insurance premiums and claims data to sync directly with platforms like QuickBooks or Xero.
- Solution: While State Farm offers robust online billing, direct API integration for all small business accounts is still evolving. Business owners should consult their agents about the "Business Insurance Gateway" for improved data export features.
Frequently Asked Questions
What is the State Farm B2B portal used for?
The State Farm B2B portal is a secure online platform used primarily by third-party service providers, such as auto repair shops, medical providers, and financial institutions. It allows these partners to manage claims, exchange sensitive documents, and process payments directly with State Farm. It is not intended for individual policyholders to manage their personal accounts.
How can a small business get a B2B insurance quote?
To obtain a B2B or commercial insurance quote, a business owner should contact a local State Farm agent. While some basic information can be submitted online, the complexity of business risks usually requires a consultation to ensure that coverage limits (such as general liability and property) are appropriate for the specific industry.
Is State Farm B2B insurance available for high-risk industries?
State Farm provides B2B coverage for a wide variety of industries, including contractors, professional services, and retail. However, businesses in extremely high-risk categories (such as heavy industrial manufacturing or high-hazard chemical processing) may be redirected to specialized surplus lines or commercial brokers, as State Farm primarily focuses on small to medium-sized business risks.
Can I manage my employees' benefits through State Farm B2B?
Yes, State Farm offers B2B solutions for employee benefits, including group life insurance and disability insurance. These products are designed to help small businesses remain competitive in the labor market by offering "big company" benefits to their staff.
How do I reset my State Farm B2B portal password?
If you are a vendor or partner, you can typically reset your password on the B2B portal login page. If you are unable to do so, you must contact your company’s internal "Security Coordinator," who has the authority to manage user accounts and reset credentials for your specific business entity.
Practical Recommendations for Businesses
To maximize the value of a State Farm B2B relationship in 2026, businesses should take proactive steps rather than viewing insurance as a passive expense.
- Conduct an Annual Risk Audit: Schedule a meeting with your agent every year. As your business grows, your B2B needs change. A policy that worked for a three-person startup will not provide adequate protection for a ten-person firm with a physical warehouse.
- Leverage Risk Management Tools: State Farm provides B2B policyholders with access to safety training materials and disaster recovery planning tools. Using these resources can reduce the likelihood of a claim and may, over time, help manage premium costs.
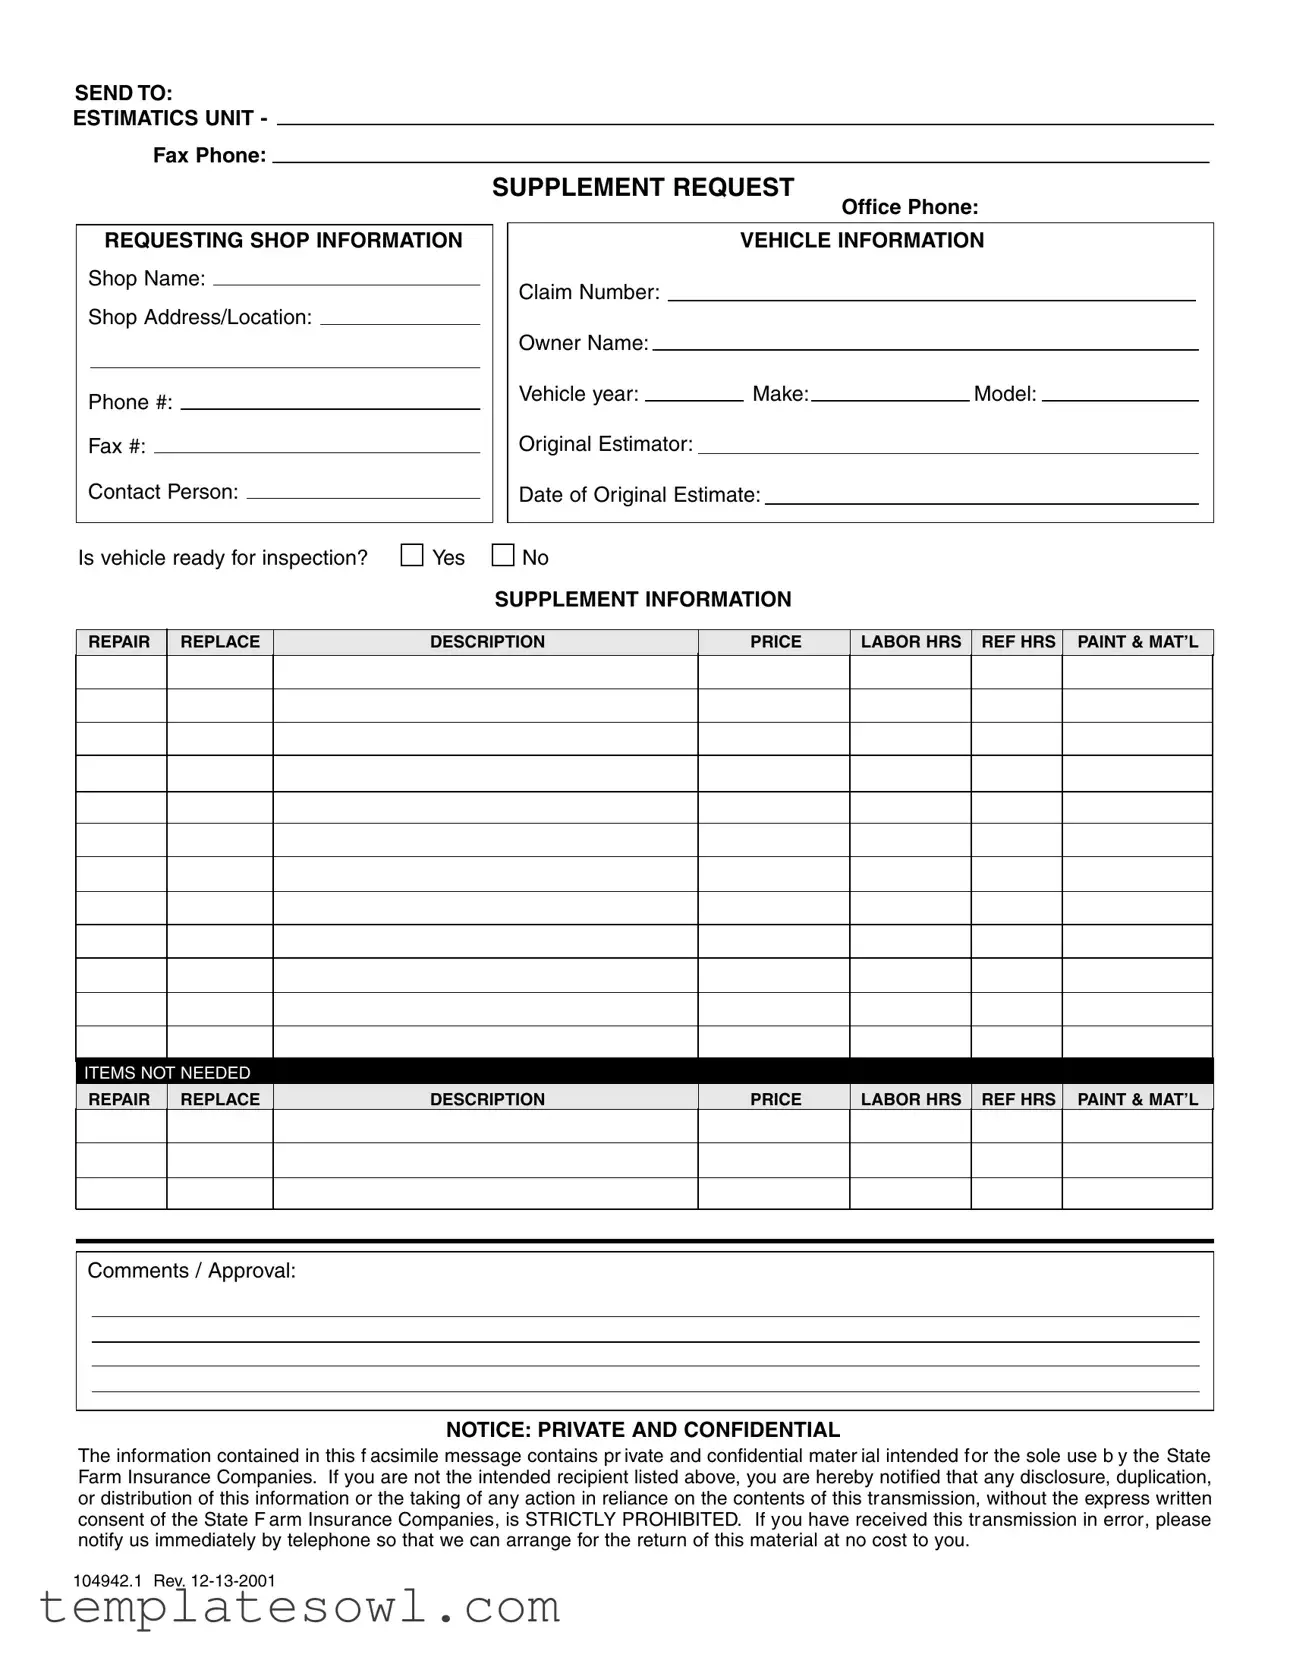
- Document Everything for the B2B Portal: If you are a vendor, ensure that all photographs, estimates, and invoices uploaded to the portal are high-resolution and clearly labeled. This reduces the "back-and-forth" with claims adjusters and speeds up your payment cycle.
- Verify Coverage for Subcontractors: If your business hires other businesses (B2B2B), ensure that your State Farm policy covers vicarious liability or that you have a system in place to verify that your subcontractors carry their own adequate insurance.