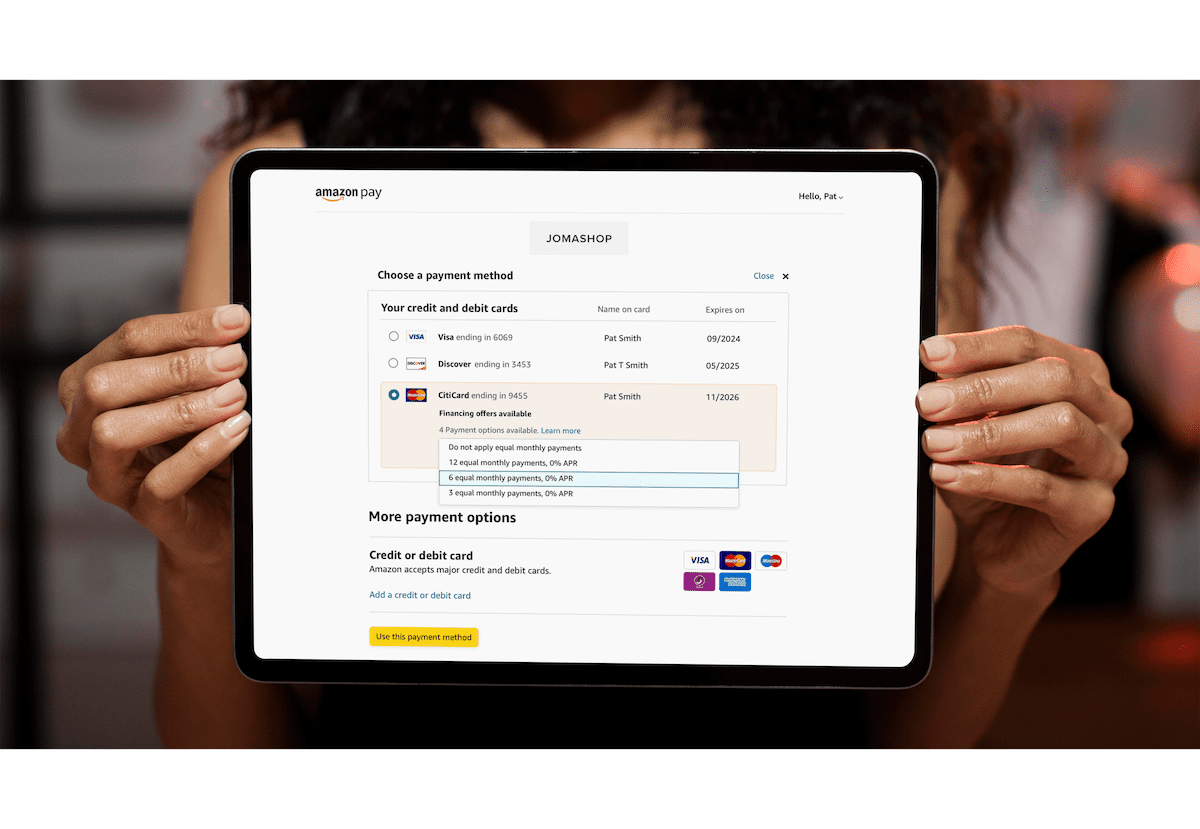
Citibank Pay encompasses the various digital and traditional payment mechanisms provided by Citibank to help customers manage bill payments, credit card balances, loan installments, and peer-to-peer money transfers. Whether paying a credit card bill from an external checking account, settling a monthly mortgage statement, or executing a fast digital transaction via mobile platforms, understanding the specific channels, processing times, and eligibility rules is essential for maintaining financial health and avoiding late fees.
Understanding Citibank Pay Channels and Services
Navigating the ecosystem of Citibank payment services requires recognizing the distinctions between internal account transfers, external bill pay utilities, and digital wallet integrations. Citibank offers multiple distinct avenues for moving money, each tailored to different financial obligations.
At its core, the payment infrastructure supports everything from routine consumer credit card settlements to complex commercial transactions. Customers interact with these services primarily through online banking portals, dedicated mobile applications, telephone banking systems, and physical branch networks.
The primary objective of these payment systems is to provide security, speed, and reliability. When initiating a payment through Citibank, transactions pass through rigorous verification protocols designed to prevent unauthorized access and protect sensitive banking data.
However, operational constraints such as cutoff times, clearing house schedules, and weekend processing holds can affect when funds actually post to a payee's account. Knowing these mechanics helps users prevent accidental overdrafts and avoid missing payment due dates.
The Evolution of Digital Payment Portals
Over the past decade, financial institutions have transitioned from paper-based and telephone-heavy payment processing toward automated, app-driven interfaces. Citibank Pay mechanisms reflect this shift, incorporating features like biometric authentication, real-time balance tracking, and instant push notifications.
Digital dashboards allow users to view scheduled payments, examine historical transaction data, and configure automated recurring transfers with minimal friction.
Despite these technological advancements, the foundational rules governing financial transfers remain consistent. Federal regulations, banking disclosures, and institutional fee schedules dictate how payments are processed, what liabilities consumers hold in the event of errors, and how disputes are handled. Balancing convenience with financial awareness is crucial for anyone utilizing these digital banking tools.
Eligibility, Prerequisites, and Account Setup
Before initiating any transaction through Citibank Pay services, users must satisfy specific account prerequisites and security validations. Not all payment features are open to every account tier, and certain geographic or account-status restrictions apply.
Account Verification and Authentication Requirements
To utilize online and mobile payment features, customers must maintain an active Citibank checking, savings, or credit card account in good standing. Security protocols mandate multi-factor authentication (MFA) to verify identity before setting up new payees or executing high-value transfers. This typically involves:
- Entering a unique One-Time Password (OTP) sent via SMS or email.
- Verifying identity through biometric scans (such as fingerprint or facial recognition) on compatible mobile devices.
- Answering predefined security questions established during initial account registration.
- Confirming external bank routing and account numbers via micro-deposits for linked external funding sources.
Preparing External Accounts for Linking
When users wish to pay Citibank credit cards from non-Citibank accounts—or conversely, use Citibank Bill Pay to pay external vendors—linking accounts requires careful validation. Users must provide accurate routing transit numbers (RTNs) and individual account numbers.
Financial institutions often require a verification period where two small, randomized deposits are made to the external account, which the user must then log in and confirm to finalize the link.
| Payment Method | Typical Processing Time | Standard Fees | Best Used For |
|---|---|---|---|
| Citibank Internal Transfer | Instant | None | Moving funds between own checking, savings, and credit cards. |
| Citibank Online Bill Pay | 1 to 3 Business Days | None for standard delivery | Paying recurring utility, mortgage, or credit card bills to external vendors. |
| External ACH Payment (Pull) | 2 to 4 Business Days | Dependent on originating institution | Pulling funds from an outside bank account to pay a Citibank loan or card. |
| Wire Transfer (Domestic) | Same Day (if before cutoff) | Varies by account tier | High-value, time-sensitive property or asset purchases. |
Step-by-Step Guide to Executing Payments
Executing payments securely requires following structured workflows designed to minimize user error and catch discrepancies before funds leave the account. Whether paying a credit card bill or setting up a recurring utility payment, adherence to proper procedural steps protects against lost payments and missed deadlines.
Making a Credit Card Payment
Settling a Citibank credit card balance is one of the most frequent tasks performed through the payment portal. Users can choose between paying the minimum amount due, the full statement balance, a fixed custom amount, or the current total balance.
- Log In: Access the official Citibank online banking portal using secure credentials or open the mobile application and authenticate via biometrics.
- Navigate to Payments: Select the "Payments" or "Transfers" tab from the primary dashboard navigation menu.
- Select Source and Destination: Choose the funding account (such as a Citibank checking account or a verified external bank account) as the source, and select the Citibank credit card as the destination.
- Specify Amount and Timing: Choose the payment amount option (Minimum Due, Statement Balance, or Other Amount) and select the delivery date. For immediate posting, select today's date, keeping daily cutoff times in mind.
- Review and Submit: Carefully inspect the confirmation screen detailing the source account, destination card, transfer amount, and scheduled date. Click "Submit" or "Confirm" to authorize the transaction.
- Save Confirmation: Note the confirmation number provided upon successful submission for your personal records.
Setting Up Recurring External Bill Pay
For monthly fixed or variable obligations—such as rent, utilities, or insurance premiums—setting up automated bill pay eliminates the risk of human oversight leading to late fees.
- Add a Payee: Navigate to the Bill Pay section and select "Add Payee." Input the exact billing name, billing address, and account number as they appear on your physical paper statement.
- Configure Payment Frequency: Choose whether the payment should occur on a one-time basis or repeat monthly, quarterly, or annually.
- Set Amount Rules: Define whether the payment should be a fixed recurring sum or set to pay the "current bill amount" (where supported by electronic biller integration, known as e-Bills).
- Establish Safety Buffers: Schedule payment initiation dates at least three to five business days before the actual due date to account for postal delivery (if paper checks are printed and mailed) and merchant processing delays.
- Authorize and Monitor: Finalize the setup and monitor the initial transactions closely to ensure the merchant successfully applies the funds to the correct account ledger.
Cutoff Times, Processing Windows, and Fees
Understanding the temporal constraints of banking operations is essential for avoiding late fees and interest charges. Financial transactions do not always process instantaneously, and weekends, federal holidays, and daily operational cutoffs heavily influence when funds settle.
Daily Processing Cutoffs
Citibank establishes daily processing cutoff times (typically structured around Eastern Time). Transactions initiated on business days prior to the cutoff time (often 8:00 PM EST, though this varies by service type) are processed with that day's effective date.
Transactions initiated after the cutoff time, on weekends, or during federal banking holidays are processed on the next subsequent business day.
Failure to account for these windows can result in payments posting a day late, potentially triggering late payment penalties from merchants or credit bureaus. Consumers should always verify the posted schedule within their specific account agreement documents.
Fee Structures and Cost Considerations
Standard electronic bill payments and internal transfers are typically provided to retail customers without direct transaction fees. However, specialized services carry distinct cost schedules:
- Domestic Wire Transfers: Subject to outgoing wire fees unless offset by qualifying high-tier account balances (such as Citigold or Citi Priority statuses).
- International Wire Transfers (FX): Subject to wire fees plus currency conversion spreads and intermediary bank fees.
- Returned Payment Fees: Assessed if a payment is initiated with insufficient funds (NSF) in the source account, which may trigger fees from both Citibank and the payee.
- Expedited Payments: Rare rush services may incur flat administrative fees if available for specific billers.
Common Mistakes and Troubleshooting
Even with robust digital interfaces, users occasionally encounter friction points, rejected transactions, or delayed postings. Recognizing common pitfalls helps resolve issues quickly before they impact credit scores or financial standing.
Incorrect Payee Information
The most frequent cause of delayed or lost bill payments is entering incorrect account numbers or mailing addresses when setting up external payees. If a biller's name or account number does not match their internal accounting records precisely, funds may sit in a suspense account or be returned to Citibank.
- Troubleshooting: If a payment does not show up on the merchant's end after five business days, access your Citibank payment history, verify the exact details entered, and obtain the transaction trace number. Contact Citibank customer support to initiate a payment trace.
Insufficient Funds and Overdrafts
Initiating payments when account balances are inadequate can lead to rejected transactions, bounced check fees, and administrative charges from third-party billers.
- Troubleshooting: Set up low-balance alerts and link a secondary overdraft protection account (such as a savings account or line of credit) to prevent accidental overdrafts when automated payments execute.
Browser Compatibility and Session Timeouts
Online banking security protocols automatically log users out after periods of inactivity. Interrupted internet connections during payment submission can create ambiguity regarding whether a transaction was successfully transmitted.
- Troubleshooting: Never attempt to resubmit a payment immediately after a timeout without first checking your account history or pending transaction list to verify whether the initial attempt registered. Submitting duplicate payments can result in double-withdrawal from your funding account.
Frequently Asked Questions
Can I use Citibank Pay to send money to someone who does not bank with Citibank?
Yes. You can use electronic bill pay services to send funds to external individuals or businesses by setting them up as payees. For individual-to-individual transfers, integrated services like Zelle allow you to send money directly from your Citibank mobile app using the recipient's email address or mobile phone number.
What happens if I schedule a payment for a weekend or holiday?
Payments scheduled for weekends or federal banking holidays are generally processed on the next business day. To avoid late fees, always ensure your scheduled payment date falls at least one to two business days before your actual merchant due date.
Are there limits on how much I can pay or transfer daily?
Yes. Citibank enforces security and risk-management limits on daily transfers and bill payments. These limits vary based on your account type, customer tenure, and verification level. You can view your specific limits within the online banking security center or request temporary limit increases by contacting customer support.
How do I cancel a pending payment?
If a payment is still listed as "Pending" or "Scheduled" in your online banking dashboard, you can typically cancel it by selecting the transaction and clicking the cancellation option. Payments that have already transitioned to "Processed" or "Completed" status cannot be canceled and must be resolved directly with the payee.
What should I do if a scheduled payment fails to reach the merchant?
First, check your Citibank account history to confirm whether the funds were successfully debited. Next, retrieve the transaction reference details and contact Citibank customer service to verify the routing status. If the funds were delivered but not applied by the merchant, provide the merchant with the trace number or confirmation proof provided by your bank.
Conclusion and Next Actions
Effectively managing your financial obligations through Citibank Pay requires a combination of proactive scheduling, awareness of processing cutoffs, and careful verification of account details. To maintain optimal financial standing, audit your recurring bills monthly, maintain adequate account buffers to prevent overdrafts, and leverage mobile alerts to track payment execution in real time. Log into your Citibank dashboard today to review your current scheduled payments, verify your linked external accounts, and ensure all upcoming financial obligations are secured.