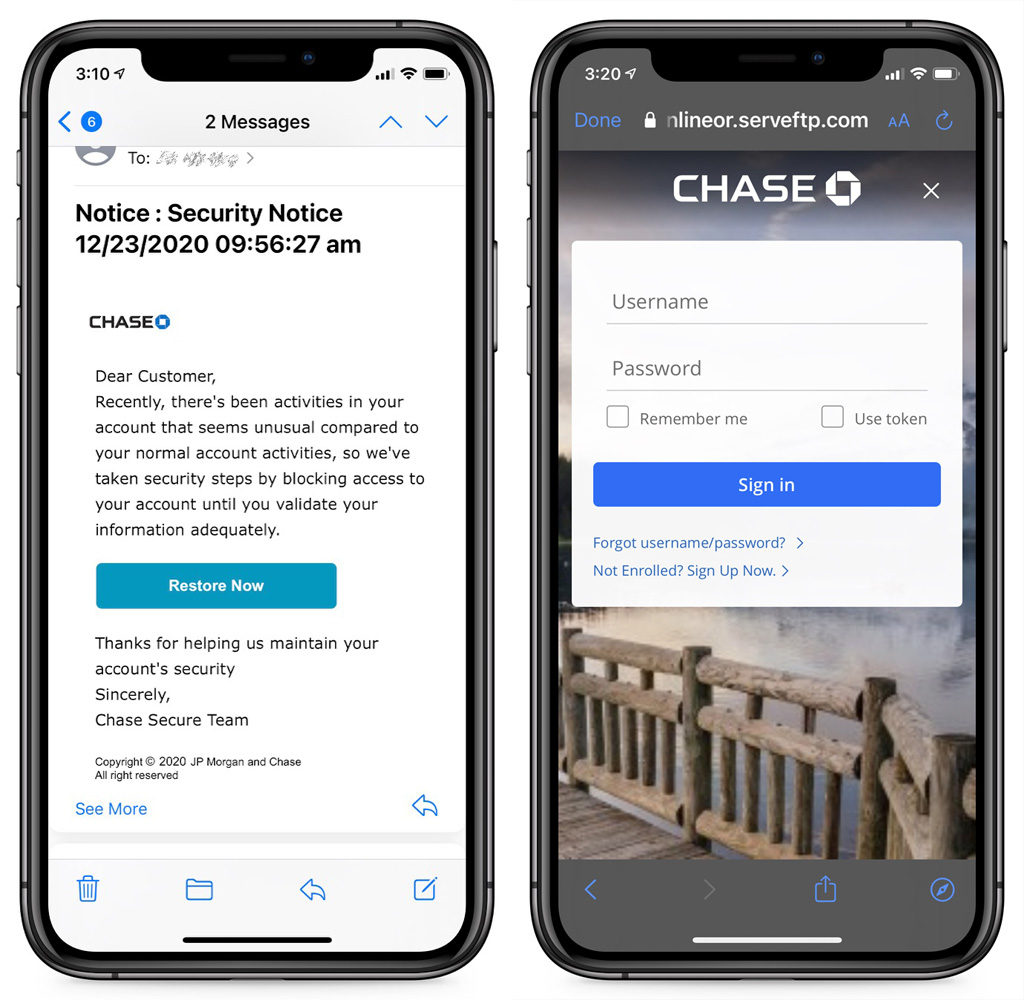
When you encounter Chase fraud, the most critical immediate step is to contact JPMorgan Chase customer service or log into your Chase Mobile app or online account to lock your card and report the unauthorized transaction. Acting swiftly limits your financial liability, initiates the dispute process, and prompts the bank to issue a replacement card with new account details.
Dealing with financial fraud can feel overwhelming, especially when unexpected charges appear on your bank statements or credit card accounts. As one of the largest financial institutions in the United States, JPMorgan Chase processes billions of transactions daily, making it a frequent target for malicious actors employing sophisticated cybercrime techniques. Understanding how Chase identifies suspicious activity, what protections apply to your accounts, and how to navigate the dispute process is essential for safeguarding your hard-earned money.
The Landscape of Chase Fraud and Security Systems
Financial institutions face a constant barrage of automated attacks, credential-stuffing schemes, and social engineering campaigns designed to separate consumers from their funds. JPMorgan Chase invests heavily in proprietary fraud-detection algorithms, machine learning models, and real-time monitoring systems designed to catch anomalies before they result in catastrophic losses.
Security systems analyze transaction patterns based on historical spending behavior, geographic location, merchant risk profiles, and transaction velocity. If your card is used in a physical store in New York and five minutes later attempts a high-value online purchase from a foreign IP address, automated tripwires trigger immediately. However, cybercriminals continually adapt, utilizing phishing emails, smishing (SMS phishing) texts, and malicious data breaches to acquire legitimate account credentials and bypass basic automated checks.
To protect yourself, you must understand the distinction between different types of fraudulent events. Unauthorized debit or credit card transactions, account takeovers, fraudulent wire transfers, and identity theft require distinct reporting mechanisms and regulatory frameworks.
Common Types of Fraud Affecting Chase Customers
Fraudsters employ a wide array of vectors to target Chase checking accounts, savings accounts, credit cards, and business lines. Recognizing these tactics allows you to spot vulnerabilities in your personal security habits and respond appropriately if an incident occurs.
Unauthorized Card Transactions
This category includes skimming devices placed on ATMs or gas station pumps, database breaches where card numbers are leaked, and random number generation attacks. An unauthorized card transaction occurs when someone uses your physical debit or credit card—or its digital token—without your knowledge or consent, and you did not benefit from the purchase.
Account Takeover (ATO)
An account takeover is a severe form of identity theft where a criminal gains full access to your online or mobile Chase banking profile. By acquiring your username, password, and two-factor authentication bypass codes through phishing or malware, the fraudster can change your contact information, transfer funds out of your account, intercept direct deposits, or open new lines of credit in your name.
Impersonation and Phishing Scams
Many consumers are tricked into voluntarily authorizing payments to fraudsters. In these scenarios, a scammer might pose as Chase fraud department personnel, government officials, or utility providers, convincing you to wire money or send funds via peer-to-peer (P2P) services like Zelle under false pretenses. Recovering funds lost through authorized peer-to-peer transfers is significantly more challenging than disputing unauthorized merchant charges.
Legal Protections and Liability Limits
Consumers are not entirely at the mercy of criminals when banking with major institutions. Federal regulations provide robust consumer protections, though the rules differ depending on whether you are using a debit card, a credit card, or an electronic fund transfer (EFT).
Credit Card Protections (Fair Credit Billing Act)
Under the Fair Credit Billing Act (FCBA), your liability for unauthorized credit card charges is legally capped at a maximum of $50. In practice, major issuers like Chase enforce a "Zero Liability" policy for unauthorized charges reported promptly, meaning you pay nothing out of pocket if your credit card number is stolen and misused.
Debit Card and Electronic Fund Transfers (Regulation E)
Checking accounts and debit cards are governed by Regulation E, which outlines consumer liability for unauthorized electronic fund transfers. Your liability depends heavily on how quickly you report the loss or theft of your card or the appearance of unauthorized charges on your statement:
- Notification within 2 days: If you notify Chase within two business days after learning of the loss or theft of your debit card, your maximum liability is $50.
- Notification after 2 days but within 60 days: If you fail to notify Chase within two business days of learning of the loss, but report it within 60 calendar days after your periodic statement is sent, your liability can rise up to $500.
- Notification after 60 days: If you fail to report an unauthorized electronic fund transfer within 60 days after the transmittal of the periodic statement, you risk losing all the money you lost after the 60-day period if Chase can prove it could have stopped the thief had you reported it earlier.
| Account Type | Governing Regulation | Maximum Legal Liability | Typical Issuer Policy |
|---|---|---|---|
| Credit Cards | Fair Credit Billing Act (FCBA) | $50 | Zero Liability Protection |
| Debit Cards / Checking | Regulation E | Up to Total Loss (depending on delay) | Zero Liability if reported promptly |
| Wire Transfers | Uniform Commercial Code (UCC) Article 4A | Varies by timing and error type | Strict verification protocols |
Step-by-Step Guide to Reporting Fraud to Chase
If you discover suspicious activity on your Chase account, executing a systematic response minimizes damage and accelerates the investigation. Follow this structured sequence to resolve the issue effectively.
1. Secure Your Account Immediately
Before speaking to a representative, use the Chase Mobile app or log into the desktop portal to lock or freeze your compromised card. If you suspect an account takeover, change your online banking password immediately and update your security questions. Revoke any unrecognized devices linked to your profile.
2. Contact Official Chase Support
Reach out to Chase using verified phone numbers found on the back of your debit or credit card, or on the official Chase Customer Service portal. Avoid calling numbers listed in suspicious text messages or emails, as these often route directly to fraudsters posing as bank agents.
3. File a Formal Dispute or Fraud Claim
Provide the bank's fraud department with exact details regarding the fraudulent transactions, including dates, merchant names, and exact dollar amounts. For unauthorized transactions, Chase will typically issue a provisional credit while they investigate the claim, which can take anywhere from a few business days to several weeks depending on the complexity and regulatory guidelines.
4. Monitor Your Credit Reports
If your personal information or Social Security number was compromised during the incident, place a security freeze or fraud alert on your credit files with the three major credit bureaus: Equifax, Experian, and TransUnion. Review your official credit reports regularly via AnnualCreditReport.com to ensure no unauthorized accounts were opened in your name.
Preventing Future Fraud: Best Practices
Proactive security habits significantly reduce your exposure to financial fraud. Implementing layered defenses protects your accounts from automated attacks and sophisticated social engineering.
- Enable Real-Time Alerts: Configure push notifications and text alerts within the Chase Mobile app for every transaction, large withdrawal, or password change.
- Use Strong, Unique Authentication: Never reuse passwords across financial accounts, email providers, and retail sites. Utilize a reputable password manager and enable multi-factor authentication (MFA) utilizing authenticator apps rather than SMS-based codes when possible.
- Verify Communications: Banks will never call, text, or email asking for your full account number, online banking password, full Social Security number, or one-time verification codes. If you receive an unexpected communication, hang up and dial the official number on the back of your card.
- Inspect Physical Hardware: When using ATMs or gas station payment terminals, give the card reader a gentle tug to check for physical skimmers, and shield your keypad when entering your Personal Identification Number (PIN).
Frequently Asked Questions
How long does Chase take to investigate a fraud claim?
Chase typically investigates fraud claims within 10 to 45 business days, depending on the type of account and transaction involved. For debit card disputes under Regulation E, the bank often issues a provisional credit to your account within 10 business days while the formal investigation is completed.
Will I get my money back if I was scammed into sending money via Zelle?
Recovering funds sent voluntarily through peer-to-peer services like Zelle is exceptionally difficult. Because you authorized the transfer, banks often classify these transactions as valid, meaning fraud protections under Regulation E may not apply. However, you should still report the scam to Chase immediately to see if the recipient's account can be flagged or frozen.
What should I do if my Chase debit card is physically stolen?
Immediately lock the card within the Chase Mobile app to block any new transactions. Call Chase customer support to report the card lost or stolen, request a permanent replacement card, and review your recent transaction history for any unauthorized charges made before you locked the card.
Can Chase close my account if I report too many fraudulent transactions?
While falling victim to fraud is not your fault, banks evaluate overall account risk. If an account experiences repeated security compromises, high-risk activity, or suspected misuse, Chase reserves the right to close the account under their deposit account agreement to mitigate financial risk for both parties.
How can I spot fake Chase fraud alert text messages?
Legitimate automated fraud alerts from Chase will typically ask you to reply with a simple yes or no regarding a specific transaction, or direct you to open your official Chase Mobile app. They will never include clickable links to log into a login portal or ask you to read back a verification code over the phone.
Next Actions and Professional Guidance
If you are dealing with complex identity theft or substantial financial losses that Chase denies covering, consider filing complaints with federal regulatory bodies such as the Consumer Financial Protection Bureau (CFPB) or the Office of the Comptroller of the Currency (OCC). For severe cases of identity theft involving legal complications or compromised credit files, consulting a certified credit counselor or an attorney specializing in consumer financial protection can provide tailored legal recourse.