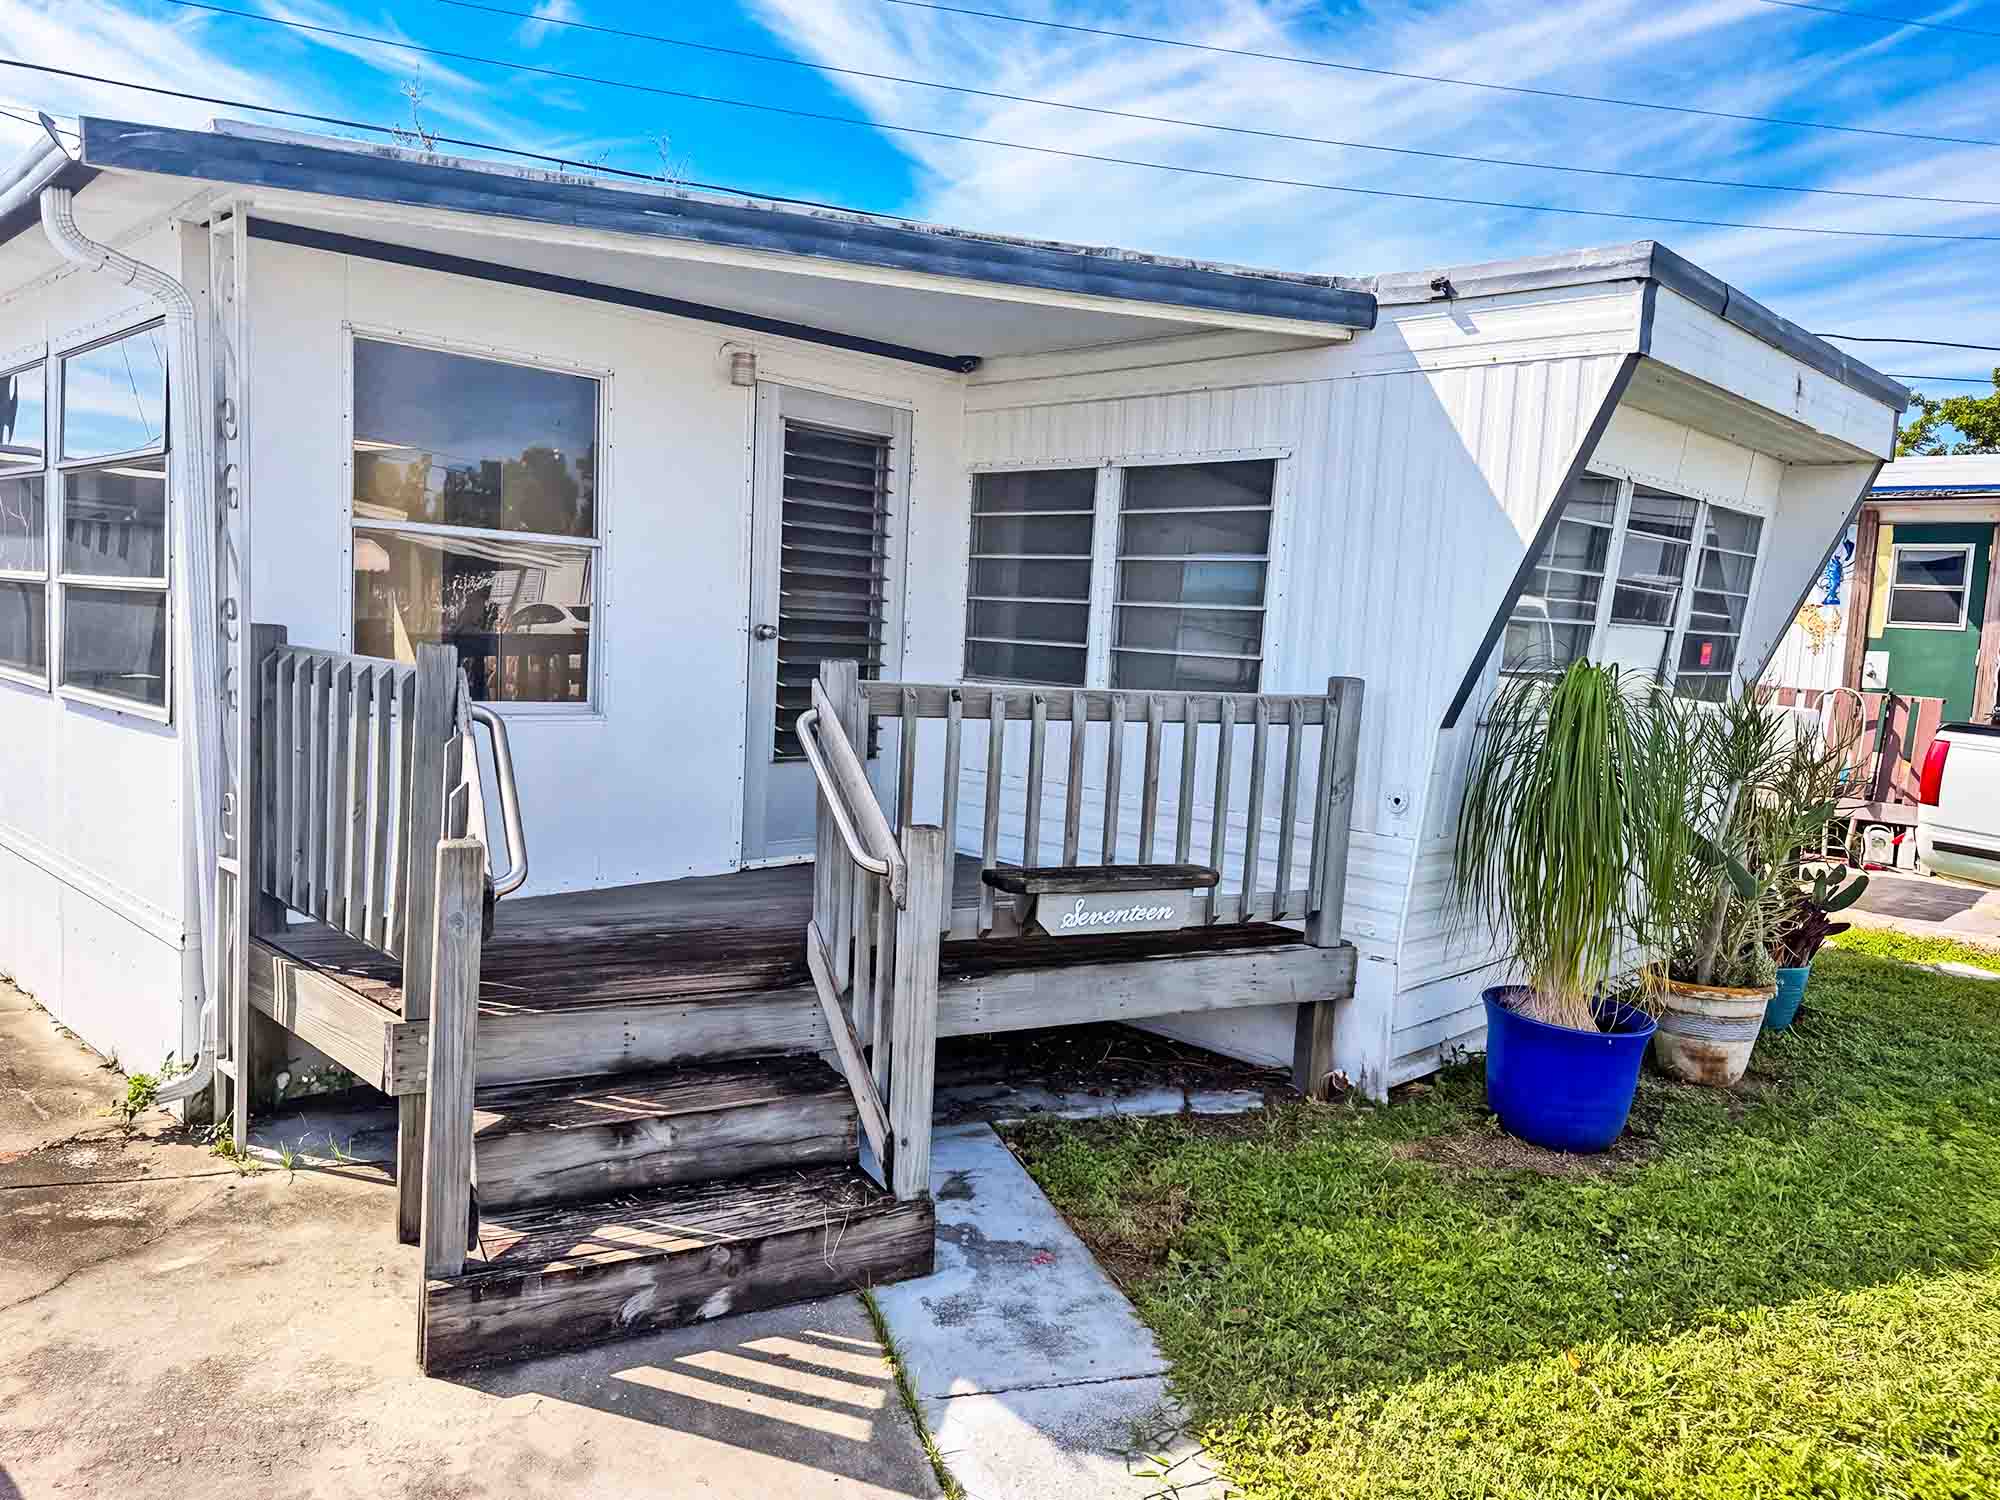
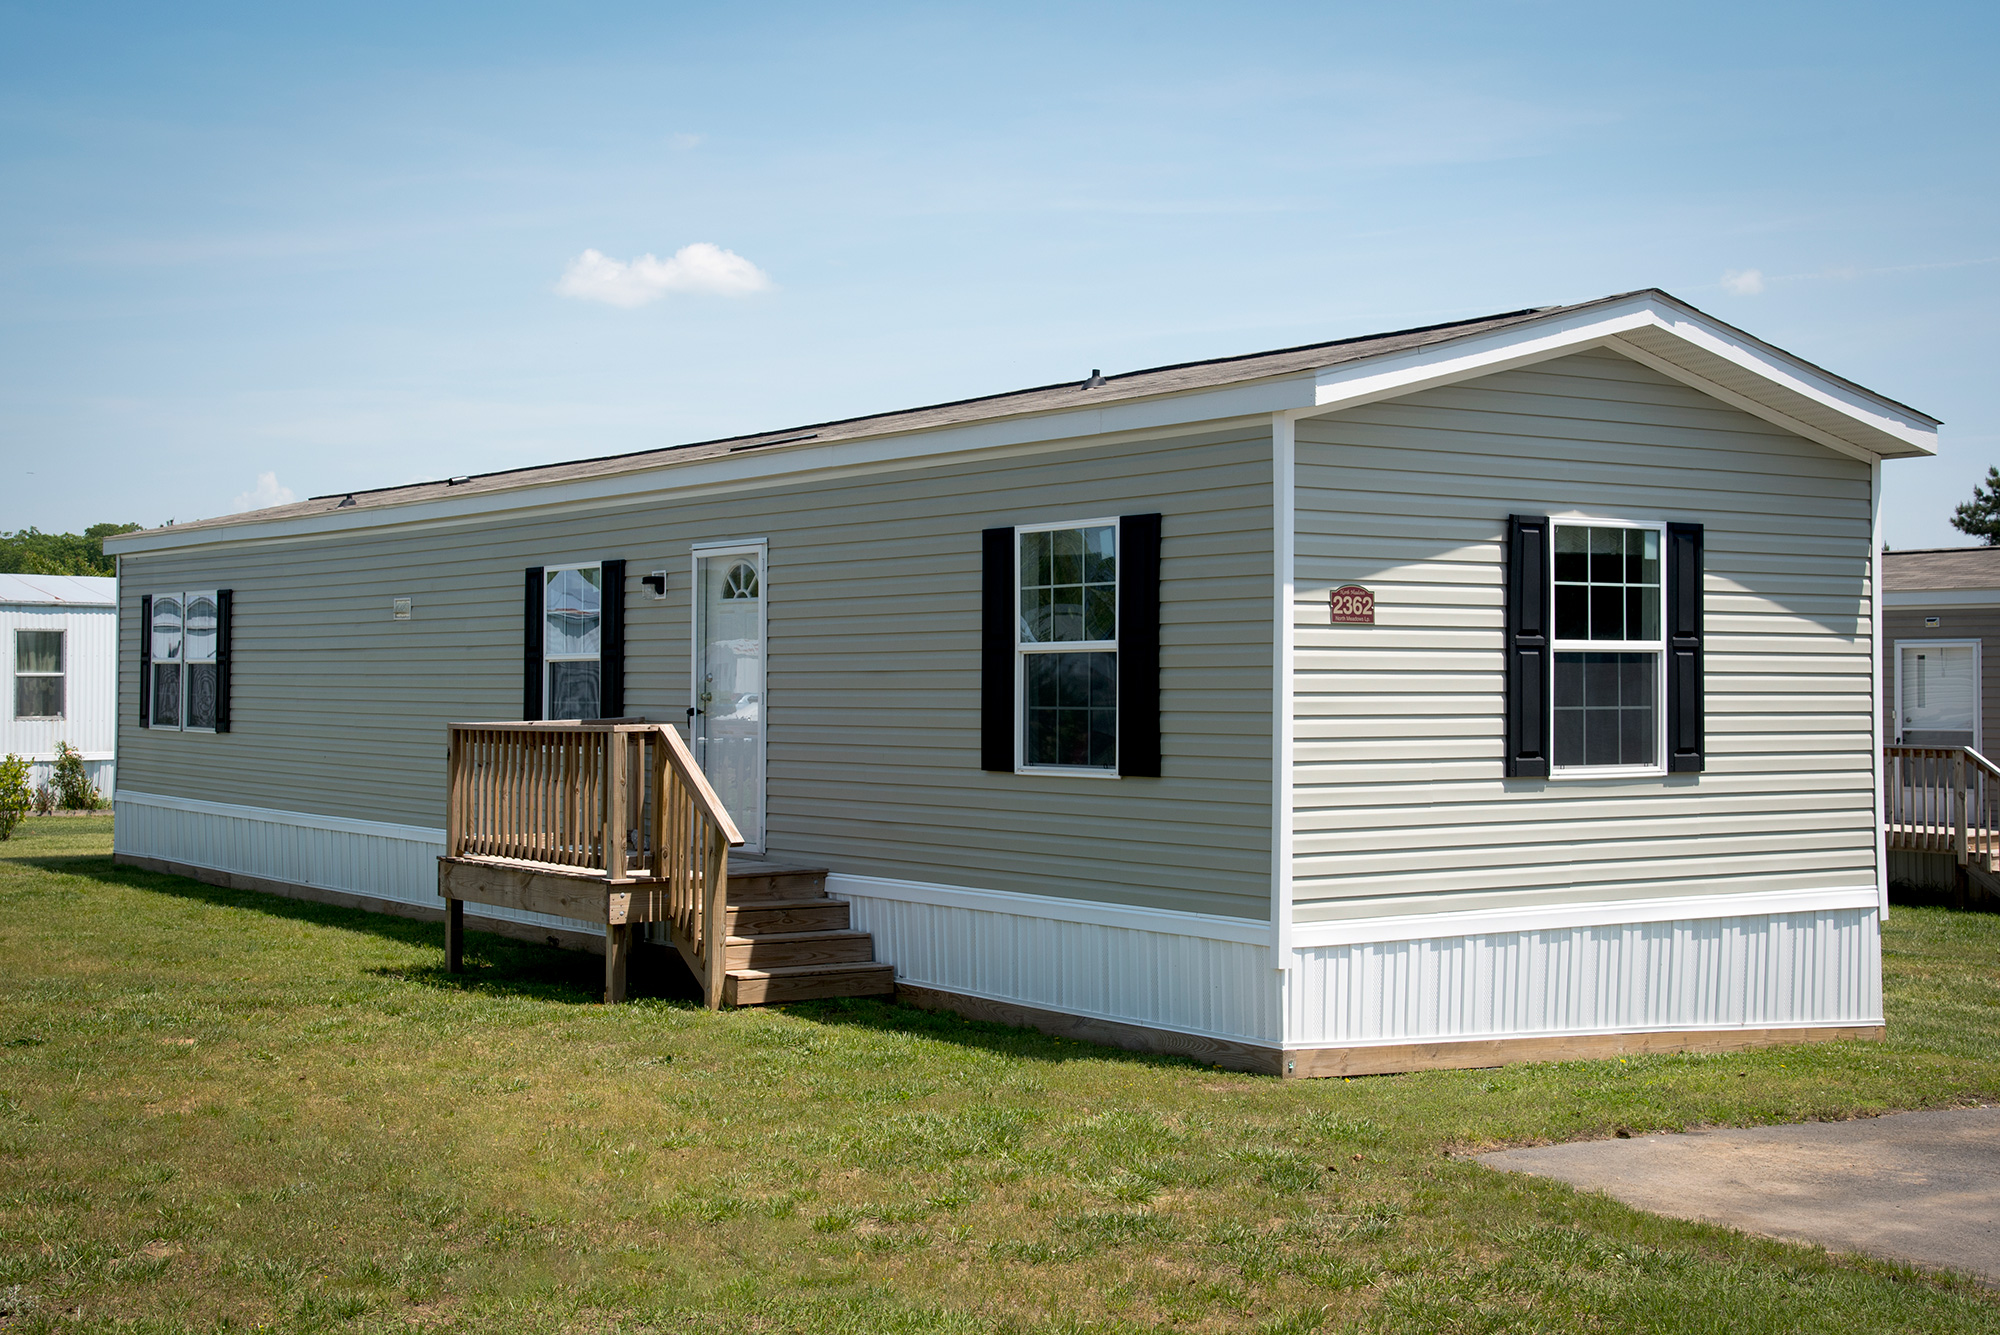
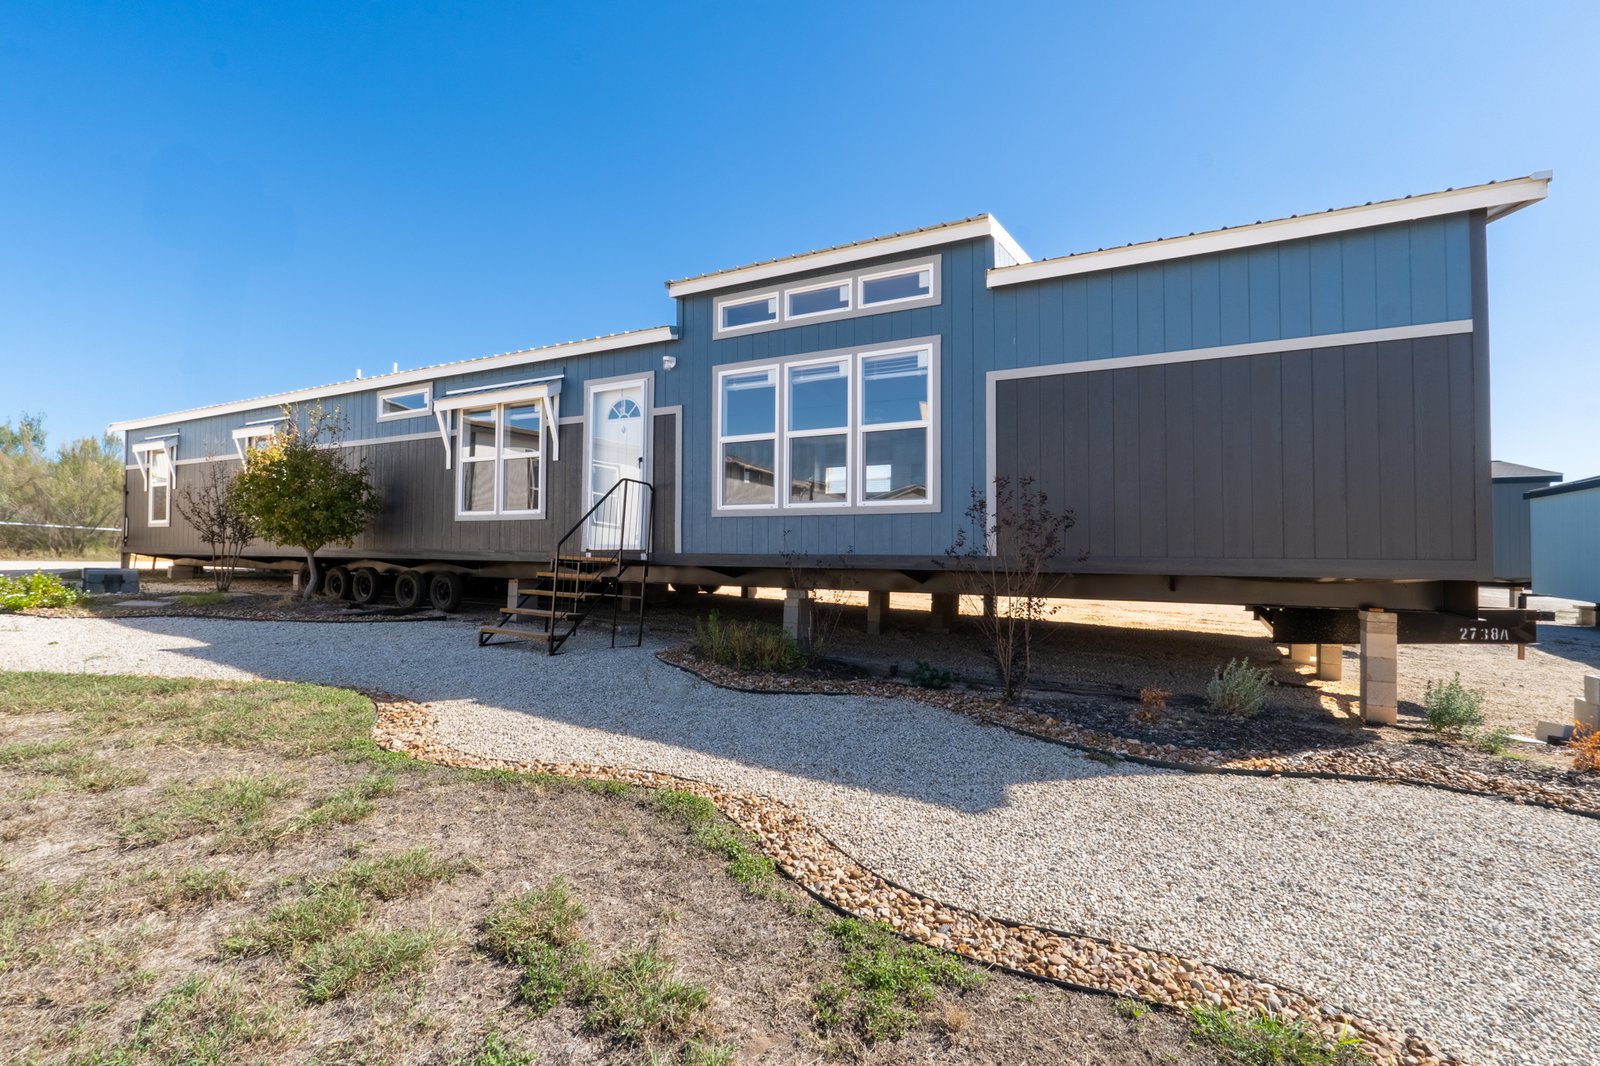
Mobile homes represent a distinct, highly regulated category of factory-built housing that provides an affordable alternative to traditional stick-built real estate. Distinguished from modular housing by their construction on a permanent steel chassis and compliance with federal HUD building codes rather than local building ordinances, these structures offer versatile housing solutions for millions of residents, though buyers must carefully navigate unique financing, zoning, and placement requirements.
Evolution and Definitions: Understanding Factory-Built Housing
The terminology surrounding factory-built housing often causes confusion among prospective buyers, lenders, and local government officials. To navigate the market effectively, one must understand the clear regulatory and historical distinctions between mobile homes, manufactured homes, and modular structures.
The Watershed Year: 1976 and the HUD Code
Prior to June 15, 1976, factory-built residential units were commonly referred to as "mobile homes." These early units faced minimal federal oversight, resulting in widely varying structural integrity, fire safety standards, and energy efficiency.
This landscape changed permanently with the passage of the National Manufactured Housing Construction and Safety Standards Act of 1974, which went into effect on June 15, 1976. Administered by the U.S. Department of Housing and Urban Development (HUD), this legislation established federal construction and safety standards—commonly known as the HUD Code—that superseded state and local building codes for these specific structures.
Consequently, any factory-built home constructed after June 15, 1976, is legally defined as a manufactured home, whereas units built before that date retain the historical designation of "mobile home." Despite this technical distinction, the public and industry participants frequently use the terms interchangeably.
Key Classifications of Factory-Built Structures
To avoid costly mistakes during purchasing and land acquisition, buyers must distinguish among the three primary categories of factory-built homes:
- Manufactured Homes: Built entirely in a controlled factory environment in accordance with the HUD Code. They are constructed on a permanent steel chassis equipped with wheels and axles designed for transportation to a site, whether they are ultimately placed on a rental pad in a land-lease community or permanently affixed to privately owned land.
- Modular Homes: Also constructed in a factory, but built entirely to state and local stick-built building codes (such as the International Residential Code or IRC). Modular homes are transported to a site in sections (modules) and assembled permanently onto a foundation by crane. They are treated legally and financially identical to site-built homes.
- Park Model RVs: These are recreational vehicles built on a single chassis mounted on wheels, certified under ANSI A119.5 standards rather than the HUD Code. They are typically intended for seasonal or temporary lodging rather than permanent residential occupancy, which carries distinct zoning implications.
Construction Specifications and Structural Integrity
Understanding how manufactured homes are engineered helps dispel outdated myths regarding their safety and durability. Modern construction techniques blend assembly-line efficiency with rigorous engineering controls mandated by federal law.
The Permanent Steel Chassis
The foundational backbone of every manufactured home is an integrated structural steel frame. Unlike traditional site-built homes that sit on concrete foundations, a manufactured home is built upon heavy-gauge steel beams running the length of the structure. Cross-members provide lateral support, and outriggers support the exterior walls. This chassis remains an integral part of the home even after it is permanently installed on a foundation, providing the tensile strength necessary to withstand the stresses of transportation and anchoring.
Dimensions and Configurations: Single-Wides vs. Double-Wides
Manufactured homes are categorized primarily by their physical dimensions and number of transportable sections:
- Single-Wide Homes: Constructed as a single unit, typically ranging from 14 to 18 feet in width and 40 to 80 feet in length. They offer a compact footprint, usually containing between 500 and 1,200 square feet of living space, making them ideal for narrow lots or tight community spaces.
- Double-Wide Homes: Composed of two separate transportable sections joined together on-site, spanning 24 feet or more in width. These units provide 1,200 to over 2,000 square feet of living space, closely mirroring the floor plans of traditional ranch-style, stick-built homes.
- Triple-Wide and Multi-Section Homes: Less common, these configurations combine three or more sections to create expansive floor plans exceeding 2,000 square feet, offering architectural complexity and customized layouts.
Materials and Insulation Standards
Under the HUD Code, construction materials must meet stringent performance criteria regarding wind resistance, thermal protection, and fire safety. The code divides the United States into three distinct Wind Zones (Zone I, Zone II, and Zone III). Homes destined for hurricane-prone coastal areas (Zone III) require significantly reinforced roof-framing, enhanced anchoring systems, and impact-resistant exterior wall assemblies compared to units built for inland regions. Similarly, thermal protection standards dictate minimum insulation (R-values) for floors, walls, and roofs based on geographic climate zones.
Placement Options: Land-Lease Communities vs. Private Land
Where a mobile home is placed dictates not only the lifestyle of the resident but also the legal rights, ongoing expenses, and potential for equity appreciation. Buyers generally choose between renting space in a manufactured home community or placing the home on privately owned land.
Manufactured Home Communities (Parks)
Living in a commercial or resident-owned community involves leasing a pad or lot while owning the physical structure itself. This arrangement offers specific financial and operational dynamics:
- Pros: Lower upfront capital requirements (no land purchase necessary), access to shared amenities (playgrounds, clubhouses, pools), and managed infrastructure (road maintenance, community water, and sewer systems).
- Cons: Monthly lot rent payments that are subject to periodic increases, adherence to community rules and regulations regarding pet ownership, exterior modifications, and guest parking, and the risk of community closure or sale of the land.
Placing a Home on Private Land
Purchasing a separate parcel of land and installing a manufactured home provides greater autonomy and stronger potential for real estate appreciation, but introduces complex logistical responsibilities:
- Zoning and Deed Restrictions: Local municipal zoning ordinances frequently restrict where manufactured homes can be placed. Some jurisdictions ban them entirely within city limits, while others require specific agricultural or manufactured-housing zoning designations. Additionally, private subdivisions may enforce Homeowners Association (HOA) covenants or restrictive deeds that prohibit factory-built structures.
- Infrastructure Costs: The buyer is entirely responsible for installing utilities, including drilling a well or connecting to municipal water, installing a septic system or sewer tap, running electrical lines, and grading the driveway.
Financing Mechanisms: Chattel Loans vs. Mortgages
Financing a mobile or manufactured home differs significantly from financing a traditional stick-built house. The primary differentiator is whether the home is classified as personal property (chattel) or real property (real estate).
Chattel Loans
When a manufactured home is placed on rented land in a community, it is legally classified as personal property, much like an automobile or a boat. Buyers secure funding through a chattel loan rather than a traditional mortgage.
- Characteristics: Chattel loans typically feature shorter terms (ranging from 10 to 20 years), higher interest rates compared to conventional real estate mortgages, and fewer statutory consumer protections in the event of default. Because personal property generally depreciates rather than appreciates, lenders view chattel financing as carrying higher risk.
Traditional Real Estate Mortgages
When the manufactured home is permanently affixed to land owned by the homebuyer, and both the home and the land are converted to real property under state law, the owner can secure standard real estate financing.
- Characteristics: Borrowers can access government-backed programs such as FHA Title II (FHA 203(b)), VA loans, and USDA Rural Development loans, alongside conventional mortgages through Fannie Mae (e.g., MH Advantage) and Freddie Mac (e.g., CHOICEREHOME). These programs offer lower interest rates, down payments as low as 3% to 5%, and amortization terms extending up to 30 years.
| Financing Feature | Chattel Loan (Personal Property) | Traditional Mortgage (Real Property) |
|---|---|---|
| Collateral | The physical home only | The home AND the underlying land |
| Land Requirement | Leased land or community pad | Owned land with permanent foundation |
| Typical Term Length | 10 to 20 years | 15 to 30 years |
| Interest Rates | Generally higher (reflecting asset risk) | Competitive with stick-built home rates |
| Loan Programs | Specialized lenders, personal property lenders | FHA, VA, USDA, Conventional (Fannie/Freddie) |
| Legal Conversion | Not required | Requires title elimination/real estate conversion |
Installation, Foundation, and Anchoring Requirements
Proper installation is critical to the structural integrity, safety, and longevity of a manufactured home. Improper setup can lead to shifting floors, leaking roofs, misaligned doors, and catastrophic failure during severe wind events.
Foundation Types
While traditional homes rely on continuous perimeter concrete foundations, manufactured homes utilize several engineered foundation systems:
- Piers and Anchors: The standard setup involves concrete piers (stacked blocks or poured pads) supporting the steel chassis, supplemented by ground anchors and steel strapping to resist high winds. A weather-resistant skirting (vinyl, metal, or masonry) is installed around the perimeter to enclose the crawlspace.
- Permanent Foundations: To qualify for traditional real estate mortgages and maximize property value, the home must be installed on a permanent foundation system, such as a perimeter concrete stem wall, a reinforced concrete slab, or engineered pier systems that meet HUD Permanent Foundation Guide for Manufactured Housing (PFGMH) standards.
The Conversion Process (Titling)
When a manufactured home is transitioned from personal property to real property, the owner must complete a specific legal process governed by state law:
- Surrender the original manufacturer’s certificate of origin or state vehicle titles to the department of motor vehicles or state titling agency.
- Record a real estate affidavit or certificate of permanent location in the local county land records office, legally binding the structure to the real estate parcel.
Comparative Analysis: Manufactured Homes vs. Site-Built Housing
Evaluating manufactured housing against traditional stick-built construction requires weighing initial capital expenditures against long-term asset performance.
[Cost Efficiency] ---> Lower per-square-foot cost due to factory assembly line efficiencies. [Construction Speed] -> Weeks to construct and install, compared to months for stick-built homes. [Appreciation] -----> Historically slower appreciation when placed on leased land; comparable when tied to owned land. [Regulation] -------> Governed by federal HUD code rather than decentralized local building ordinances.
Advantages of Manufactured Housing
- Affordability: The cost per square foot for a manufactured home is frequently 20% to 35% lower than an equivalent site-built home, primarily due to economies of scale in material purchasing and streamlined factory labor.
- Speed of Construction: While weather delays can stall traditional home construction for months, factory construction is completed indoors in a matter of weeks, followed by rapid site placement.
- Quality Control: Controlled factory environments minimize lumber warping caused by weather exposure and ensure rigorous standardized inspections at multiple production stages.
Disadvantages and Limitations
- Stigma and Resale Perception: Outdated stereotypes regarding older mobile homes can impact public perception, affecting market liquidity in certain areas.
- Depreciation on Leased Land: Homes located in land-lease communities generally act as depreciating assets because the owner does not hold equity in the underlying real estate.
- Financing Hurdles: Securing competitive financing for chattel loans can be challenging, requiring higher credit scores or larger down payments.
Frequently Asked Questions
Do mobile homes appreciate in value over time?
Whether a manufactured home appreciates depends entirely on land ownership. When the home is situated on rented land in a community, the physical structure typically depreciates over time much like an automobile, while the land owner retains all real estate equity. Conversely, when a manufactured home is permanently affixed to privately owned land and converted to real property, it historically appreciates at rates comparable to traditional site-built homes in the same geographic market.
Can I place any manufactured home on any piece of land?
No. Local municipal zoning laws dictate whether manufactured homes are permitted in specific areas. Even if municipal zoning allows them, local homeowners associations (HOAs) and deed restrictions in private subdivisions frequently prohibit factory-built housing entirely. Buyers must verify all local ordinances and private covenants before purchasing land for home placement.
What is the difference between a mobile home and a manufactured home?
The difference is strictly legal and chronological. Homes built prior to the implementation of federal HUD safety standards on June 15, 1976, are legally classified as "mobile homes." Units built on or after that date must comply with the federal HUD Code and are officially designated as "manufactured homes."
How are manufactured homes anchored during severe storms?
Manufactured homes use engineered anchoring systems designed to withstand local wind zone requirements. Steel straps are attached to the structural frame and secured to ground anchors (such as auger anchors screwed deep into the earth) or bolted directly into concrete foundations. Skirting is vented to prevent moisture accumulation beneath the chassis while protecting the anchoring components.
What insurance options are available for mobile homes?
Owners can purchase specialized manufactured home insurance policies. If the home is financed via a chattel loan, policies function similarly to renter's or auto insurance combined with property liability. If the home is on owned land with a permanent foundation, coverage closely mirrors standard homeowners insurance (HO-3 or HO-7 forms), protecting against fire, windstorm, theft, and liability.
Next Actions and Practical Recommendations
Prospective buyers and current owners should take a methodical approach to evaluating manufactured housing investments:
- Verify Zoning and Land Rights: Confirm local zoning laws and check for deed restrictions or HOA covenants before purchasing a manufactured home or parcel of land.
- Shop Lenders Carefully: Compare rates between specialized chattel lenders and traditional mortgage brokers offering FHA, VA, or conventional real estate loans tied to land ownership.
- Inspect Installation and Anchoring: Hire a certified independent home inspector specializing in manufactured housing to evaluate the structural stability, skirting, crawlspace ventilation, and anchoring systems prior to finalizing any purchase agreement.