A car payment is the recurring monthly amount a borrower pays to a lender to repay an auto loan, typically consisting of principal and interest. Successfully managing this financial obligation requires a clear understanding of loan amortization, interest calculations, strategic budgeting, and proactive payment options designed to minimize overall borrowing costs.
Managing a monthly vehicle obligation represents one of the most substantial ongoing financial commitments for modern households. Whether financing a brand-new vehicle, purchasing a certified pre-owned car, or refinancing an existing debt, understanding how every dollar is allocated transforms an intimidating bill into a manageable component of personal finance. Mastery of this subject requires looking past the monthly figure advertised by dealerships to evaluate the true total cost of vehicle ownership.
Anatomy of a Monthly Car Payment
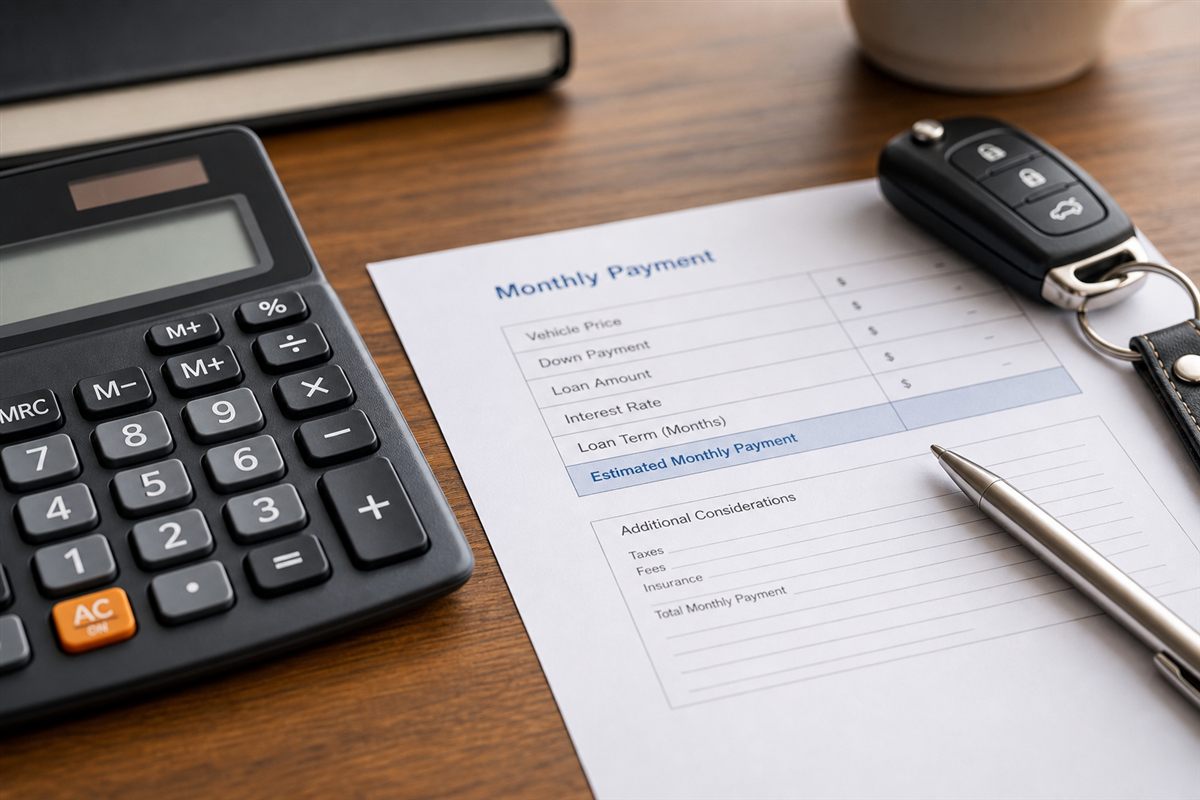
To master an auto loan, borrowers must first deconstruct the exact components that form each monthly transaction. A standard car payment is rarely a flat fee going toward the vehicle's purchase price. Instead, it is a calculated blend of several distinct financial elements managed through an amortization schedule.
Principal Balance
The principal is the original sum of money borrowed from the financial institution to purchase the vehicle, minus any down payment or trade-in value applied at the point of sale. In the early stages of a standard auto loan, a smaller portion of the monthly allocation goes toward reducing this principal balance. As time progresses, the proportion shifts, with more money reducing the principal and less going toward interest.
Interest and the APR
Interest represents the cost of borrowing money, expressed as an Annual Percentage Rate (APR). Lenders calculate monthly interest charges by applying a periodic rate—derived by dividing the annual APR by twelve—to the remaining principal balance. Consequently, as the principal balance decreases over the life of the loan, the absolute dollar amount of interest paid each month also declines, even though the total monthly payment amount remains fixed.
Taxes, Fees, and Optional Add-Ons
Many auto loans roll additional costs directly into the total financed amount. These expenses can include state sales taxes, vehicle registration fees, documentation fees, and optional products like Guaranteed Asset Protection (GAP) insurance or extended service contracts. Financing these items increases the principal balance, which in turn increases the total interest paid over the life of the loan.
Determining Affordability and Budgeting Strategies
Before shopping for a vehicle or signing a financing agreement, establishing a strict budget prevents financial distress. Financial experts and consumer protection organizations consistently emphasize that transportation costs should not overwhelm a household's monthly cash flow.
The 10% and 20% Rules
A widely accepted guideline in personal finance is that total vehicle expenses—including the loan payment, auto insurance, fuel, and routine maintenance—should not exceed 10% to 15% of a borrower's monthly take-home pay. When isolating the car payment alone, many advisors recommend keeping it under 15% to 20% of gross monthly income, though a lower percentage provides a safer financial buffer against unexpected expenses.
Down Payments and Trade-Ins
Providing a substantial down payment reduces the total amount that must be financed, directly lowering both the monthly obligation and the overall interest expense. A larger down payment also mitigates the risk of becoming " upside-down" on the loan—a scenario where the vehicle depreciates faster than the principal is paid down, leaving the borrower owing more than the car is worth.
| Loan Term (Months) | Impact on Monthly Payment | Impact on Total Interest Paid | Risk of Negative Equity |
|---|---|---|---|
| 36 Months | Highest | Lowest | Lowest |
| 48 Months | Moderate | Moderate | Low |
| 60 Months | Moderate-Low | High | Moderate |
| 72+ Months | Lowest | Highest | Highest |
Exploring Auto Loan Structures and Lenders
Borrowers have multiple avenues when securing vehicle financing, and the chosen path dictates the interest rates, terms, and flexibility available during the repayment period.
Traditional Banks and Credit Unions
Securing pre-approval from a bank or credit union before visiting a dealership provides a strong negotiating baseline. Credit unions, in particular, frequently offer competitive interest rates and flexible terms for members, making them an attractive alternative to dealer-sponsored financing.
Dealership Financing and Captive Lenders
Dealerships often partner with captive lenders—financial institutions owned by major automotive manufacturers—to offer specialized promotional programs, such as low-interest or zero-percent financing for well-qualified buyers. While these offers can save money, they often require high credit scores and shorter loan terms, and they may preclude buyers from taking advantage of cash-back rebates.
Loan Terms and Amortization Schedules
Loan lengths have steadily expanded, with 72-month and 84-month terms becoming common. While extended terms lower the immediate monthly payment, they drastically increase the total interest paid and prolong the period of negative equity. Understanding the amortization schedule allows borrowers to see precisely how much equity they hold in the vehicle at any given month.
Strategies for Reducing and Managing Your Payment
If an existing car payment strains monthly finances, several tactical approaches can reduce the financial burden or accelerate debt elimination.
Refinancing the Loan
If market interest rates have dropped, or if the borrower's credit score has improved significantly since the original purchase, refinancing the auto loan can secure a lower interest rate. Borrowers can also refinance to extend the loan term, lowering the monthly payment, though this may increase the total interest paid over the life of the loan.
Making Principal-Only Payments
Most standard auto loan agreements allow borrowers to make extra payments toward the principal balance without incurring prepayment penalties. Designating extra funds explicitly as "principal-only" accelerates the amortization schedule, reduces the total interest accrued, and shortens the time required to fully pay off the vehicle.
Communication with Lenders
If a temporary financial hardship threatens a borrower's ability to make their monthly payment, contacting the lender immediately is crucial. Many financial institutions offer hardship programs, payment deferrals, or temporary modifications to help consumers avoid default and protect their credit scores.
Frequently Asked Questions
What happens if I miss a car payment?
Missing a car payment can result in late fees, negative reporting to major credit bureaus after 30 days, and potential repossession of the vehicle. Lenders typically initiate recovery procedures if payments fall significantly behind, which severely damages the borrower's credit score and impacts future borrowing ability.
Can I pay off my car loan early?
Most auto loans do not carry prepayment penalties, meaning you can pay off the balance early to save on interest. However, borrowers should verify their specific loan agreement terms and ensure any extra funds are applied directly to the principal rather than advanced interest.
How does my credit score affect my car payment?
A higher credit score demonstrates lower risk to lenders, qualifying the borrower for lower interest rates and more favorable loan terms. A lower interest rate directly decreases the monthly payment amount and reduces the total cost of financing the vehicle.
Is it better to put down cash or finance the entire amount?
Putting down cash reduces the total loan amount, lowers the monthly payment, and minimizes total interest charges. Financing the entire amount preserves cash liquidity for emergencies, but it increases monthly obligations and total borrowing costs.
What is vehicle refinancing?
Refinancing involves replacing your current auto loan with a new loan, typically from a different lender, featuring new terms and interest rates. It is commonly used to secure lower monthly payments, reduce interest rates, or adjust the repayment timeline.
Next Steps for Managing Your Auto Financing
Reviewing your current loan agreement is the essential first step toward optimizing your financial position. Locate your most recent billing statement to verify your current interest rate, remaining principal balance, and scheduled payoff date. If your credit score has improved or market rates have shifted, research local credit unions or online lenders to evaluate potential refinancing offers. For those struggling with cash flow, contact your current lender proactively to discuss hardship options before missing a payment deadline.