A one-time payment is a single, non-recurring financial transaction used to settle the cost of a product, service, or obligation in full. Unlike subscription models or installment plans, a one-time payment eliminates future financial commitments, simplifies accounting for the payee, and provides immediate ownership or fulfillment. As of 2026, businesses and consumers increasingly weigh these payments against recurring models to manage cash flow and asset lifecycle costs.
The Concept and Economic Mechanics of One-Time Payments
At its core, a one-time payment represents the total value exchange between a buyer and a seller at the point of transaction. This model is foundational in retail, real estate, and capital goods procurement. By paying the full amount upfront, the payer satisfies their liability entirely.
From a merchant’s perspective, receiving a one-time payment reduces the risk of payment default and minimizes administrative overhead associated with managing billing cycles, dunning processes, and recurring invoice generation. For the consumer, this model often unlocks discounts—frequently referred to as "paid-in-full" incentives—as the merchant gains the advantage of immediate liquidity.
However, the economic feasibility depends on the nature of the asset. For perishable goods or transient services, the one-time payment is the standard. For software or long-term utility services, the shift toward "Software as a Service" (SaaS) subscription models has made the one-time perpetual license—a form of one-time payment—a specialized offering.
Comparative Framework: One-Time Payments vs. Recurring Models
Understanding when to choose a one-time payment requires an analysis of opportunity cost and long-term utility. The following table compares the two primary payment architectures found in 2026 market environments.
| Feature | One-Time Payment | Recurring Subscription |
|---|---|---|
| Cash Flow Impact | Significant initial outflow | Low, predictable periodic outflow |
| Long-Term Cost | Often lower total cost of ownership | Usually higher cumulative cost |
| Ownership Status | Immediate and permanent | Conditional; access ends if payment stops |
| Maintenance | Typically user-managed or limited | Often includes updates and support |
| Administrative Burden | Minimal; no ongoing billing cycles | High; requires active billing management |
Benefits of Choosing One-Time Payments
Eliminating Future Financial Obligations
The primary benefit of a one-time payment is the removal of future debt or liability. Once the transaction is processed and confirmed, the user is not required to worry about future price increases, changes in merchant billing policies, or service interruptions due to missed payments. This provides psychological and financial security, particularly for high-value assets where long-term ownership is the objective.
Cost Efficiency Over Time
While the upfront cost is higher, the total cost of ownership (TCO) is almost invariably lower with a one-time payment. Subscription models are designed to maximize lifetime value (LTV) for the merchant, which often results in a consumer paying significantly more over a three-to-five-year period than they would have with an upfront purchase.
Data Privacy and Security
Recurring billing requires storing payment credentials—such as credit card numbers or bank account details—in a merchant’s digital vault. Each storage point increases the surface area for potential data breaches. With a one-time payment, the interaction is singular. Once the transaction is cleared, the requirement for the merchant to maintain sensitive payment tokens is reduced or eliminated, depending on regional data retention regulations.
Challenges and Operational Considerations
Capital Allocation Risks
The most significant barrier to a one-time payment is the "liquidity constraint." For businesses or households with tight budgets, tying up capital in a single, large-scale payment reduces the ability to deploy that cash for other immediate needs. This is why credit-based financing or leasing remains prevalent, even when one-time payments are mathematically cheaper in the long run.
Maintenance and Obsolescence
When a product is purchased via a one-time payment—specifically in software or technology—the user often assumes the risk of product obsolescence. If the vendor updates the product, the one-time purchaser may be forced to buy a new version (a "version upgrade") rather than receiving continuous updates as a subscriber would. This requires a careful evaluation of the product lifecycle before committing to a one-time transaction.
Verification and Security Procedures
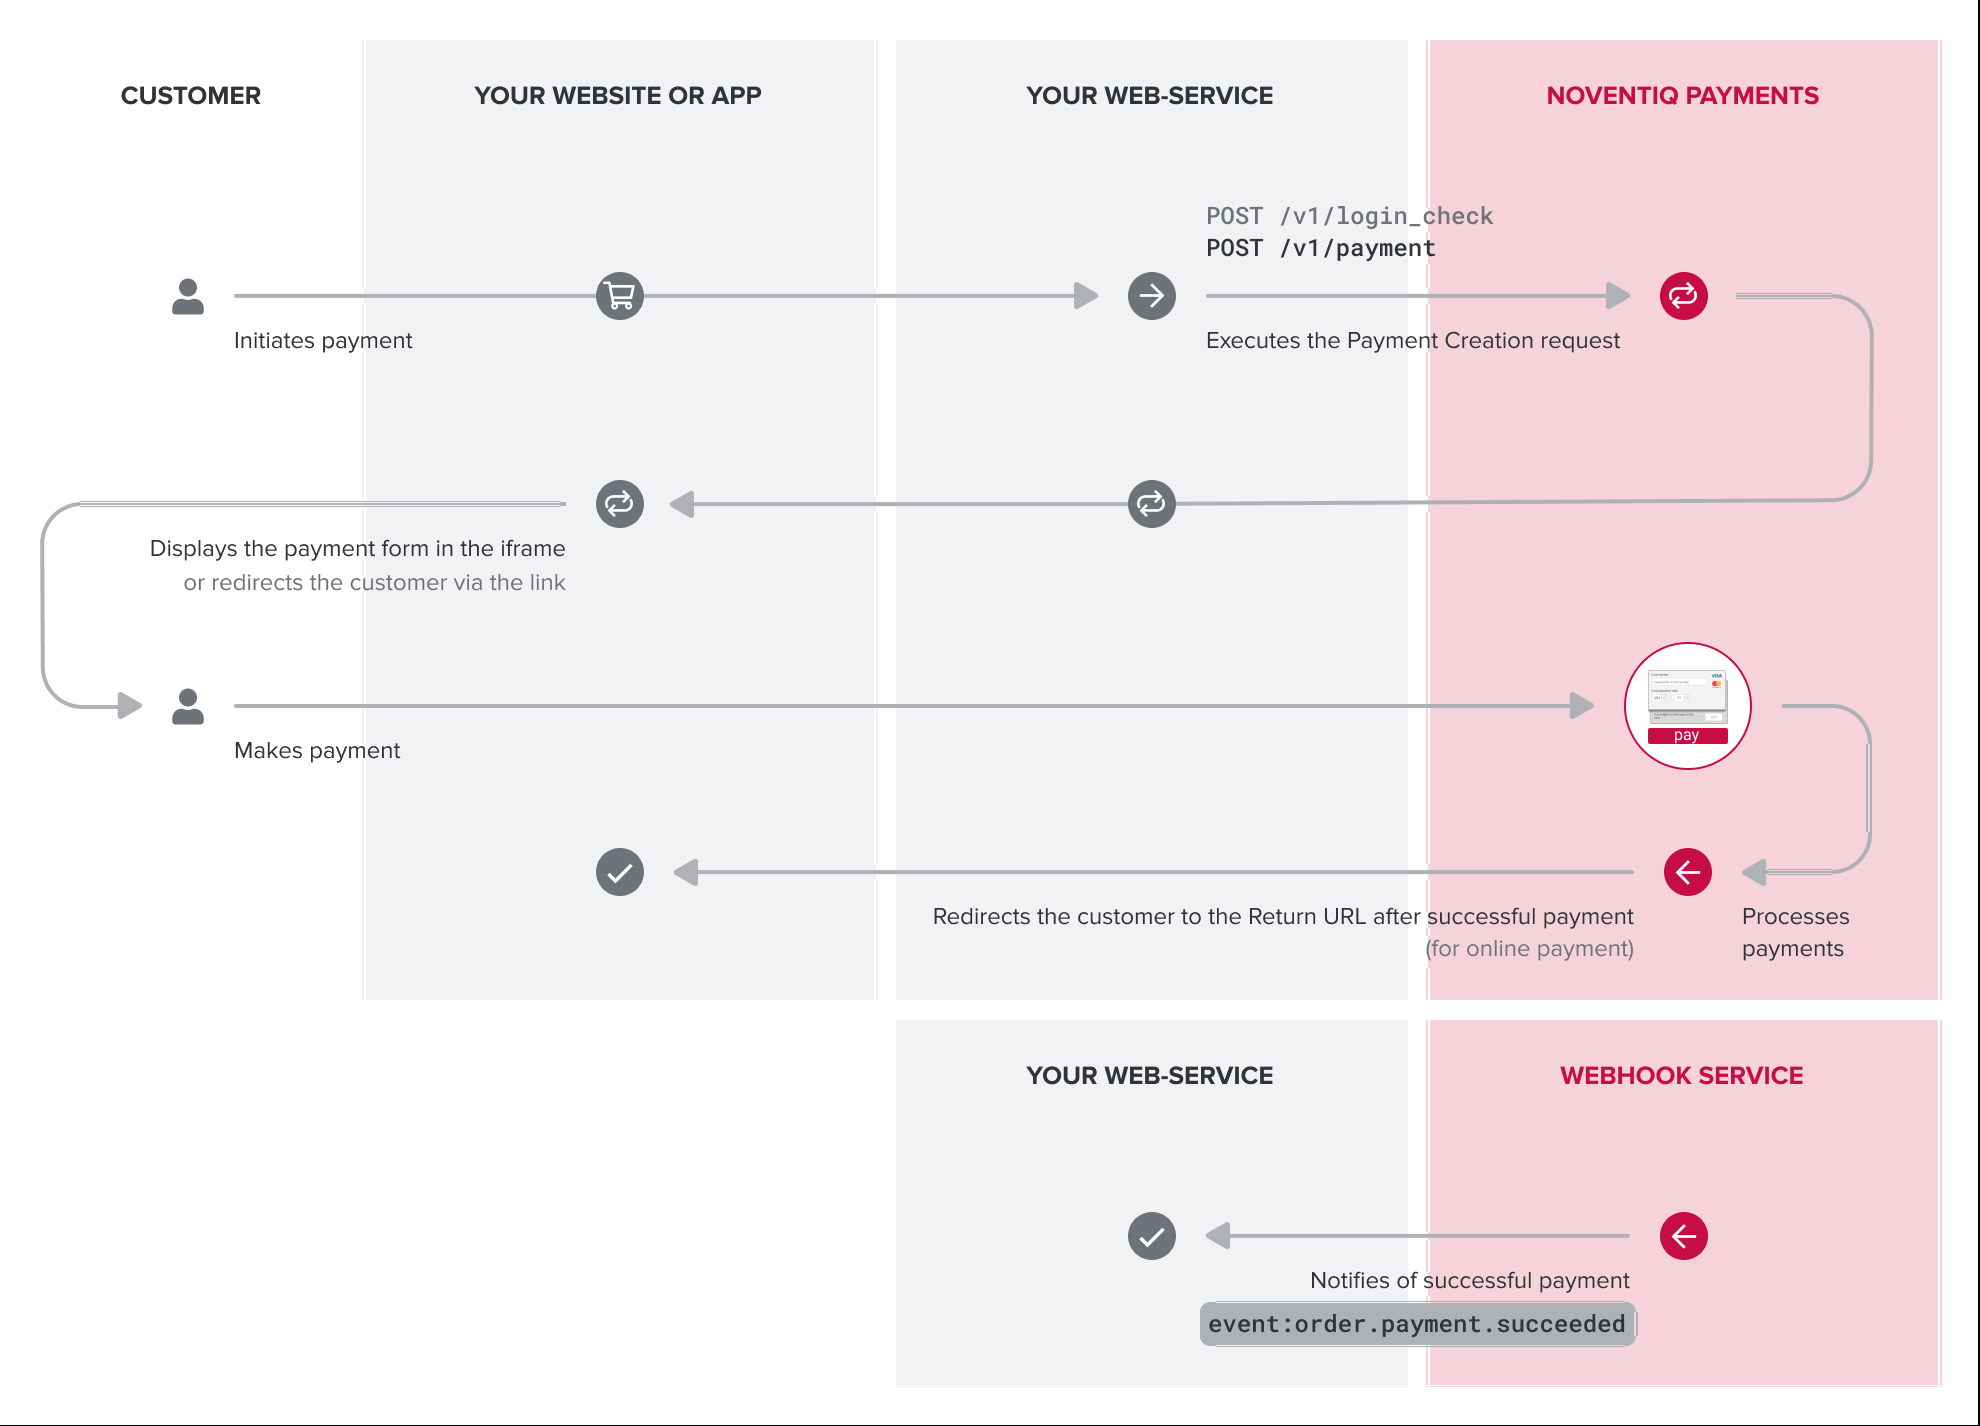
Executing a secure one-time payment involves several layers of verification. In 2026, the standard for secure transactions relies on Payment Card Industry Data Security Standard (PCI DSS) compliance and multi-factor authentication (MFA).
- Authentication: The buyer authenticates their identity through the payment gateway, typically using biometrics or one-time passcodes (OTP) sent to a registered device.
- Authorization: The payment processor verifies that the funds or credit limit exist.
- Settlement: The funds are transferred from the issuer to the merchant’s acquiring bank.
- Receipting: A permanent record of the transaction is generated. This is critical for tax purposes, as a one-time payment must be substantiated as a capital expense or full settlement of an invoice.
Users should always verify the legal receipt provided after a one-time payment. This document acts as the primary evidence of ownership and should state clearly that no further payments are due.
Troubleshooting Common Issues
Payment Declines
A one-time payment of a large amount may be flagged by automated fraud detection systems. If a transaction fails, it is often due to a "velocity limit" or an unusual spending pattern detected by the bank. To resolve this, contact the issuing financial institution before attempting the payment again.
Dispute Resolution
If a product or service was paid for via a one-time transaction and was not delivered as described, the buyer has a window of time—typically dictated by the bank’s policies—to file a chargeback. Unlike subscriptions, where disputes can be complex due to multiple transaction dates, a one-time payment is usually straightforward to identify and contest if the merchant failed to meet their contractual obligations.
Accounting Discrepancies
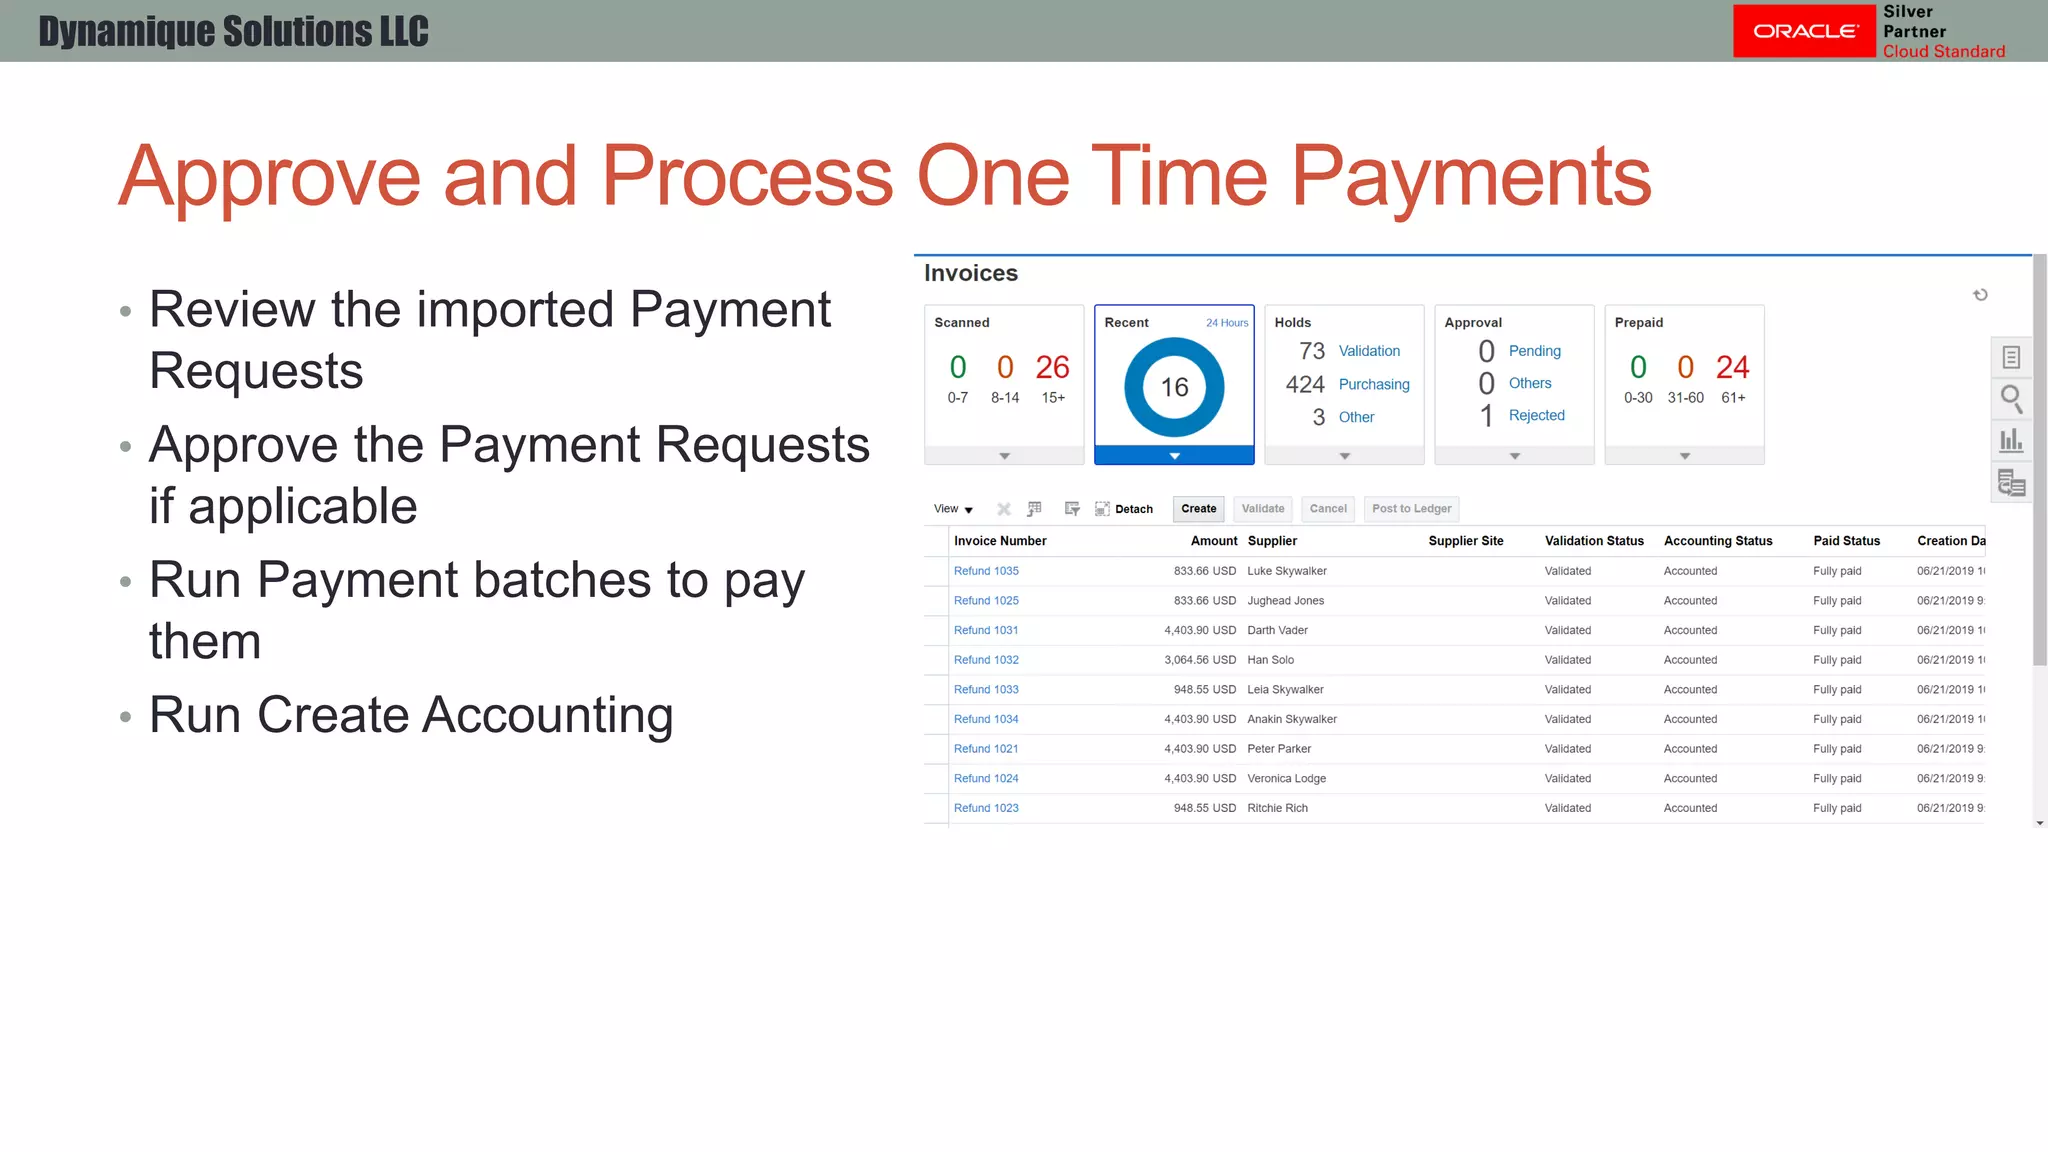
For businesses, a one-time payment must be accurately categorized in the ledger. If an invoice remains "open" in a merchant’s accounting system despite payment, request an updated statement marked "Paid in Full." Relying on bank statements alone can be insufficient for audits, as they often lack the specific SKU or invoice reference numbers required to reconcile the expense.
Frequently Asked Questions
Is a one-time payment always cheaper than a subscription?
Yes, in terms of the total cost of ownership over the lifespan of the product. While subscriptions offer lower entry costs, they rarely offer a "break-even" point that favors the consumer over the long term. If you intend to use a tool for more than two years, a one-time payment is mathematically superior in most cases.
Can I get a refund on a one-time payment?
Refund eligibility is governed by the specific terms of service of the merchant and local consumer protection laws. Most one-time payments are refundable within a specific window (e.g., 30 days), provided the product has not been consumed or irreversibly activated. Always review the merchant’s cancellation policy before clicking "Pay."
Does a one-time payment affect my credit score?
No. A standard one-time payment made with a debit card or existing funds has no impact on your credit score. If the one-time payment is made using a credit card, it may impact your credit utilization ratio, which can indirectly affect your score. However, it does not involve the credit-building or reporting cycle associated with installment loans.
What should I look for in a payment gateway during a one-time transaction?
Look for "HTTPS" in the browser address bar and a verified security seal from a trusted provider like Stripe, PayPal, or a major banking institution. Ensure the payment page is not a redirect to a suspicious third-party site. If in doubt, verify the payment link via the company’s official, established website.
Can I be forced into a subscription after a one-time payment?
In many jurisdictions, businesses are legally required to obtain separate, explicit consent before enrolling a customer in a recurring billing cycle. If you paid via a one-time purchase button, you should not be automatically enrolled in a subscription. If this occurs, it constitutes a "dark pattern" and is a valid reason for a regulatory complaint or bank-initiated dispute.
Recommendation for Execution
Before committing to a one-time payment, perform a "utility assessment." Ask yourself if the product or service will remain relevant to your needs for at least 24 months. If the answer is yes, prioritize the one-time payment to avoid the "subscription creep" that characterizes 2026 digital spending. Ensure you retain the digital or paper receipt in a secure, backed-up location, as this serves as your sole proof of permanent entitlement to the purchase. If you are a business buyer, ensure your accounts payable department classifies the expense as a non-recurring capital event to prevent future reconciliation errors.