Navigating New Jersey insurance requirements involves understanding mandatory minimum coverage limits for auto and health policies, navigating state-specific regulations administered by the Department of Banking and Insurance (DOBI), and selecting appropriate optional protections like homeowners and umbrella insurance to safeguard personal assets.
Securing the right insurance policy in New Jersey requires a clear understanding of state mandates, financial thresholds, and regulatory protections. Whether you are registering a vehicle, purchasing a home, or evaluating healthcare options, the New Jersey insurance landscape is governed by specific state laws designed to protect consumers while holding policyholders to strict compliance standards. This comprehensive guide explores the core categories of insurance in New Jersey, outlines mandatory coverage levels, and provides actionable steps for evaluating, purchasing, and managing your policies effectively.
The New Jersey Insurance Regulatory Landscape
Insurance products in New Jersey are strictly regulated to ensure carrier solvency, fair pricing, and consumer protection. The primary regulatory body overseeing all insurance sectors in the state is the New Jersey Department of Banking and Insurance (DOBI). DOBI oversees licensing for insurance producers, reviews and approves rate filings, and investigates consumer complaints against carriers.
State oversight directly impacts how policies are structured, priced, and renewed. For consumers, understanding that DOBI enforces consumer protection laws means you have recourse if a claim is improperly denied or if premium increases violate state guidelines. Working with licensed New Jersey insurance brokers or captive agents ensures that the policies you purchase comply with statutory requirements rather than out-of-state templates that may fail to meet local legal standards.
New Jersey Auto Insurance Requirements
Automobile insurance is one of the most heavily regulated and frequently purchased insurance products in the state. New Jersey is a "Choice No-Fault" state, which means drivers select how their medical bills and lawsuits are handled after an accident. Understanding the nuances of New Jersey auto insurance requires looking closely at mandatory coverage types, the distinction between standard and basic policies, and the implications of the verbal threshold.
Mandatory Coverage Types and Minimum Limits
Every registered vehicle in New Jersey must carry active liability and personal injury protection insurance. Driving without valid insurance can result in severe penalties, including fines, community service, and suspension of driving privileges.
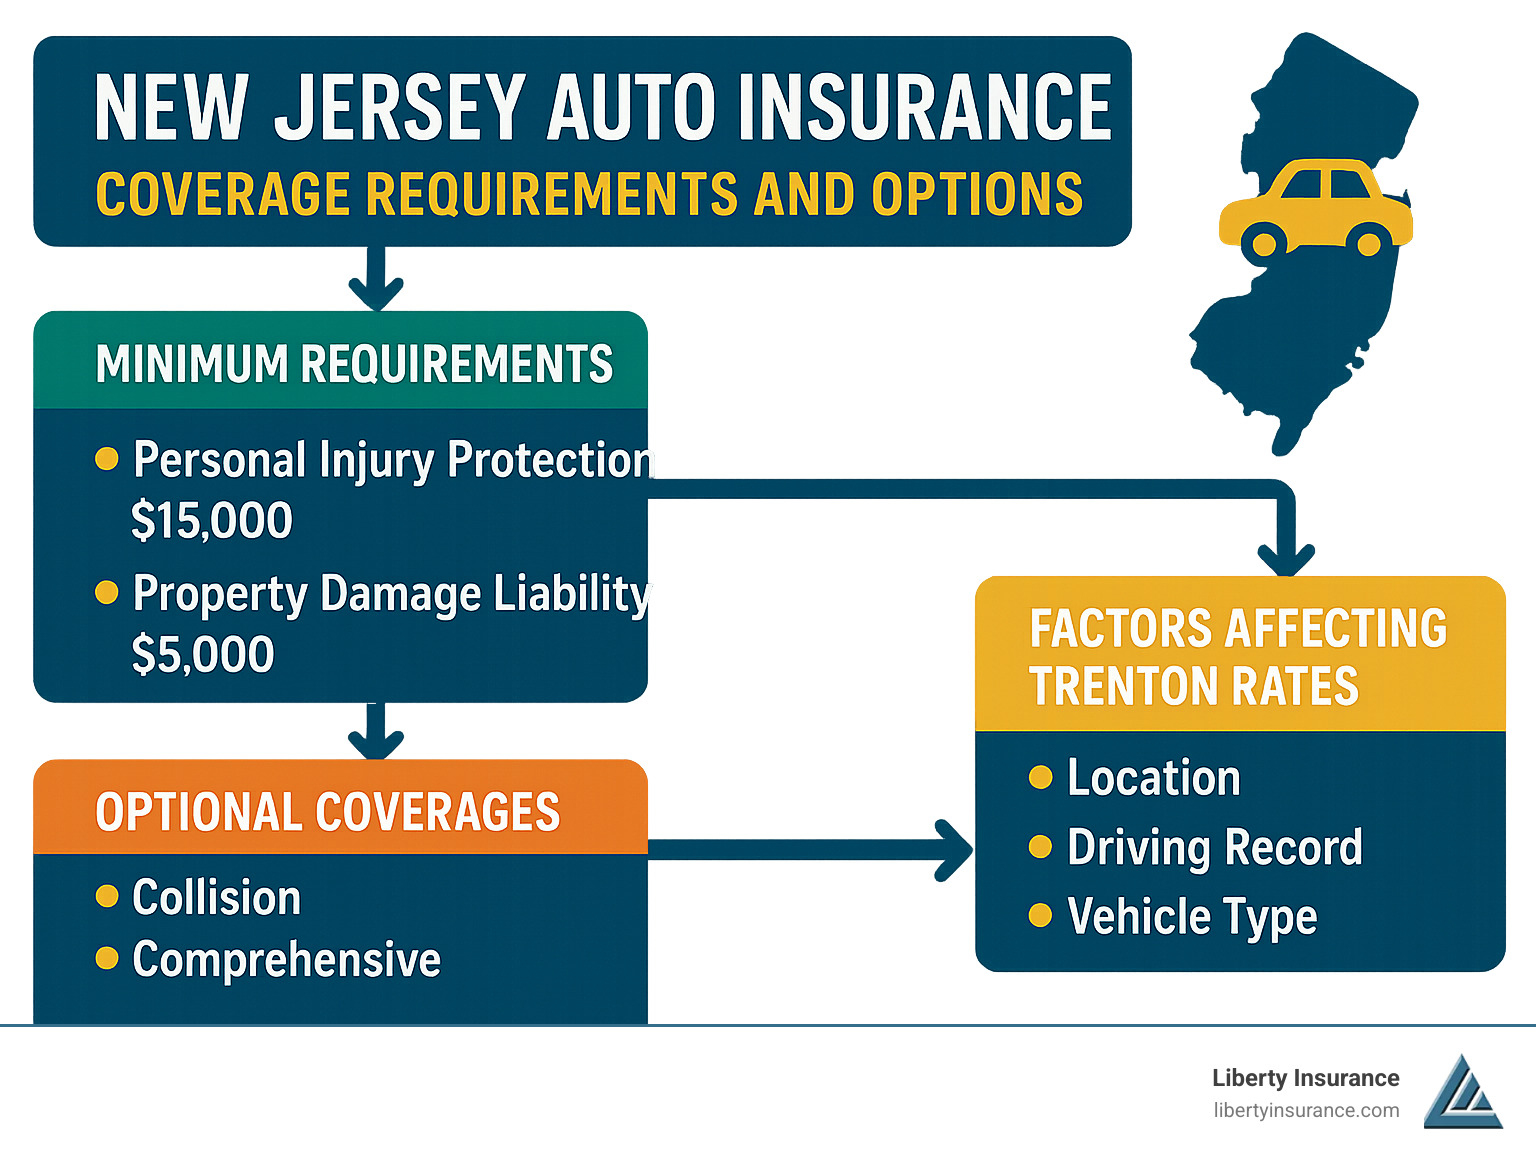
- Liability Coverage: Pays for injuries and property damage you cause to others. New Jersey requires minimum limits of $25,000 for bodily injury per person, $50,000 for bodily injury per accident, and $25,000 for property damage per accident (often written as 25/50/25).
- Personal Injury Protection (PIP): Covers medical expenses for you and your passengers injured in an accident, regardless of who is at fault. New Jersey mandates a minimum PIP limit of $15,000, though higher limits up to $250,000 are available and recommended to cover catastrophic medical bills.
- Uninsured/Underinsured Motorist (UM/UIM) Coverage: Protects you if you are hit by a driver who has no insurance or insufficient limits to cover your damages. While often bundled, it is vital to match your UM/UIM limits to your liability limits.
Standard Policy vs. Basic Policy
New Jersey offers two primary types of auto insurance policies to accommodate different financial situations:
| Feature | Basic Policy | Standard Policy |
|---|---|---|
| Target Audience | Budget-conscious drivers with minimal assets. | Drivers seeking comprehensive asset protection. |
| Liability Limits | Very low ($10,000 property damage; bodily injury is typically not included unless added via optional endorsement). | Higher limits available ($25/50/25 up to $250/500/100 or higher). |
| PIP Medical Coverage | $15,000 standard (can be up to $250,000 for certain catastrophic injuries). | Up to $250,000 in comprehensive medical expense benefits. |
| Lawsuit Limitation | Applies the limitation on lawsuit threshold automatically. | Allows choice between lawsuit limitation and zero threshold. |
The Limitation on Lawsuit Option (Verbal Threshold)
When purchasing a New Jersey auto policy, you must choose between the "Limitation on Lawsuit" (often called the verbal threshold) and the "No Limitation" (zero threshold) option. Choosing the limitation on lawsuit saves money on premiums, but it restricts your right to sue an at-fault driver for non-economic damages (pain and suffering) unless the injury falls into one of six specific statutory categories, such as death, dismemberment, or significant disfigurement. Opting for no limitation allows you to sue for any injury, but results in a higher premium.
Homeowners and Property Insurance in New Jersey
Homeownership in New Jersey comes with unique property risks, ranging from severe coastal nor'easters and winter blizzards to inland flooding and high winds. Standard homeowners insurance (HO-3 policies) covers your dwelling, personal property, and personal liability, but policyholders must pay close attention to specific exclusions.
Coastal Risks and Windstorm Deductibles
Properties located in coastal counties or near tidal waters often face specialized underwriting rules. Many insurance carriers in New Jersey utilize separate, higher percentage deductibles for windstorm or hurricane damage—ranging from 1% to 5% of the home's insured value—rather than a flat dollar deductible like $1,000 or $2,500. Reviewing your policy's declarations page for windstorm and named-storm clauses is essential to avoiding unexpected out-of-pocket costs after a storm.
Flood Insurance Realities
Standard homeowners insurance policies explicitly exclude flood damage. Because New Jersey features extensive coastline, river basins, and low-lying inland areas, many homeowners are vulnerable to rising water from heavy rains or storm surges. Flood insurance is typically purchased separately through the National Flood Insurance Program (NFIP) or private surplus lines carriers. Mortgage lenders will mandate flood insurance if your property sits within a designated Special Flood Hazard Area (SFHA).
Health Insurance Options in New Jersey
Healthcare coverage in New Jersey is governed by both federal Affordable Care Act (ACA) guidelines and state-level mandates. The state operates its own health insurance exchange, Get Covered New Jersey, which provides access to individual and family health plans with potential state and federal subsidies.
- Individual Mandate: New Jersey enforces an individual health insurance mandate. Residents must maintain minimum essential health coverage or pay a state shared responsibility payment when filing state income taxes, unless they qualify for an exemption.
- Plan Tiers: Plans on the exchange are organized into metal tiers (Bronze, Silver, Gold, Platinum) based on how you and the plan share costs. Silver and Gold plans are popular choices for balancing monthly premiums with out-of-pocket medical expenses.
Life and Disability Insurance Considerations
Financial planning in New Jersey often incorporates life and disability insurance to protect dependents and income streams against unforeseen events.
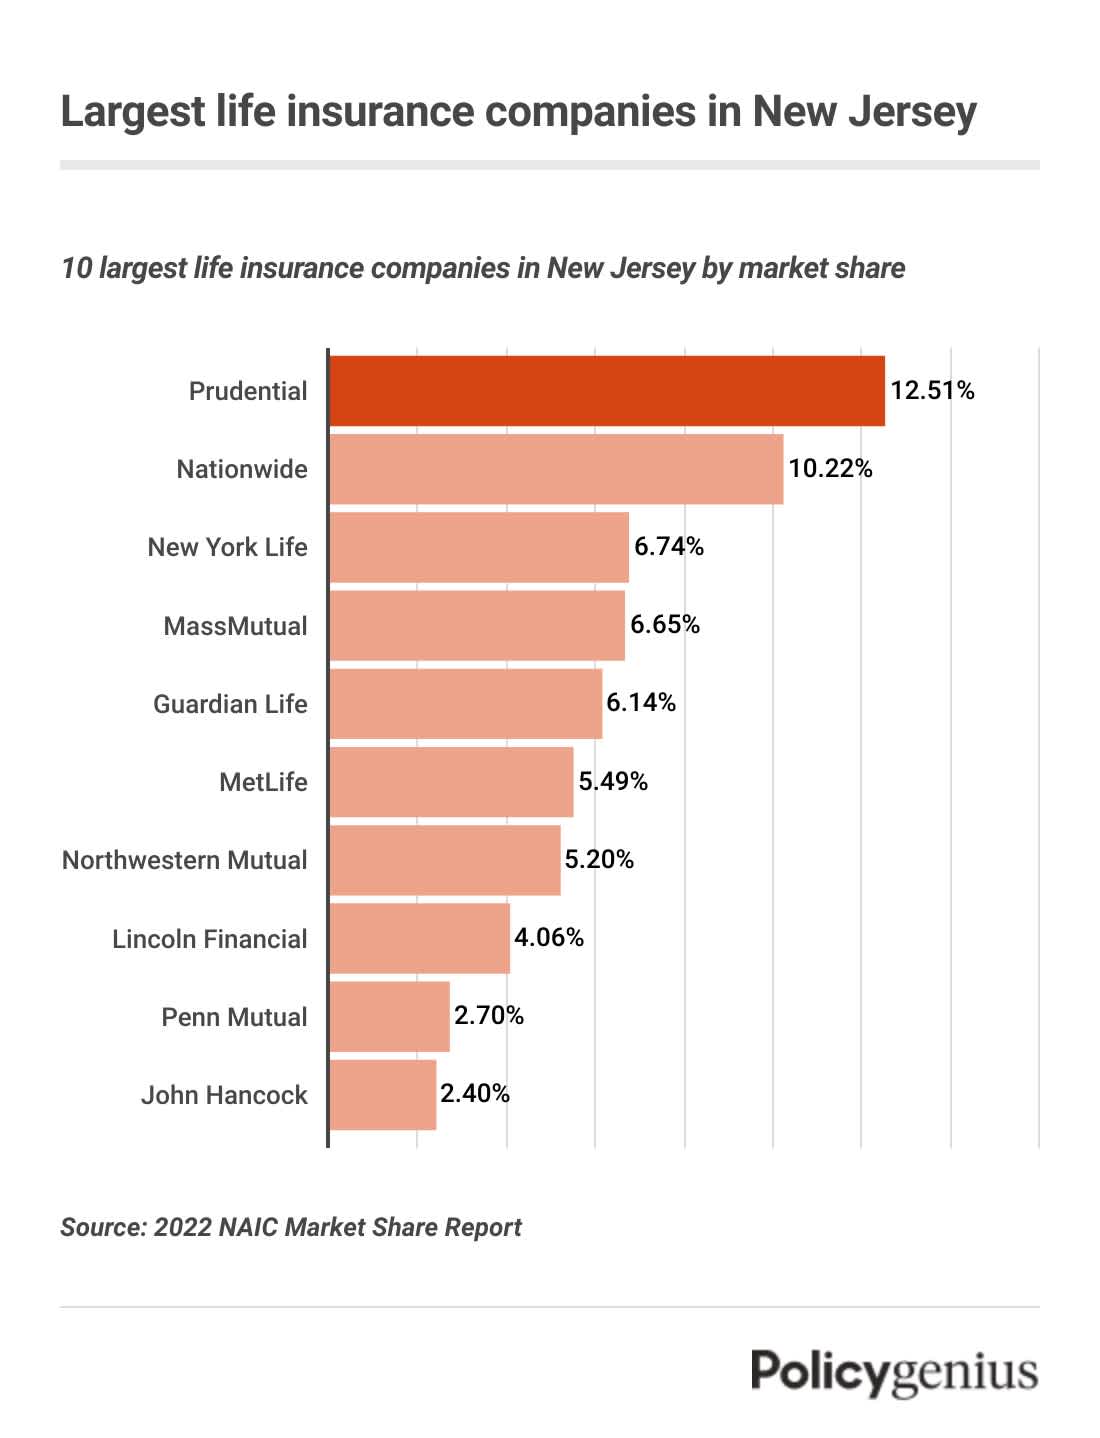
- Life Insurance: Consumers choose primarily between term life insurance (providing pure death benefit protection for a set number of years) and permanent life insurance (such as whole or universal life, which includes a cash-value component). New Jersey residents benefit from statutory grace periods and policy loan regulations enforced by DOBI.
- State Disability Benefits: New Jersey operates a state-administered Temporary Disability Insurance (TDI) program funded through payroll deductions shared by employers and employees. This program provides partial wage replacement if you cannot work due to a non-work-related illness, injury, or pregnancy. Workers can also access Family Leave Insurance (FLI) to bond with a new child or care for a seriously ill family member.
How to Compare and Purchase Insurance Policies
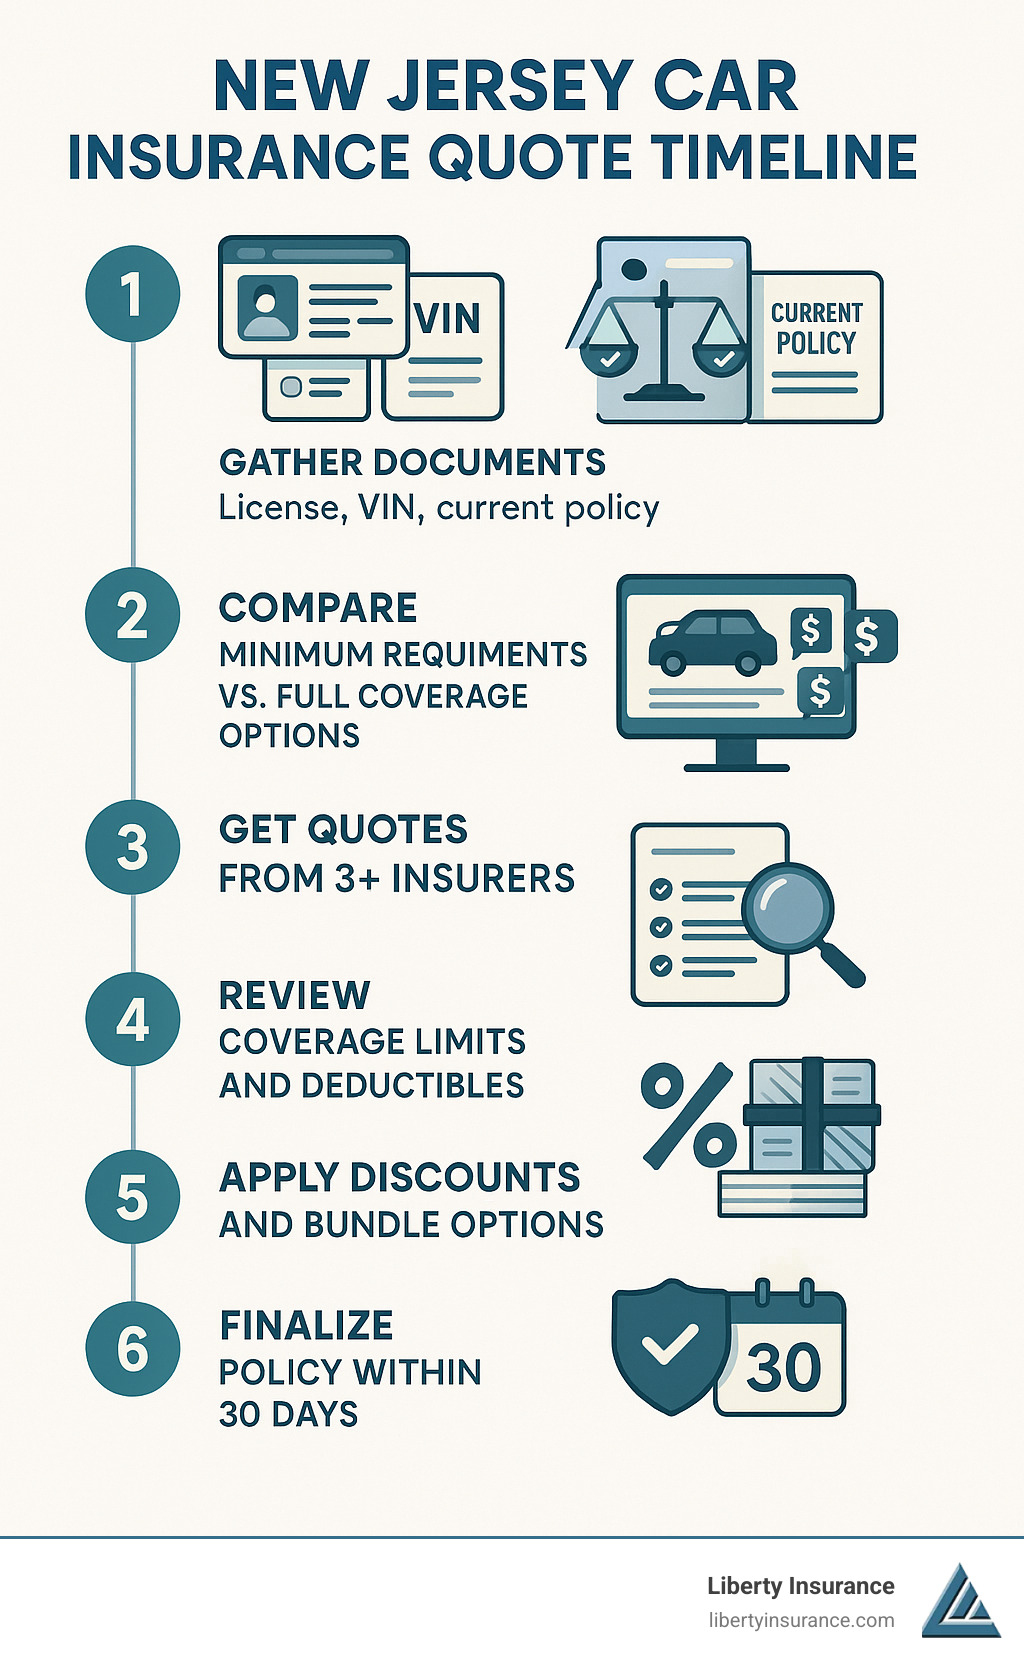
Selecting the right coverage requires a systematic evaluation of your financial risk tolerance, asset portfolio, and statutory obligations. Follow these steps when shopping for insurance in New Jersey:
- Audit Your Assets: Calculate your net worth, home equity, and future earnings potential to determine appropriate liability limits. Relying solely on state minimums leaves personal assets vulnerable to excess judgments in a lawsuit.
- Gather Quotations: Obtain quotes from multiple carriers. You can work directly with independent insurance agents who represent multiple insurance companies, or utilize direct-to-consumer online platforms.
- Check Carrier Licensing: Verify that the insurance company and the agent or broker are licensed to operate in New Jersey by searching the DOBI online license lookup tool.
- Evaluate Deductibles and Riders: Balance monthly premium costs against out-of-pocket exposure by selecting deductibles you can comfortably afford in an emergency. Add endorsements for scheduled personal property (jewelry, art) or umbrella liability if necessary.
- Review Annually: Life events—such as moving, purchasing a vehicle, remodeling a home, or changing jobs—directly alter your insurance needs. Review your policy portfolio at least once a year.
Frequently Asked Questions About NJ Insurance
Is car insurance mandatory in New Jersey?
Yes. Every registered vehicle in New Jersey must maintain continuous liability insurance, personal injury protection (PIP), and uninsured/underinsured motorist coverage. Operating a vehicle without valid insurance can lead to heavy fines, license suspension, and surcharges.
What is the difference between New Jersey's basic and standard auto policy?
A basic policy offers lower premium costs with minimal liability limits ($10,000 property damage) and restricted bodily injury coverage. A standard policy provides comprehensive liability limits, flexible medical payment options through PIP, and customizable lawsuit thresholds tailored for asset protection.
Does standard homeowners insurance cover flood damage in New Jersey?
No. Standard homeowners policies explicitly exclude damage caused by rising surface water, storm surges, or overflowing bodies of water. Homeowners must purchase a separate flood insurance policy through the National Flood Insurance Program or a private insurer.
How does New Jersey's health insurance mandate work?
New Jersey requires all residents to maintain qualifying health insurance coverage throughout the year. If you go without coverage and do not qualify for a statutory exemption, you will be assessed a shared responsibility payment when filing your New Jersey state income tax return.
Can I buy insurance directly from out-of-state companies?
Insurance companies must be authorized and licensed by the New Jersey Department of Banking and Insurance to sell policies within the state. Purchasing coverage from an unauthorized carrier leaves you unprotected and violates state regulatory statutes.
Next Actions
To ensure you are properly protected under New Jersey law, pull your current auto, home, and health insurance policy declarations pages. Compare your current liability limits and deductibles against your personal asset exposure. If you find gaps—such as carrying only basic auto liability or lacking umbrella coverage—contact a licensed New Jersey insurance professional to request customized quotes that align with state regulations and your financial goals.