Enterprise global payment solutions refer to institutional-grade financial technology infrastructures that enable multinational corporations, large marketplaces, and high-volume digital enterprises to process cross-border transactions, manage multi-currency accounts, and automate payouts securely across diverse regulatory and banking networks.
Understanding the Landscape of Enterprise Global Payment Solutions
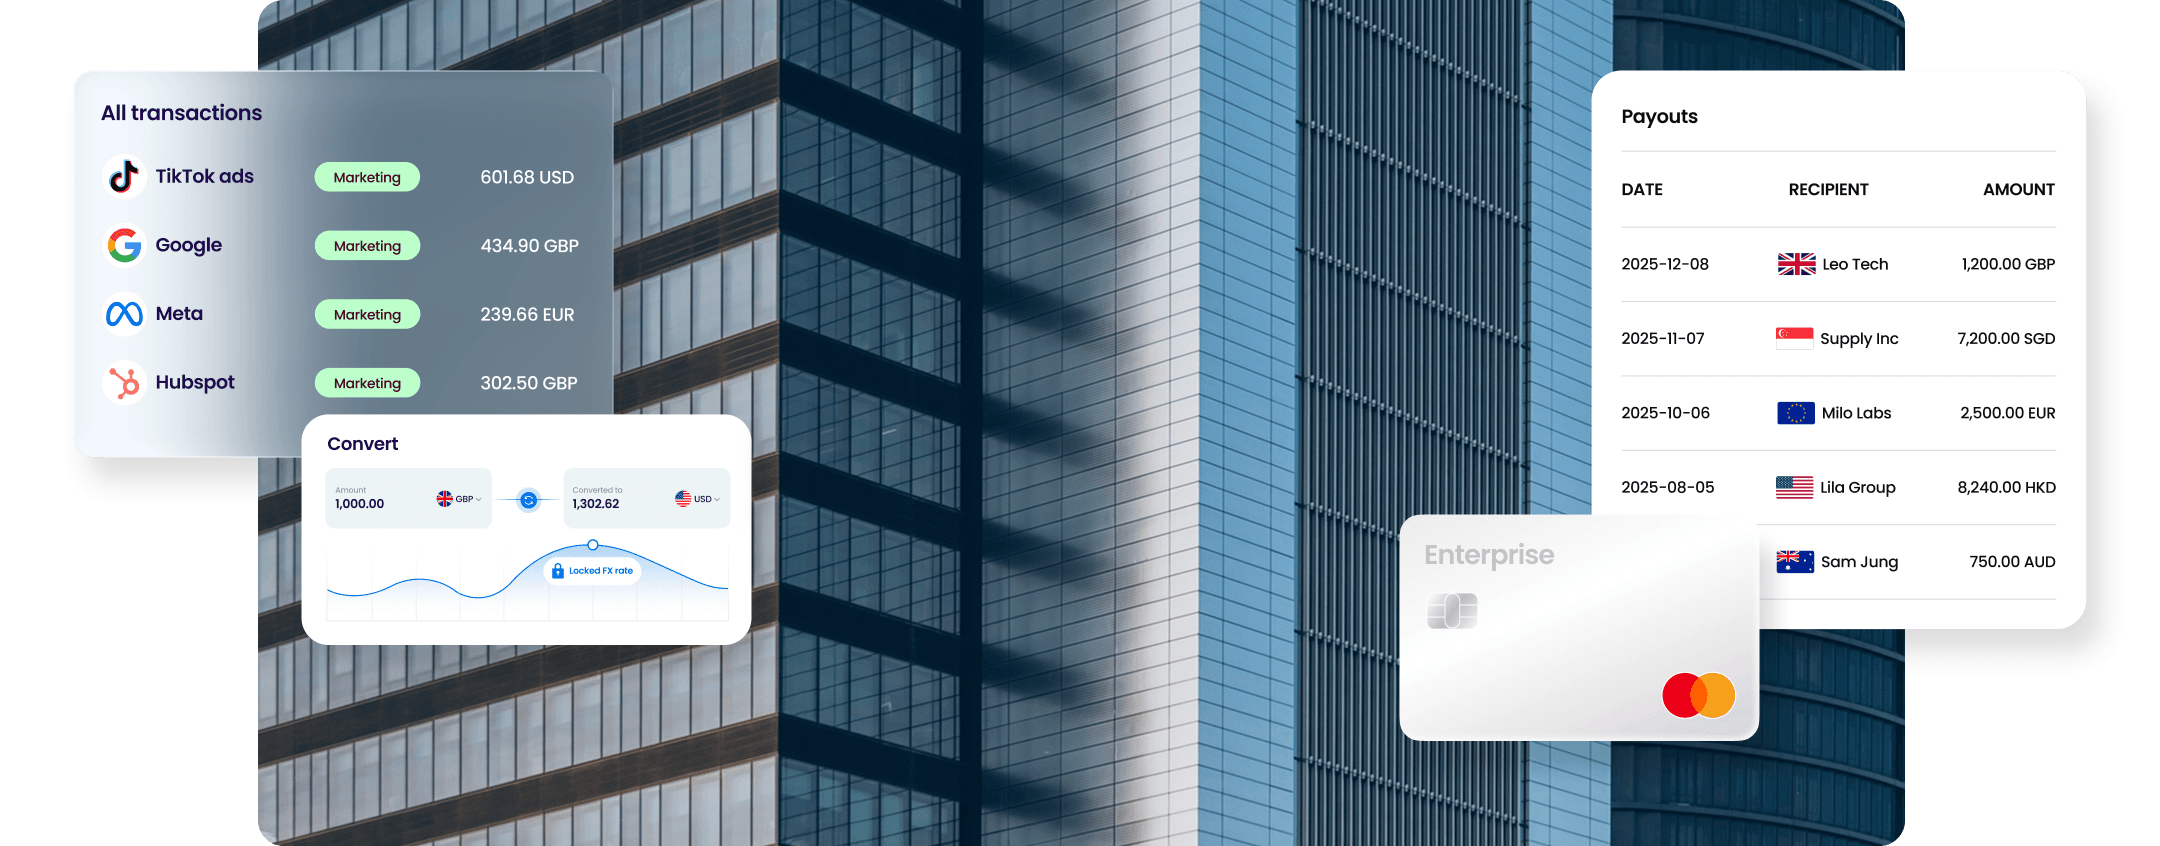
Operating a business across multiple international jurisdictions introduces immense financial complexity. Traditional banking networks often fail to meet the speed, transparency, and cost-efficiency required by modern multinational organizations. Enterprise global payment solutions bridge this gap by consolidating multi-currency operations, optimizing foreign exchange (FX) management, and integrating directly into enterprise resource planning (ERP) systems.
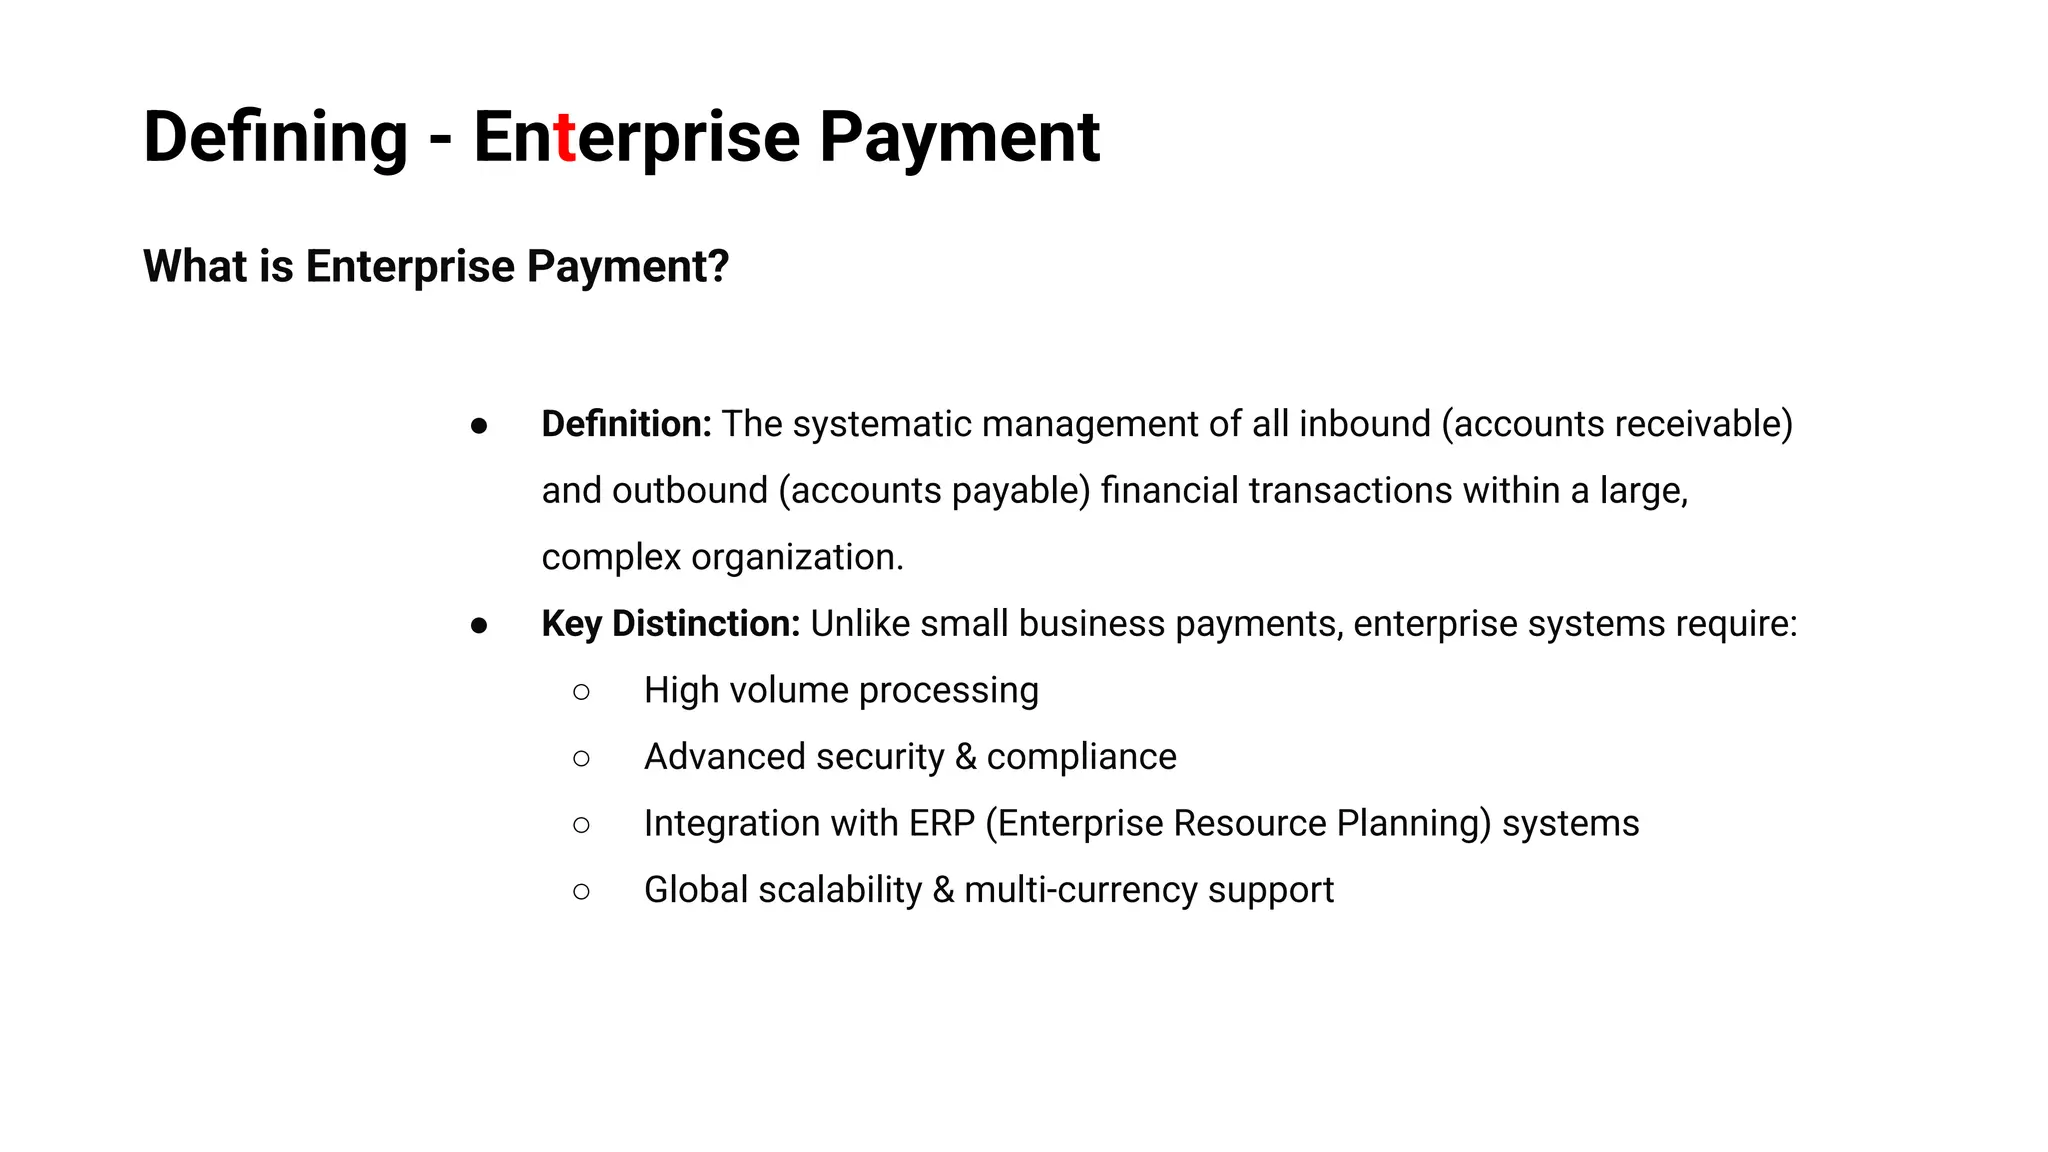
For the purposes of this guide, enterprise solutions are distinguished from small-and-medium-business (SMB) tools by their capacity to handle high-volume batch processing, complex tax and compliance requirements, custom API integrations, and robust treasury management features. As digital commerce accelerates worldwide, selecting and architecting the correct payment stack is vital for protecting profit margins and maintaining liquidity.
The Core Architectural Pillars
Modern global payment architectures are built upon several foundational pillars designed to eliminate friction in international cash flows:
- Multi-Currency Accounts (MCAs): Virtual and physical accounts that allow enterprises to hold, receive, and pay out in dozens of local currencies without mandatory immediate conversions.
- Smart Routing Engines: Algorithms that dynamically route transactions through the most cost-effective and reliable banking rails—such as SWIFT, local automated clearing houses (ACH), or real-time payment (RTP) networks.
- FX Optimization and Hedging Tools: Modules designed to minimize currency conversion costs, lock in exchange rates, and protect against market volatility.
- Orchestration Layers: Unified API gateways that abstract the complexity of managing dozens of local acquiring banks and alternative payment methods (APMs).
Key Capabilities and Technical Requirements
When evaluating enterprise-grade financial infrastructure, organizations must look beyond basic credit card processing capabilities. The technical requirements demand deep integration, uncompromising security, and scalability.
API-First Infrastructure and ERP Integration
Enterprise systems do not operate in a vacuum. A robust global payment solution must seamlessly integrate with existing technological ecosystems, including enterprise resource planning platforms like SAP, Oracle, and NetSuite, as well as customer relationship management (CRM) systems.
- RESTful APIs and Webhooks: Real-time data synchronization ensures that financial teams have instant visibility into incoming settlements, failed charges, and dispute statuses.
- Idempotency and Fault Tolerance: High-volume systems require robust idempotency keys to prevent duplicate charges during network timeouts or system retries.
- Custom Ledgering: Automated reconciliation tools that map transaction data back to general ledger accounts, reducing manual accounting overhead.
Security, Compliance, and Regulatory Frameworks
Operating globally means adhering to a labyrinth of local and international financial regulations. Non-compliance can result in severe financial penalties and reputational damage.
- PCI-DSS Level 1 Compliance: The gold standard for payment card security, ensuring that cardholder data is transmitted, processed, and stored securely.
- KYC and AML Automation: Built-in Know Your Customer (KYC) and Anti-Money Laundering (AML) screening tools that verify the identity of payees and buyers against global watchlists.
- Data Sovereignty and GDPR: Ensuring that transactional data complies with regional privacy laws, such as the European Union's General Data Protection Regulation, by offering localized data residency options.
Evaluating Architectural Models: Payment Gateways vs. Orchestration vs. Embedded Finance
Organizations face strategic choices regarding how they build their payment stack. The table below compares the primary structural approaches available to enterprise architects.
| Architecture Model | Primary Use Case | Integration Complexity | Control Over Routing & Cost | Best Suited For |
|---|---|---|---|---|
| Traditional Global Gateway | Standard e-commerce and regional credit card processing. | Low to Moderate | Low (Fixed acquirer relationships) | Mid-market companies with single-region focus. |
| Payment Orchestration Platform (POP) | Multi-acquirer setups, fallback routing, and unified reporting. | Moderate to High | High (Dynamic routing across multiple providers) | Large enterprises scaling into multiple international markets. |
| Embedded Financial Infrastructure | Software platforms embedding financial services and payouts for users. | High | Moderate (Dependent on underlying banking-as-a-service partners) | SaaS platforms, B2B marketplaces, and gig-economy giants. |
Operational Costs and Pricing Mechanics
Understanding the total cost of ownership (TCO) for enterprise global payment solutions requires analyzing more than just headline transaction fees. Hidden costs can quickly erode margins if not properly evaluated during the procurement phase.
Fee Structures Explained
- Interchange-Plus Pricing: The most transparent model, where the enterprise pays the exact interchange fee charged by the card networks plus a fixed markup by the payment provider.
- Blended Rates: A flat percentage and per-transaction fee regardless of the card type or origin. While simpler to forecast, this model is frequently more expensive for high-volume enterprises processing premium or international cards.
- FX Markups (Spread): The difference between the mid-market exchange rate and the rate charged by the provider. Enterprise solutions often negotiate tighter basis-point spreads compared to retail platforms.
- Cross-Border Fees: Additional surcharges applied when the card-issuing bank is in a different country than the merchant acquiring bank.
Hidden Operational Expenses
Beyond direct transaction costs, organizations must account for:
- Implementation and Professional Services Fees: Upfront costs associated with custom API development, ERP mapping, and security audits.
- Chargeback and Dispute Management Fees: Administrative costs incurred when processing customer chargebacks and fraud investigations.
- Maintenance and Engineering Overhead: Internal developer resources required to maintain API connections, update SDKs, and monitor system uptime.
Implementation Best Practices and Risk Management
Deploying a global payment solution across an enterprise is a cross-functional initiative involving finance, engineering, legal, and compliance teams. Adhering to structured deployment methodologies minimizes operational disruption.
Phased Rollout Strategy
- Discovery and Gap Analysis: Map existing payment flows, identify high-friction corridors, and document compliance mandates for target jurisdictions.
- Sandbox Testing and Validation: Execute rigorous end-to-end testing in simulated environments, focusing on edge cases such as partial refunds, currency fluctuations, and network timeouts.
- Canary Deployment: Route a small percentage of low-risk traffic (e.g., a specific geographic region or non-critical product line) through the new infrastructure to validate real-world performance.
- Full Cutover and Monitoring: Scale up traffic while utilizing real-time monitoring dashboards to track authorization rates, latency, and error codes.
Fraud Mitigation and Risk Scoring
As transaction volumes scale, enterprises become prime targets for sophisticated fraud rings, synthetic identity fraud, and friendly fraud (chargeback abuse). Modern enterprise solutions leverage machine learning models trained on global transaction networks to score risk in milliseconds without introducing unnecessary friction for legitimate customers. Implementing step-up authentication protocols, such as 3D Secure (3DS) version 2.2+, helps shift liability away from the merchant while complying with regional mandates like Strong Customer Authentication (SCA) in Europe.
Frequently Asked Questions
What is the difference between a payment gateway and a payment orchestrator?
A payment gateway connects a merchant's checkout interface to a single acquiring bank or processing network. A payment orchestration platform sits above multiple gateways and acquirers, allowing enterprises to route transactions dynamically based on cost, currency, or historical success rates through a single unified API.
How do enterprise solutions minimize foreign exchange (FX) losses?
Enterprise solutions minimize FX losses by utilizing multi-currency accounts that allow businesses to collect and hold local currencies, bypassing immediate conversion steps. They also offer advanced hedging tools and access to wholesale interbank exchange rates with minimal markups.
What compliance standards are mandatory for global enterprise payments?
Mandatory standards typically include Payment Card Industry Data Security Standard (PCI-DSS) Level 1 for card data security, regional data privacy regulations such as GDPR, and adherence to local Know Your Customer (KYC) and Anti-Money Laundering (AML) legal frameworks.
How long does it take to integrate a global payment solution into an existing ERP?
Integration timelines vary based on architectural complexity, legacy system constraints, and custom requirements. Simple gateway setups can take weeks, while deep enterprise ERP integrations involving custom ledgering and multi-entity reconciliation typically take three to nine months.
Can enterprise payment solutions handle local alternative payment methods (APMs)?
Yes. A primary advantage of modern enterprise platforms is their ability to aggregate local payment methods—such as Pix in Brazil, iDEAL in the Netherlands, or Alipay in China—alongside traditional credit cards through a single integration layer.
Conclusion and Strategic Next Actions
Selecting and deploying an enterprise global payment solution is a foundational strategic decision that impacts operational efficiency, customer satisfaction, and international growth potential. To move forward, stakeholders should conduct a comprehensive internal audit of current payment flows, map out target expansion markets, and engage prospective technology vendors with clear performance, compliance, and integration criteria.