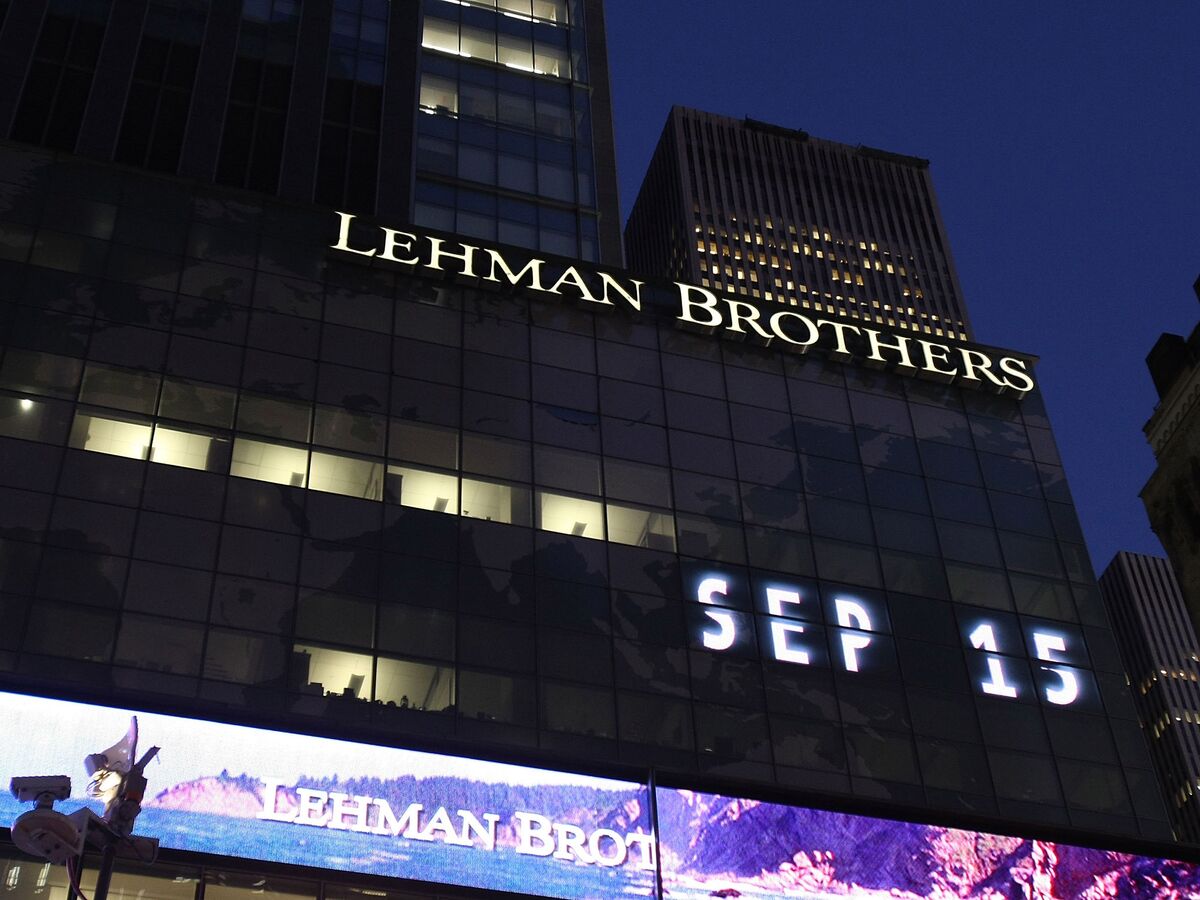
The term "Lehman email" refers to the trove of electronic communications from executives, employees, and analysts associated with Lehman Brothers, which became central to post-mortem investigations into the firm’s September 2008 collapse. These records documented the aggressive accounting maneuvers, liquidity crunches, and regulatory pressures that characterized the final months of the fourth-largest investment bank in the United States, providing critical evidence for congressional committees, bankruptcy examiners, and civil litigation.
Historical Background and the Collapse of Lehman Brothers
To understand the significance of the Lehman email archives, one must examine the operational environment of Lehman Brothers Holdings Inc. leading up to its historic bankruptcy filing on September 15, 2008. Founded in 1850, the firm evolved from a modest cotton brokerage in Montgomery, Alabama, into a global financial powerhouse heavily exposed to the subprime mortgage market. As the United States housing bubble deflated throughout 2007 and 2008, Lehman accumulated billions of dollars in toxic real estate assets, commercial mortgages, and leveraged loans that it could neither easily value nor successfully offload to secondary markets.
During this period of extreme market volatility, internal communications among traders, risk managers, and executive leadership grew increasingly tense. The firm’s senior management, led by Chief Executive Officer Richard Fuld, repeatedly insisted to shareholders, rating agencies, and federal regulators that the bank was adequately capitalized and possessed sufficient liquidity to weather the storm. However, internal email traffic revealed a starkly different reality characterized by frantic efforts to secure emergency funding, asset markdowns, and debates over the true exposure of the firm's balance sheet.
The publication and legal discovery of these electronic records shattered the public facade of stability. Regulatory bodies, including the Securities and Exchange Commission (SEC) and the Financial Industry Regulatory Authority (FINRA), as well as the United States House Committee on Oversight and Government Reform, subpoenaed millions of pages of electronic mail. These documents offered legal investigators a chronological view of how corporate governance structures failed to adequately restrain risk accumulation, shedding light on the precise moments when executives became aware of impending insolvency.
Key Themes and Disclosures Within the Email Archives
The recovered electronic mail from Lehman Brothers covers multiple operational dimensions of the firm, ranging from everyday administrative notes to confidential risk committee briefings. Analyzing these records highlights several recurring themes that dominated the post-bankruptcy investigations and subsequent civil proceedings.
Repo 105 and Balance Sheet Manipulation
One of the most legally significant revelations derived from the email corpus involved an accounting technique known internally as "Repo 105" and its shorter-term variant, "Repo 108." These transactions involved Lehman temporarily transferring securities off its balance sheet just before reporting period ends, replacing them with cash to artificially lower its reported net leverage ratio.
Internal emails demonstrated that senior finance executives, legal compliance officers, and outside auditors debated the ethical and regulatory implications of these transactions. Certain risk officers explicitly questioned whether Repo 105 transactions constituted true sales under standard accounting principles or merely collateralized loans designed to deceive the market. The written trail provided investigators with clear evidence that accounting treatments were manipulated specifically to project a misleading picture of financial health to credit rating agencies and investors.
Liquidity Management and Collateral Scrambles
As confidence in the global financial system plummeted following the collapse of Bear Stearns in March 2008, Lehman's liquidity position deteriorated rapidly. The email correspondence among treasury personnel, liquidity managers, and prime brokerage clients shows a daily scramble to meet margin calls and secure overnight funding.
Messages exchanged between Lehman executives and counterparties at major commercial banks reveal growing reluctance from Wall Street institutions to extend short-term credit to the firm without substantial collateral discounts, known as haircuts. These records exposed the systemic vulnerability of reliance on short-term wholesale funding markets during a liquidity crisis, illustrating how quickly market panic can freeze an institution's operational cash flow.
Communications with Regulators and Rating Agencies
The transparency of Lehman's interactions with regulatory authorities became a focal point of the Bankruptcy Court Examiner's report, authored by Anton Valukas. Internal correspondence captured instances where executives actively managed the flow of information to federal regulators to prevent public downgrades.
Furthermore, emails concerning interactions with credit rating agencies such as Moody's, Standard & Poor's, and Fitch highlighted the intense pressure applied by Wall Street firms to maintain investment-grade ratings. A downgrade below investment grade would have triggered immediate termination clauses in numerous trading agreements, accelerating the firm's demise. The electronic record documented how executives attempted to reassure ratings analysts while simultaneously acknowledging internally that their asset valuations were overly optimistic.
| Document Category | Primary Focus | Regulatory / Legal Significance |
|---|---|---|
| Repo 105 Correspondence | Temporary asset transfers designed to reduce net leverage at quarter-end. | Provided direct evidence of intent to mislead investors and auditors regarding balance sheet leverage. |
| Liquidity & Treasury Emails | Daily cash management, collateral demands, and repo market access. | Illustrated the rapid depletion of unencumbered assets and the failure of internal stress testing models. |
| Risk Committee Notes | Debates over commercial real estate concentration and subprime exposure. | Demonstrated that executive leadership was repeatedly warned about high-risk asset accumulations. |
| External Communications | Interactions with media, rating agencies, and federal regulators. | Documented attempts to manage public perception while internal assessments grew increasingly dire. |
Legal, Regulatory, and Governance Impact
The fallout from the release of the Lehman email archives extended far beyond the immediate bankruptcy proceedings, reshaping corporate compliance standards and regulatory oversight on a global scale.
The Valukas Report and Legal Accountability
Appointed by the U.S. Bankruptcy Court for the Southern District of New York, examiner Anton Valukas utilized the millions of recovered emails to construct a comprehensive 2,200-page report published in March 2010. This document relied heavily on direct quotes from internal electronic mail to establish color and legal standing for potential colorable claims against senior management, board members, and Ernst & Young, Lehman's outside accounting firm.
While criminal charges against senior executives were ultimately not pursued by federal prosecutors due to the high legal burden of proving criminal intent amidst complex financial engineering, the civil settlements resulting from the investigation totaled billions of dollars. These resolutions reshaped expectations regarding the personal liability of corporate officers and directors who ignore internal risk warnings.
Evolution of Corporate Email Governance and Compliance
The Lehman collapse served as a watershed moment for electronic discovery (e-discovery) and enterprise information archiving. In the wake of the bankruptcy, corporate legal departments globally overhauled their data retention and email monitoring policies.
Key changes adopted across the financial services industry include:
- Enhanced Surveillance: Implementation of automated lexicon-based scanning tools to flag internal communications discussing accounting treatments, regulatory avoidance, or liquidity strain.
- Stricter Archiving Protocols: Elimination of auto-delete functions on messaging platforms and stricter enforcement of policies prohibiting the use of unapproved encrypted messaging apps for business correspondence.
- Clearer Escalation Pathways: Formalization of reporting channels for risk and compliance officers who identify potentially fraudulent financial reporting or regulatory non-compliance.
Common Misconceptions and Research Guidance
When studying the historical record of Lehman Brothers through electronic communications, researchers, journalists, and students frequently encounter several widespread misconceptions.
One common error is the assumption that a single "smoking gun" email triggered the bankruptcy. In reality, the collapse was the result of a protracted structural failure driven by macroeconomic conditions, excessive leverage, and a systemic freeze in liquidity, rather than a solitary executive directive transmitted via email. The value of the email corpus lies in its cumulative documentation of institutional behavior and risk blindness over a period of years.
Another frequent point of confusion involves distinguishing between internal regulatory investigations and the public bankruptcy examiner's report. While various regulatory bodies collected subsets of electronic data for specific enforcement actions, the Valukas report remains the definitive public repository synthesizing the most critical internal correspondence into an organized legal narrative.
For researchers seeking to examine primary source documents, complete digital copies of the Valukas report and selected exhibits containing declassified internal memoranda and email excerpts are publicly accessible through the United States Bankruptcy Court records for the Southern District of New York and academic legal repositories hosted by major university law libraries.
Conclusion and Future Relevance
The examination of the Lehman email archive provides a sobering case study in institutional hubris, the limits of financial risk modeling, and the critical importance of transparent corporate governance. By capturing the unfiltered voices of executives, traders, and risk officers during a historic financial panic, these electronic records continue to serve as essential educational material for business ethics courses, legal training programs, and regulatory policy design in the modern financial era.