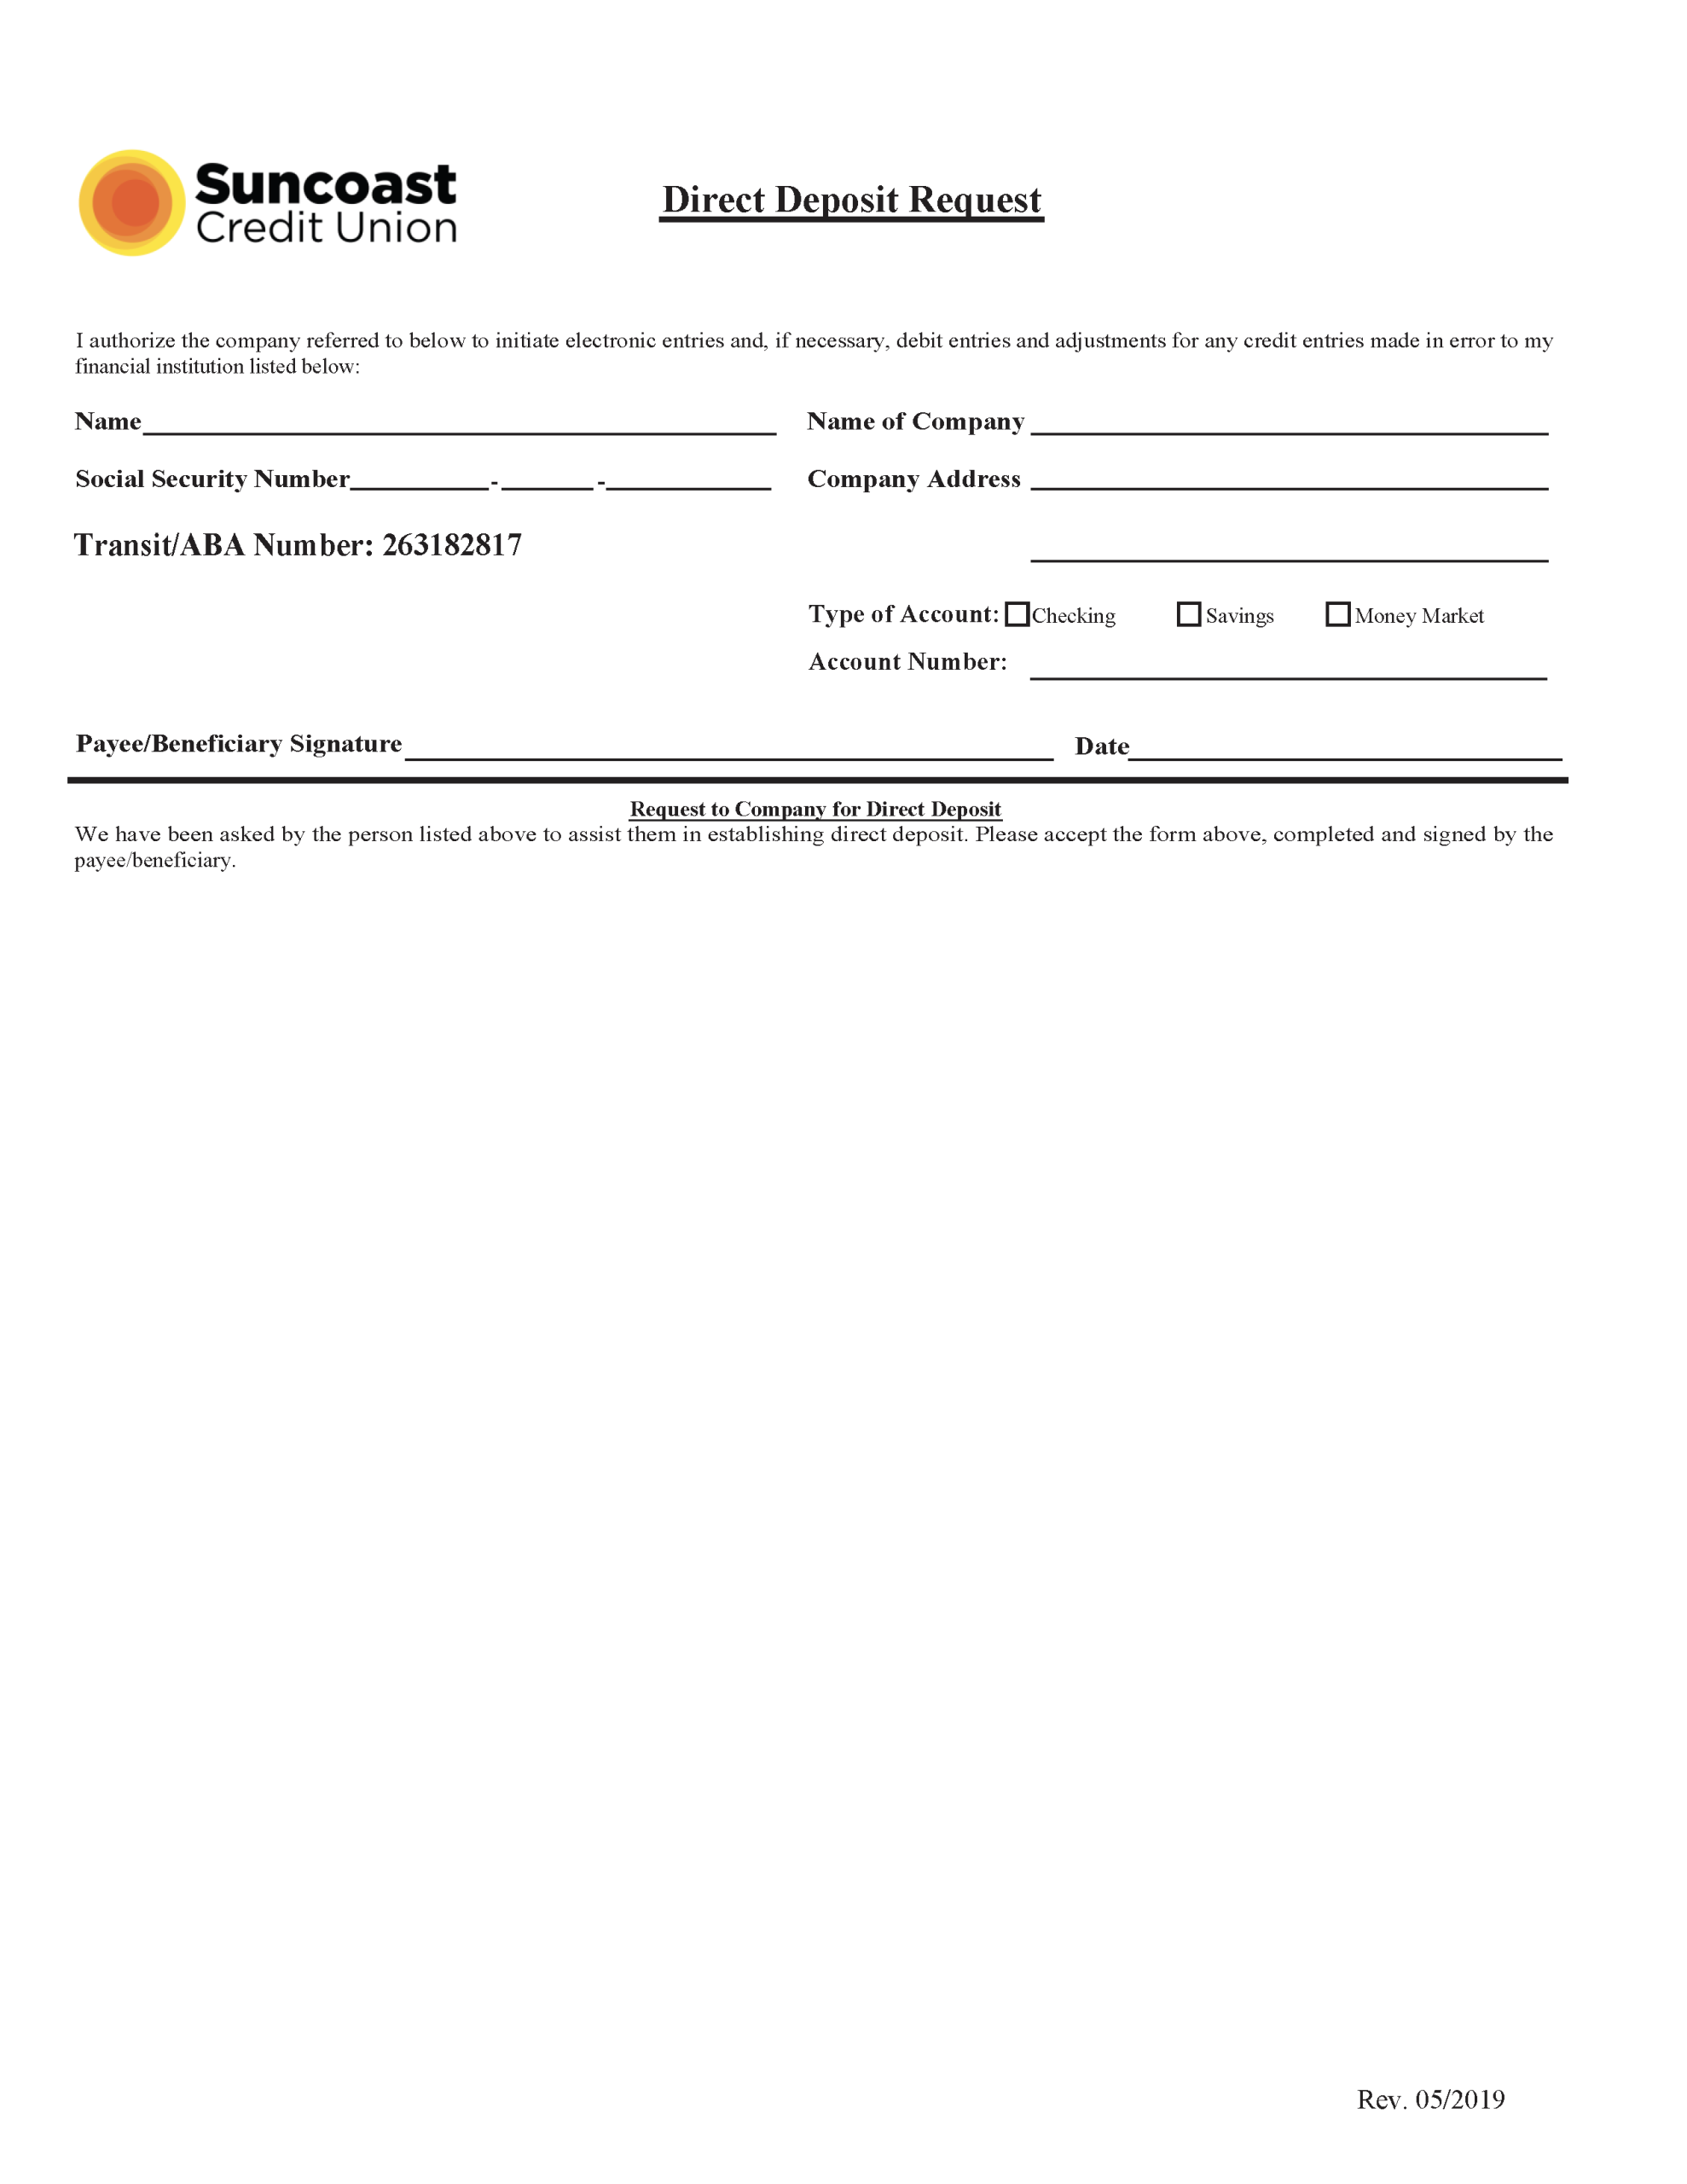
Suncoast Pay generally refers to online payment and financial transaction portals associated with Suncoast credit unions or specific regional municipal entities, serving as a centralized hub for members or citizens to settle bills, manage accounts, and execute secure financial transfers. Navigating these systems requires a clear understanding of user authentication requirements, fee schedules, processing windows, and standard troubleshooting protocols to ensure your financial obligations are met accurately and on time.
Overview and Purpose of Suncoast Pay Portals
Payment portals designed for institutional platforms streamline the transfer of funds between members, account holders, and service providers. When engaging with a system designated as "Suncoast Pay," the platform typically acts as a secure intermediary. Its primary purpose is to eliminate traditional friction points—such as mailing physical checks or visiting a brick-and-mortar branch—by digitizing the transaction lifecycle.
Institutions implement these interfaces to handle multiple types of transactions. Depending on the precise ecosystem, users may encounter portals built for credit union loan disbursements and credit card settlements, or localized utility and tax payment gateways used within specific geographic regions bearing the Suncoast name. Regardless of the exact backend configuration, the overarching goal remains uniform: providing a PCI-DSS (Payment Card Industry Data Security Standard) compliant environment where sensitive financial data is encrypted during transit and at rest.
Understanding the distinction between internal member transfers (such as paying a Suncoast Credit Union auto loan from a Suncoast checking account) and external payment gateways (such as municipal or commercial billing portals) is critical. Internal credit union portals usually interface directly with your core banking ledger, posting payments instantly or within standard processing windows. External payment gateways, conversely, often rely on third-party payment processors like Automated Clearing House (ACH) networks, debit card networks, or credit card processors, which can introduce distinct fee structures and processing delays.
Eligibility, Prerequisites, and Account Setup
Before executing transactions through a Suncoast payment platform, users must fulfill specific administrative and technical prerequisites. Attempting to initiate payments without establishing the proper credentials often leads to transaction failures, locked accounts, or delayed posting dates that can trigger late fees.
To use these platforms effectively, you must typically have:
- An active, verified account or loan profile with the issuing institution.
- A valid email address and a mobile phone number capable of receiving multi-factor authentication (MFA) codes.
- An accepted funding source, which may include a routing and account number for ACH transfers, an eligible debit card, or an accepted credit card (Visa, Mastercard, Discover).
- A secure, updated web browser or the official mobile application provided by the institution.
Account registration generally follows a structured validation sequence. Users are required to provide primary identifiers, such as a member account number, Social Security Number (SSN) or Taxpayer Identification Number (TIN), and a date of birth. Once the system verifies these identifiers against its internal database, you will be prompted to establish a unique username and a complex password adhering to modern cybersecurity standards.
Enabling multi-factor authentication during this initial setup phase is strongly recommended. MFA introduces an extra security layer by requiring a secondary verification code sent via SMS, email, or an authenticator app whenever a login is attempted from an unrecognized device or when high-value transactions are initiated.
Transaction Types, Fees, and Processing Times
Different payment methods carry distinct operational rules, processing speeds, and potential fee implications. Reviewing these factors before submitting a payment prevents unexpected charges and ensures funds clear before relevant due dates.
| Payment Method | Typical Processing Time | Potential Fees | Best Used For |
|---|---|---|---|
| Internal Account Transfer | Instant to 1 Business Day | $0.00 (Free) | Paying Suncoast loans from Suncoast checking/savings |
| ACH / Electronic Check | 2 to 3 Business Days | Usually Free; check institution policy | Standard bill payments where processing time allows |
| Debit Card Gateway | Immediate posting; 1-2 days to clear | Flat fee or percentage-based fee may apply | Expedited payments requiring same-day credit |
| Credit Card Gateway | Immediate posting; 1-2 days to clear | Convenience fees often range from 2% to 3% | Emergency payments or maximizing rewards (if net of fees) |
Internal transfers executed entirely within a credit union's proprietary ledger represent the fastest and most cost-effective method. Because no external clearinghouse is involved, funds typically move immediately, reflecting accurately on both the sending and receiving balances.
External ACH payments, while generally free of direct transaction fees, are subject to the mechanics of the Automated Clearing House network. Payments submitted after daily cutoff times (often set at 5:00 PM Eastern Time) do not begin processing until the following business day. Weekends and federal holidays further extend clearing times. Consequently, relying on standard ACH for same-day due dates is a frequent source of accidental late payments.
Debit and credit card payment channels offer immediate posting benefits, ensuring the payee registers the credit on the exact day of submission. However, institutions and third-party gateways frequently pass processing costs onto the user via convenience fees. Users must weigh the cost of these fees against the potential penalties of a late payment.
Step-by-Step Guide to Executing a Payment
Navigating the user interface to complete a transaction requires attention to detail. Following a systematic procedure minimizes the risk of keystroke errors, misapplied funds, or incomplete submissions.
- Access the Secure Portal: Navigate directly to the official web address or open the verified mobile application. Avoid clicking links in unsolicited emails or text messages to prevent phishing exposure.
- Authenticate Your Session: Enter your username and password. Complete any secondary multi-factor authentication prompts by entering the code delivered to your registered device.
- Navigate to the Payment Hub: Locate the menu options labeled "Transfers," "Pay Bills," or "Make a Payment." Select the specific account, loan, or bill you intend to credit.
- Select the Funding Source: Choose your pre-linked bank account, debit card, or credit card. If using a new funding source, enter the required routing and account numbers or card details carefully.
- Specify Amount and Effective Date: Enter the exact payment amount. If the portal allows scheduled payments, select the calendar date you wish the transaction to execute.
- Review Transaction Disclosures: Carefully examine the summary screen, noting any service fees, the funding source, and the projected posting date.
- Authorize and Save Confirmation: Click the final authorization button (e.g., "Submit Payment" or "Authorize Transfer"). Record or screenshot the confirmation number provided on the success screen for your permanent financial records.
Common Errors and Troubleshooting Protocols
Even with robust digital infrastructure, users occasionally encounter technical hurdles or transaction rejections. Identifying the root cause of an error allows for swift remediation.
Invalid Routing or Account Numbers
If an ACH payment is rejected, the primary culprit is often an input error in the routing or account number fields. Financial institutions issue automated Return Codes when an ACH transaction fails. If your payment bounces, verify your checks or online bank statements to ensure every digit matches precisely before re-submitting.
Locked Accounts Due to Failed Logins
Entering incorrect passwords repeatedly triggers automated security lockouts to protect against brute-force attacks. If your account is locked, do not repeatedly guess credentials. Utilize the automated "Forgot Password" or "Reset Username" utilities, which verify identity through secure email or phone prompts. If automated recovery fails, contact the institution's member services or technical support department directly.
Browser Compatibility and Cache Issues
Outdated web browsers, corrupted cache files, or aggressive ad-blockers can interfere with secure JavaScript scripts required by payment portals. If buttons fail to respond or payment pages loop endlessly, clear your browser cache and cookies, disable browser extensions temporarily, or switch to an alternative modern browser like Google Chrome, Mozilla Firefox, or Apple Safari.
Frequently Asked Questions
Can I cancel a payment after it has been submitted through a Suncoast pay portal?
Whether a payment can be cancelled depends entirely on its processing stage. Internal transfers and scheduled ACH payments can typically be cancelled via the portal interface if they are still in a "Pending" or "Scheduled" status prior to the daily cutoff time. Once a transaction moves to "Processing" or "Posted," cancellation is no longer possible through the portal, and you must contact customer support directly to discuss stop-payment options or dispute procedures.
Are there maximum transaction limits imposed on online payments?
Yes. Financial institutions and third-party payment gateways enforce daily and per-transaction limits to mitigate fraud and manage liquidity risk. These limits vary based on account age, member status, and the chosen funding method. If your payment exceeds the maximum allowable limit, the system will prompt an error message requiring you to break the payment into smaller increments or utilize an alternative payment method like a wire transfer or cashier's check.
What should I do if my payment posts late due to a system outage?
If the payment platform experiences downtime that prevents you from submitting a payment on its due date, document the outage immediately by taking timestamped screenshots of error messages. Contact the billing department or loan servicer immediately to report the technical failure. Many institutions will waive late fees or adjust credit reporting if the delay stems directly from verified platform outages, provided you attempt payment promptly once service is restored.
How do I update my expired debit or credit card on file?
To update payment credentials, log into your secure account dashboard and navigate to the "Wallet," "Payment Methods," or "Profile Settings" section. Locate the expired card profile and select the option to edit or delete the entry. Input the new card number, expiration date, and CVV security code. Ensure your billing address matches the address on file with your card issuer to prevent authorization rejections.
Is it safe to save my payment credentials within the portal?
Saving payment methods within a password-protected, encrypted portal is generally secure for everyday convenience. However, cybersecurity best practices dictate that you should only save credentials on private, trusted devices protected by biometric locks or strong device passcodes. Avoid saving financial details on shared computers, public library terminals, or unsecured public Wi-Fi networks.
Conclusion and Next Actions
Effectively managing transactions through a Suncoast pay interface requires balancing convenience with vigilance regarding processing windows, potential fees, and security practices. To ensure smooth financial operations, verify your account details before submitting payments, monitor your transaction history regularly for confirmation numbers, and utilize internal transfer channels whenever possible to avoid external clearing fees. If you encounter persistent technical issues or financial discrepancies, gather your transaction IDs and error logs, then reach out directly to the institution's official support channels for personalized assistance.