Deborah Jeter is a distinguished accounting educator, researcher, and Professor Emerita of Accounting at Vanderbilt University’s Owen Graduate School of Management. Best known as the co-author of the widely adopted textbook Advanced Accounting, her scholarship focuses on complex financial reporting standards, business combinations, consolidated financial statements, foreign currency transactions, and audit fee structures.
Academic Background and Professional Career of Deborah Jeter
Deborah H. Jeter built a career centered on accounting research, higher education, and financial reporting analysis. After earning her Bachelor of Science and Master of Business Administration degrees from Western Kentucky University, she completed her Doctor of Philosophy (Ph.D.) in Accounting at Vanderbilt University. As a Certified Public Accountant (CPA), Jeter combined practical industry knowledge with academic rigor throughout her tenure on the faculty at Vanderbilt University’s Owen Graduate School of Management.
During her time at Vanderbilt, Jeter taught undergraduate, graduate, and executive-level courses in financial accounting, managerial accounting, and advanced financial reporting. Her academic work extends beyond classroom instruction into empirical accounting research. Her published papers have appeared in leading academic journals, including The Accounting Review, Journal of Accounting and Economics, Auditing: A Journal of Practice & Theory, and Contemporary Accounting Research.
Jeter's research contributions focus primarily on financial reporting quality, audit pricing dynamics, auditor independence, earnings management, and the economic consequences of debt covenant violations. By examining how financial disclosure rules impact corporate behavior and capital markets, her academic publications provided valuable empirical evidence for regulators, auditors, and corporate financial managers.
The Landmark Textbook: Jeter & Chaney’s Advanced Accounting
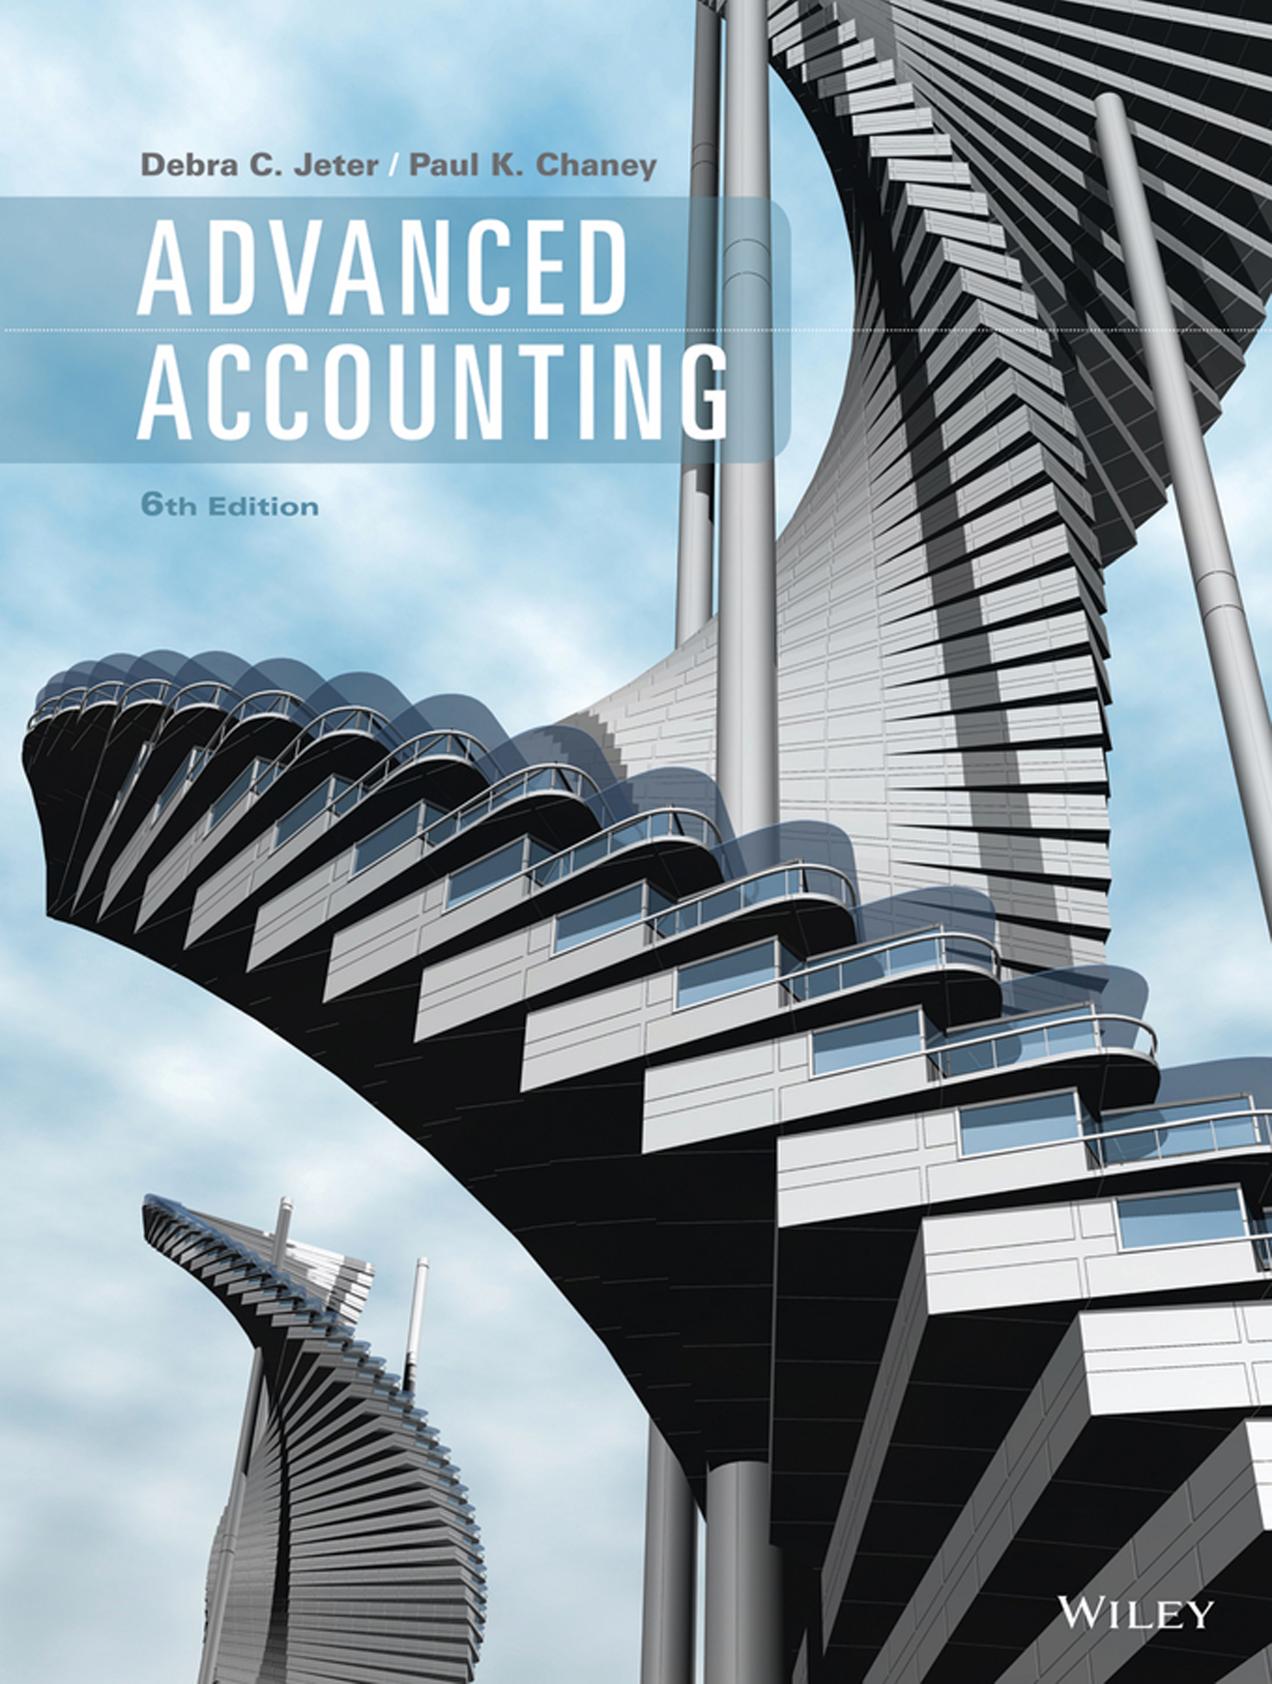
Among accounting professionals, educators, and university students, Deborah Jeter is recognized for co-authoring Advanced Accounting alongside Paul K. Chaney. Published by John Wiley & Sons, this text serves as a cornerstone curriculum resource in upper-level undergraduate and Master of Science in Accounting (MSA) programs across North America and internationally.
- Jeter & Chaney's Advanced Accounting
- Corporate M&A & ASC 805 Acquisition Accounting
- Consolidations & Intercompany (810)
- Global & Non-Profit Reporting (830 & GASB)
The textbook addresses some of the most technical topics in financial accounting. Rather than focusing solely on mechanical journal entries, Jeter and Chaney designed the material to emphasize the underlying economic rationale driving accounting standards issued by the Financial Accounting Standards Board (FASB) and the International Accounting Standards Board (IASB).
Key pedagogical features established by Deborah Jeter in Advanced Accounting include:
- Comprehensive Elimination Worksheets: Clear visual frameworks demonstrating step-by-step consolidation entry mechanics.
- Dual-Standard Alignment: Parallel discussions comparing U.S. GAAP (FASB Accounting Standards Codification) with International Financial Reporting Standards (IFRS).
- Real-World Disclosures: Integration of actual corporate financial statements and SEC filings (Form 10-K) to illustrate complex accounting transactions.
- CPA Exam Readiness: Direct alignment with the Financial Accounting and Reporting (FAR) section of the Uniform CPA Examination.
Core Accounting Topics Covered in Jeter’s Framework
Deborah Jeter’s teaching and writing framework breaks down complex accounting scenarios into manageable, step-by-step methodologies. Her work covers several key areas of advanced financial reporting.
1. Business Combinations (FASB ASC 805 / IFRS 3)
Business combinations represent one of the primary areas of focus in Jeter’s curriculum. The framework details the transition from legacy methods (such as the pooling-of-interests method) to the modern acquisition method mandated by FASB ASC 805.
Jeter outlines the complete accounting lifecycle of mergers and acquisitions:
- Identifying the Acquirer: Determining control based on voting rights, board composition, and transaction structure.
- Determining the Acquisition Date: Establishing the date control is legally transferred.
- Measuring Consideration Transferred: Valuing cash, stock issuance, contingent consideration, and debt assumed at fair market value.
- Recognizing Assets Acquired and Liabilities Assumed: Allocating fair value to tangible and identifiable intangible assets (such as patents, trademarks, and customer relationships).
- Calculating Goodwill or Bargain Purchase Gains: Measuring residual goodwill when purchase price exceeds net asset fair value, or recording an immediate gain in net income if the transaction is a bargain purchase.
2. Consolidated Financial Statements and Intercompany Transactions (FASB ASC 810)
When a parent company acquires a controlling financial interest in a subsidiary, consolidated financial statements are required to present the economic entity as a single enterprise. Jeter's framework provides systematic procedures for eliminating intercompany transactions to prevent double-counting of revenues, expenses, assets, and liabilities.
Key elimination categories covered include:
- Intercompany Inventory Sales: Removing unrealized profit from ending inventory and adjusting cost of goods sold (COGS) for both downstream (parent to subsidiary) and upstream (subsidiary to parent) transfers.
- Intercompany Fixed Asset Transfers: Adjusting gain or loss on sale of land, buildings, and equipment, along with recalculating accumulated depreciation based on original cost bases.
- Intercompany Bondholdings: Accounting for constructive retirement of debt when one affiliate purchases the outstanding bonds of another affiliate on the open market.
- Noncontrolling Interest (NCI): Measuring and presenting the portion of subsidiary net assets and net income attributable to non-parent shareholders on the consolidated balance sheet and income statement.
3. Foreign Currency Transactions and Translation (FASB ASC 830)
Global corporate operations require converting financial statements from foreign entities into the reporting currency of the parent organization. Jeter’s work clarifies the two primary techniques used under FASB ASC 830:
- The Current Rate Method: Applied when the foreign entity’s functional currency is its local currency. Assets and liabilities are translated at the current spot exchange rate on the balance sheet date, income statement items are translated at weighted-average exchange rates, and translation adjustments are recorded in Other Comprehensive Income (OCI) as part of Accumulated Other Comprehensive Income (AOCI).
- The Temporal Method (Remeasurement): Applied when the foreign entity’s functional currency is the U.S. dollar or when the economy suffers from hyperinflation. Monetary items are translated at current exchange rates, non-monetary items (such as inventory and property, plant, and equipment) are translated at historical rates, and remeasurement gains or losses are recognized directly in consolidated net income.
4. Partnership Accounting and Corporate Liquidations
Beyond corporate consolidations, Jeter’s writings cover capital structures for partnerships and troubled business entities. Her partnership framework outlines:
- Formation and Initial Capital Contributions: Evaluating tax bases versus fair market values of contributed assets.
- Profit and Loss Allocation Agreements: Applying multi-tier allocation formulas involving interest allowances, salary allowances, and residual profit split ratios.
- Admission and Retirement of Partners: Utilizing the Bonus Method versus the Revaluation (Goodwill) Method when ownership shares are transferred.
- Partnership Liquidation: Structuring simple liquidations and installment liquidations using Safe Payment Schedules and Cash Distribution Plans to protect creditor and partner capital accounts.
5. Governmental and Non-Profit Accounting (GASB & FASB Standards)
A complete advanced financial accounting education requires exposure to non-business entities. Jeter’s educational materials cover the specialized rules governed by the Governmental Accounting Standards Board (GASB) for state and local municipalities, as well as FASB standards for private non-profit institutions.
The curriculum covers:
- Fund Accounting Structures: Separating accounts into Governmental Funds (General, Special Revenue, Capital Projects, Debt Service, Permanent), Proprietary Funds (Enterprise, Internal Service), and Fiduciary Funds (Trust and Custodial).
- Measurement Focus and Basis of Accounting: Balancing the modified accrual basis (current financial resources measurement focus used in governmental funds) with the full accrual basis (economic resources measurement focus used in government-wide statements and proprietary funds).
- Financial Reporting Units: Preparing Annual Comprehensive Financial Reports (ACFR) featuring fund-level financial statements reconciled to government-wide statement of net position and statement of activities.
Comparison Table: Core Topics in Advanced Accounting Frameworks
The following matrix synthesizes the accounting domains covered in Deborah Jeter's work, showing their relevant regulatory standards, primary procedural tasks, and real-world accounting applications.
| Accounting Domain | Primary Authoritative Standard | Key Methodological Focus | Practical Application / Regulatory Impact |
|---|---|---|---|
| Business Combinations | FASB ASC 805 / IFRS 3 | Acquisition method, fair value asset valuation, goodwill calculation | Corporate mergers, acquisitions, purchase price allocations |
| Consolidated Statements | FASB ASC 810 | Elimination entries, intercompany profit removal, NCI allocation | Parent-subsidiary financial statement consolidation |
| Foreign Currency Translation | FASB ASC 830 | Current rate method vs. Temporal remeasurement method | Multinational financial reporting, FX risk disclosure |
| Partnership Operations | Subchapter K (IRC) / UPA | Bonus method, revaluation method, safe payment schedules | Accounting for law firms, medical practices, equity partnerships |
| State & Local Government | GASB Statements | Fund accounting, modified accrual, budgetary entry integration | Municipal financial reporting (ACFR preparation) |
| Not-for-Profit Entities | FASB ASC 958 | Net assets with and without donor restrictions, functional expenses | Non-profit financial statements and public compliance |
How to Study and Master Advanced Accounting using Jeter's Framework
For accounting majors, graduate students, and professionals preparing for the CPA Exam, mastering advanced financial accounting requires a structured approach. Deborah Jeter’s pedagogical approach emphasizes systematic practice and concept mapping over rote memorization.
- Master Fundamentals: Equity Method & ASC 805
- Standard Worksheets: Elimination Entries (C, E, R, O, N)
- Multi-Currency & GASB: Foreign Translation & Fund Rules
- Real-World Auditing: Review 10-K Notes & Disclosures
Step 1: Establish a Solid Base in Investment Accounting
Before tackling consolidated statements, master the distinction between alternative methods of accounting for equity investments:
- Fair Value Method: Applied when ownership is below 20% and significant influence is absent.
- Equity Method (FASB ASC 323): Applied when ownership is between 20% and 50% (or when significant influence exists). Understand how parent company journal entries reflect equity in subsidiary net income, dividend distributions, and amortizations of fair value differentials.
- Consolidation Method: Applied when control exists (typically over 50% voting interest or variable interest entity primary beneficiary status).
Step 2: Learn Standard Consolidation Elimination Entries
Jeter's framework relies on standard working paper elimination codes to streamline complex consolidation procedures. Practice preparing working paper entries using the established mnemonic framework:
- Entry C: Eliminate changes in the parent's investment account during the current year (equity in subsidiary income and dividends declared).
- Entry E: Eliminate beginning-of-year subsidiary equity balances (common stock, additional paid-in capital, retained earnings) against the parent investment account and noncontrolling interest.
- Entry R: Recognize differential allocations (revaluation of assets/liabilities to fair value at acquisition date).
- Entry O: Eliminate intercompany transaction balances (accounts receivable/payable, loans, management fees).
- Entry N: Allocate current-year net income and dividend distributions to the noncontrolling interest.
Step 3: Analyze Real-World SEC Filings
Apply theoretical concepts directly to public filings available through the SEC EDGAR database:
- Examine Note disclosures for major acquisitions in a public company’s Form 10-K, focusing on the allocation of purchase consideration to goodwill and identifiable intangibles.
- Review the Consolidated Statements of Comprehensive Income to observe how Foreign Currency Translation Adjustments flow into Accumulated Other Comprehensive Income.
Research Legacy and Academic Contributions
Beyond her textbook contributions, Deborah Jeter’s academic career generated valuable insights into audit economics and corporate disclosure behaviors. Her empirical research studies investigated how financial markets respond to accounting choices and regulatory changes.
Audit Pricing and Auditor Transitions
Jeter conducted research examining the determinants of audit fees and the market dynamics surrounding changes in independent auditor appointments. Her work demonstrated that:
- Auditor switches often occur following corporate restructurings, changes in management, or financial distress.
- Audit fee discounting ("initial low-balling") can occur in the initial years of an engagement, though regulatory and market discipline helps maintain audit quality.
- Complex client structures—such as multinational operations requiring multi-currency consolidations—correlate directly with higher baseline audit fees due to increased testing requirements under auditing standards.
Accounting Disclosures and Debt Covenants
Another key focus of Jeter’s published research involves the interaction between financial reporting flexibility and debt agreements. Her work analyzed how managers use discretionary accounting choices (accruals) to maintain compliance with debt covenants, such as leverage ratios and interest coverage thresholds. These findings helped demonstrate the real-world economic incentives that influence corporate financial reporting.
Frequently Asked Questions (FAQs)
Who is Deborah Jeter?
Deborah H. Jeter is an accounting scholar, CPA, and Professor Emerita of Accounting at Vanderbilt University’s Owen Graduate School of Management. She is recognized for her academic research on auditing and financial disclosures, as well as co-authoring the textbook Advanced Accounting.
What topics are emphasized in Deborah Jeter’s Advanced Accounting textbook?
The textbook focuses on business combinations (FASB ASC 805), consolidated financial statements (FASB ASC 810), foreign currency transactions and translation (FASB ASC 830), partnership accounting, corporate liquidations, and governmental/non-profit accounting (GASB/FASB standards).
How does Deborah Jeter’s textbook prepare students for the CPA Exam?
Jeter’s text aligns directly with the Financial Accounting and Reporting (FAR) section of the Uniform CPA Examination. It offers detailed elimination worksheets, comprehensive problem sets, and balanced coverage of both U.S. GAAP and IFRS rules.
What is the primary difference between the acquisition method and older business combination methods in Jeter's framework?
Under the modern acquisition method (FASB ASC 805), all acquired assets and assumed liabilities are recognized at fair value on the acquisition date, with goodwill recorded as the residual balance. Older methods, such as the pooling-of-interests method, carried forward historical book values without recognizing goodwill or fair value adjustments.
How does Jeter’s accounting framework handle foreign currency translation?
Jeter presents two methods based on the foreign entity's functional currency: the Current Rate Method (where translation adjustments go to Other Comprehensive Income in equity) and the Temporal Method (where remeasurement gains and losses impact net income directly).
Key Takeaways and Next Steps
Deborah Jeter’s work has helped shape advanced accounting education by turning complex regulatory standards into structured, practical learning frameworks. Her contributions serve as an essential foundation for accounting students, academics, and finance professionals navigating complex financial reporting environments.
To build on the principles established in Jeter’s accounting framework, consider taking these actionable steps:
- Review Authoritative Guidance: Refer directly to the FASB Accounting Standards Codification (specifically ASC 805, ASC 810, and ASC 830) when reviewing consolidated reporting issues.
- Practice Working Paper Mechanics: Work through standard multi-column consolidation worksheets to master elimination entries for intercompany transactions, inventory markups, and noncontrolling interests.
- Study Real-World Footnote Disclosures: Examine 10-K filings from multinational corporations to see how acquisition accounting, goodwill impairment tests, and foreign currency translations operate in actual public reporting.