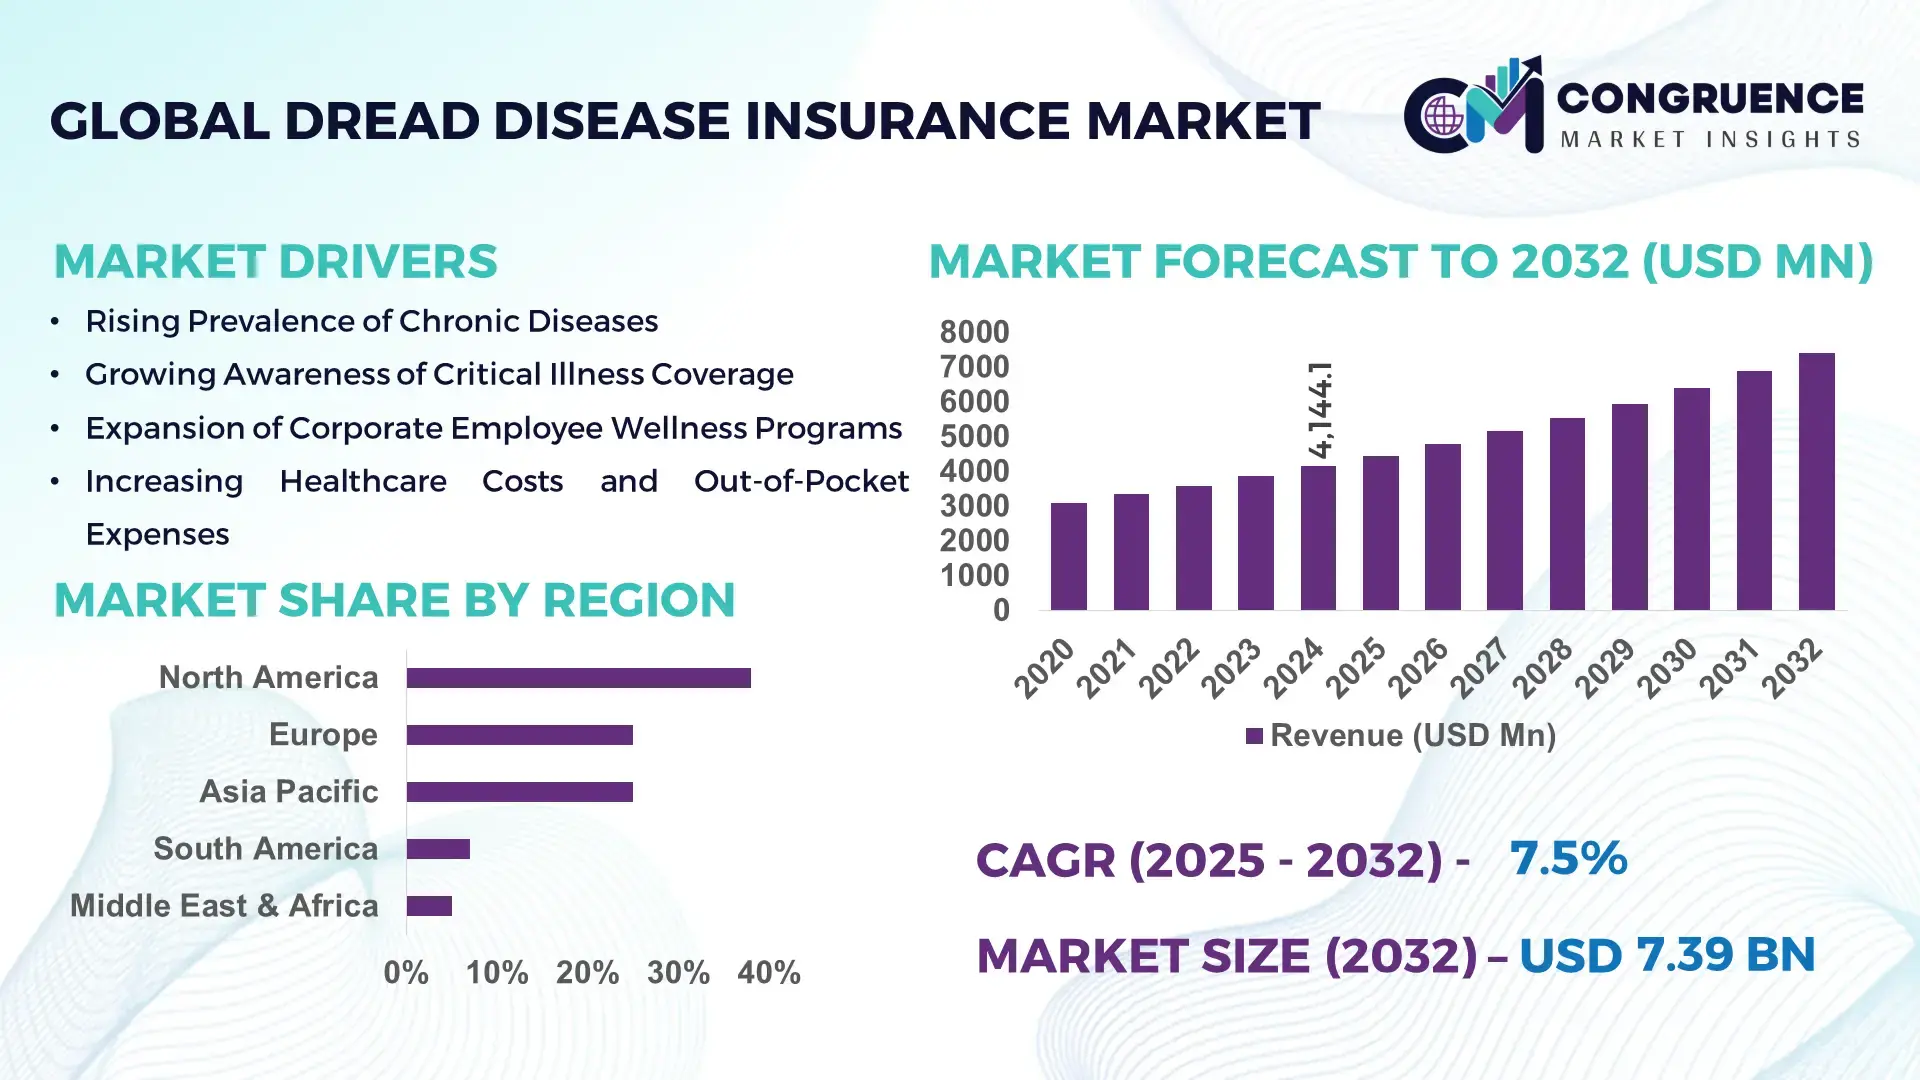
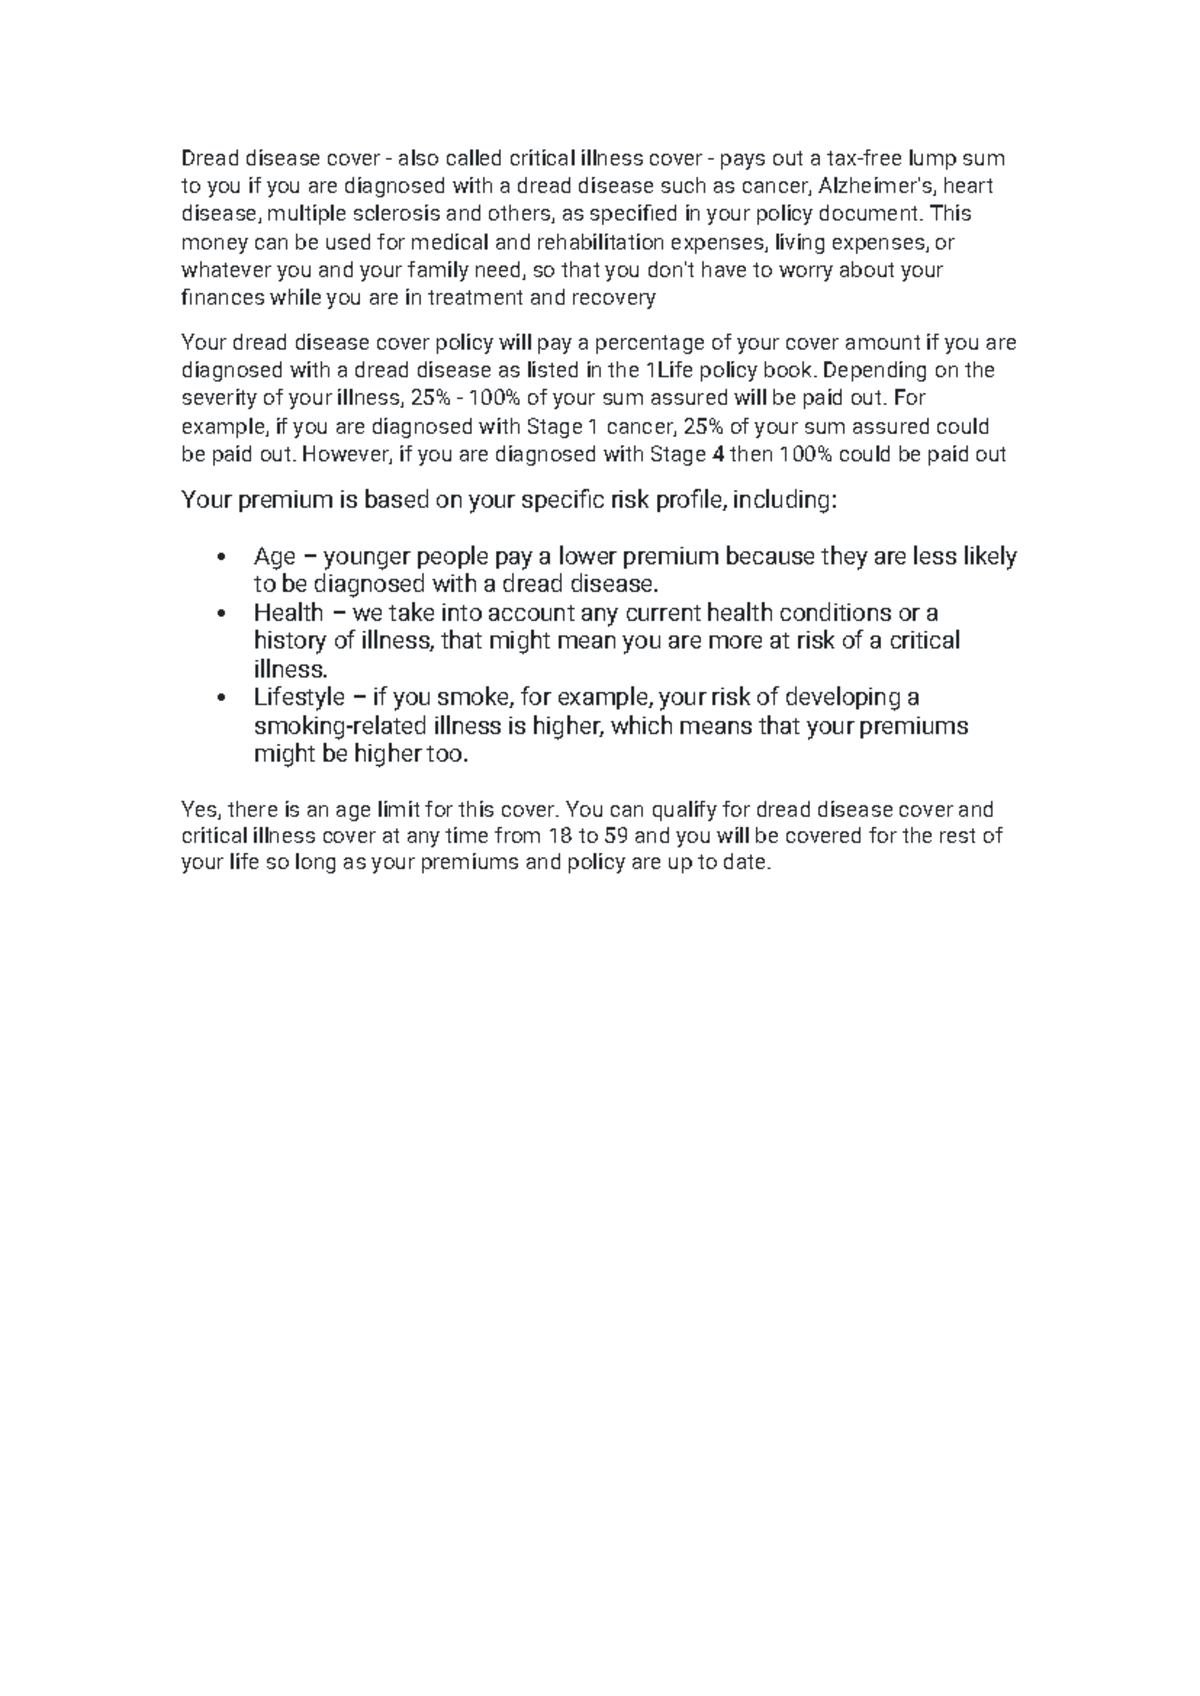
Dread disease insurance, commonly known as critical illness insurance, is a specialized financial product designed to provide a lump-sum cash benefit upon the diagnosis of a covered severe medical condition, such as cancer, stroke, or heart attack, helping policyholders manage out-of-pocket medical costs and daily living expenses during recovery.
Introduction to Dread Disease Insurance
Navigating a severe medical diagnosis involves immense emotional and physical strain, but the financial burden can compound these challenges exponentially. Even with comprehensive standard health insurance, patients frequently face substantial out-of-pocket costs, including high deductibles, specialized medications not covered by formularies, experimental therapies, and travel expenses for out-of-area treatment. Furthermore, a prolonged recovery period often leads to lost income for both the patient and any family members acting as caregivers.
Dread disease insurance—historically and commercially referred to as critical illness insurance—was developed to bridge this coverage gap. Originating in South Africa in the 1980s by surgeon Dr. Marius Barnard, the concept recognized that modern medical advancements were saving patients from fatal outcomes of major illnesses, but the resulting financial devastation was crippling families. Today, these policies exist worldwide as standalone products or as riders attached to life insurance policies. Understanding how these plans operate, what they cover, and their limitations is essential for anyone evaluating their long-term financial security.
Evolution and Core Purpose of Critical Illness Policies
To fully appreciate modern dread disease insurance, it is helpful to examine its origins and structural intent. Dr. Marius Barnard, part of the team that performed the world's first human heart transplant, observed that while surgical techniques and medical treatments successfully kept patients alive after major cardiac events or cancer diagnoses, the financial costs of rehabilitation and inability to work pushed many into bankruptcy. Standard indemnity health insurance covers direct medical bills, but it rarely accounts for indirect financial shocks.
The core purpose of a dread disease policy is income protection and liquidity preservation during a medical crisis. Instead of reimbursing specific medical bills or requiring hospital invoices, a critical illness policy pays a predetermined, tax-free lump sum directly to the policyholder upon the formal diagnosis and verification of a covered condition. The insured individual retains complete autonomy over how these funds are spent. They can allocate the capital toward mortgage payments, hiring in-home nursing care, liquidating high-interest debt to reduce monthly obligations, or funding alternative medical treatments that standard insurance providers might deem experimental.
How Dread Disease Coverage Works: Mechanics and Definitions
The operational framework of a dread disease policy relies heavily on strict contractual definitions, waiting periods, and survival clauses. Unlike traditional health insurance, which involves continuous claims processing for various medical services, a critical illness policy is typically an all-or-nothing proposition for a specific event.
The Diagnosis and Verification Process
When a policyholder experiences symptoms and receives a diagnosis, triggering the policy payout requires navigating a rigorous verification protocol. The insurance provider's underwriting guidelines dictate exact clinical criteria that must be met. For example, a diagnosis of cancer generally requires microscopic confirmation of malignant cell growth and invasion of tissue, but certain early-stage or localized cancers—such as localized prostate cancer or in-situ melanoma—may be explicitly excluded or qualify for only a fractional payout. Similarly, a diagnosis of a heart attack (myocardial infarction) typically requires specific biochemical markers, such as elevated cardiac enzymes, alongside electrocardiographic changes.
Critical Policy Clauses
- Waiting Period (Qualifying Period): Most policies include an initial waiting period—often 30 to 90 days from the policy effective date—during which any diagnosis of a covered illness is excluded from coverage. This prevents individuals from purchasing policies after experiencing early symptoms.
- Survival Period: To qualify for the lump-sum payout, the insured person must typically survive for a specified duration following the formal diagnosis, commonly ranging from 14 to 30 days. This clause distinguishes critical illness coverage from life insurance.
- Pre-Existing Conditions: Policies universally scrutinize medical history. Conditions for which the insured received treatment, consultation, or advice within a specific look-back period prior to application are typically excluded, either permanently or for a defined duration.
Standard Coverage Scope and Common Exclusions
The breadth of conditions covered by a dread disease policy varies significantly depending on the insurer, the specific tier of the product, and regional regulatory frameworks. Basic policies typically cover the "big three" medical events that account for the vast majority of catastrophic health claims, while comprehensive plans may encompass dozens of distinct conditions.
| Condition Category | Commonly Covered Diagnoses | Typical Exclusions or Limitations |
|---|---|---|
| Cardiovascular | Heart attack, coronary artery bypass surgery, stroke, heart valve replacement. | Angioplasty with minor stent placement (unless specified as a graded benefit), mild arrhythmias. |
| Oncological | Invasive malignant cancers, leukemia, lymphoma. | Skin cancers (other than malignant melanomas), tumors classified as pre-malignant or non-invasive in-situ. |
| Neurological | Multiple sclerosis, Parkinson’s disease, Alzheimer’s disease, motor neuron disease. | Functional nervous disorders, psychiatric conditions, stress-related neurological symptoms. |
| Organ Failure | Major organ transplant, chronic kidney failure requiring dialysis. | Early-stage organ impairment that does not require surgical intervention or artificial support. |
Beyond these primary categories, advanced policies may cover severe burns, loss of sight, loss of speech, paralysis, and major head trauma. Conversely, almost all policies exclude illnesses resulting from self-inflicted injury, illegal acts, substance abuse, or acts of war.
Financial Considerations, Premiums, and Payout Structures
Evaluating the financial viability of a dread disease policy requires balancing the cost of premiums against the potential utility of the lump-sum benefit. Insurance carriers calculate premiums based on several risk factors, including the applicant's age at the time of purchase, tobacco use, family medical history, and the chosen benefit amount.
Premium Structures
- Level Premiums: Rates remain constant throughout the life of the policy or a specified term. While higher initially than step-rate options, they provide long-term budget predictability and protect against age-related rate spikes.
- Step-Rate (Renewable) Premiums: Rates start lower and increase incrementally each year or at defined age bands (e.g., every five years). This structure can become cost-prohibitive in later life stages when the statistical likelihood of illness increases.
Payout Configurations
- Lump-Sum Benefit: The traditional model, providing a single cash payment upon the first qualifying diagnosis, after which the policy may terminate.
- Multi-Stage or Graded Benefits: Modern policies often feature tiered payouts. For example, an early-stage cancer diagnosis might trigger a 25% advance payout, preserving the remaining 75% benefit for a future major medical event.
- Return of Premium Riders: An optional feature that refunds a portion or all of the cumulative premiums paid if the policyholder reaches a certain age or passes away without ever filing a critical illness claim. This adds substantial cost to the baseline premium.
Strategic Comparison: Dread Disease Insurance vs. Other Safety Nets
Consumers often confuse critical illness insurance with other forms of risk management, such as traditional health insurance, disability insurance, and life insurance. Each product serves a distinct function within a comprehensive financial plan.
[Standard Health Insurance] ---> Covers Direct Medical Bills (Doctors, Hospitals, Drugs) [Disability Insurance] ---> Replaces Lost Earned Income Due to Inability to Work [Dread Disease Insurance] ---> Provides Liquid Cash Lump-Sum for Out-of-Pocket Crisis Costs
While disability insurance replaces a percentage of monthly income regardless of the specific medical cause (as long as it prevents working), dread disease insurance pays out based strictly on the diagnosis of a named condition, even if the policyholder continues to work. Conversely, health insurance handles clinical billing directly with providers but offers no cash for non-medical expenses like home modifications, childcare, or debt elimination. Recognizing these operational boundaries helps prevent coverage overlaps and identifies genuine protection gaps.
Common Pitfalls and Mistakes to Avoid
Securing appropriate critical illness coverage requires careful attention to policy language to avoid unexpected claim denials or underinsurance.
- Underestimating the Required Benefit Amount: Selecting an arbitrary round number (e.g., a flat $50,000) without calculating actual ongoing living expenses, potential lost household income, and specialized medical costs can leave a family financially vulnerable. Financial planners often recommend aiming for an amount equal to one to two years of gross annual income.
- Ignoring Definition Nuances: Not all policies define specific illnesses identically. A policy definition for stroke that requires permanent neurological deficit lasting more than 30 days is significantly harder to satisfy than one requiring verifiable clinical evidence of neurological deficit at the time of diagnosis.
- Failing to Disclose Medical History: Non-disclosure or misrepresentation on the initial application—even if unintentional—gives the insurer legal grounds to rescind the policy or deny a claim during the contestability period. Complete transparency regarding past consultations and diagnostic tests is mandatory.
- Treating the Policy as an Investment: Policies featuring return-of-premium riders or cash-value accumulation often carry significantly higher premium costs. Evaluating whether those extra dollars would yield a higher return through traditional investment vehicles is a critical part of the decision-making process.
Frequently Asked Questions
What happens to a dread disease policy after it pays out a claim?
In most traditional single-event policies, once the full lump-sum benefit is paid following a qualifying diagnosis, the policy is fulfilled and terminates entirely. However, many modern policies feature multi-claim structures that allow for subsequent payouts for unrelated illnesses, provided specific waiting periods and category distinctions are met.
Is the payout from a critical illness policy taxable?
In many jurisdictions, if the policyholder purchases and pays for an individual critical illness policy using after-tax dollars, the resulting lump-sum benefit is received completely tax-free. Conversely, if an employer sponsors the plan and pays the premiums as a pre-tax benefit, the payout may be subject to ordinary income tax. Consulting a qualified tax professional regarding local tax laws is advised.
Can I purchase dread disease insurance if I have a pre-existing condition?
Purchasing a policy with a pre-existing condition is challenging. Insurers will typically either exclude that specific condition from coverage while covering all other listed illnesses, charge a higher premium (rated policy), or decline coverage altogether depending on the severity and recency of the condition.
How does a critical illness policy differ from a cancer-only policy?
A cancer-only policy provides benefits exclusively for the diagnosis of malignant neoplasms, whereas a dread disease or critical illness policy covers a broad spectrum of medical events, including cardiac, neurological, and organ-system failures. While cancer-only policies are generally less expensive, they offer a much narrower scope of financial protection.
Do I need critical illness insurance if I already have robust health and disability insurance?
Even with excellent health and disability coverage, many individuals face unique out-of-pocket expenses during a major medical crisis, such as out-of-network specialists, experimental treatments, or modifications to a home or vehicle. Critical illness insurance provides immediate, unconditional liquidity to address these specific expenses without depleting retirement savings.
Conclusion and Next Actions
Evaluating dread disease insurance requires an objective assessment of your family medical history, current financial safety net, and ability to absorb a sudden income shock or out-of-pocket medical expense. If existing emergency funds, health insurance, and disability policies adequately cover potential severe health crises, additional coverage may be unnecessary. However, for those with dependents, high fixed liabilities, or inadequate disability protections, a critical illness policy provides valuable financial insulation. Begin by reviewing current policy definitions, requesting quotes from reputable carriers, and consulting with a fee-only financial planner to determine the optimal coverage level for your specific circumstances.