Opening and managing an Individual Retirement Association (IRA) with Vanguard allows investors to build a long-term retirement portfolio utilizing low-cost index funds, exchange-traded funds (ETFs), and actively managed mutual funds. Vanguard offers both traditional and Roth IRAs, giving investors the flexibility to choose between tax-deferred growth or tax-free distributions in retirement, backed by the firm's investor-owned structure and renowned low expense ratios.
Understanding Vanguard IRA Accounts
Before committing funds to any financial institution, it is essential to understand the structural mechanics of the institution and the specific wrappers they offer. Vanguard is uniquely structured as client-owned, meaning that the mutual funds and ETFs within the platform ultimately own the company. This alignment of interests historically translates to downward pressure on fees, making Vanguard a foundational choice for cost-conscious long-term investors.
When examining retirement options, investors generally look at two primary types of individual accounts: the Traditional IRA and the Roth IRA. Both accounts share identical annual contribution limits set by the Internal Revenue Service (IRS), but they differ fundamentally in their tax treatment, distribution rules, and eligibility criteria.
Traditional IRA vs. Roth IRA at Vanguard
Choosing between a Traditional and Roth IRA depends heavily on your current tax bracket, anticipated tax bracket in retirement, and immediate need for tax deductions.
- Traditional IRA: Contributions may be tax-deductible in the year they are made, depending on your modified adjusted gross income (MAGI) and whether you or your spouse are covered by a workplace retirement plan like a 401(k). Investments grow tax-deferred, meaning you do not pay capital gains or dividend taxes as your portfolio compounds. Withdrawals taken in retirement are taxed as ordinary income.
- Roth IRA: Contributions are made with after-tax dollars and are never tax-deductible. However, the primary benefit is that investments grow entirely tax-free, and qualified withdrawals in retirement are completely tax-free. Furthermore, Roth IRAs do not force Required Minimum Distributions (RMDs) during the original owner's lifetime.
| Feature | Traditional IRA | Roth IRA |
|---|---|---|
| Tax Treatment of Contributions | Often tax-deductible (subject to income limits) | Never tax-deductible (made with after-tax dollars) |
| Growth of Investments | Tax-deferred | Tax-free |
| Tax Treatment of Withdrawals | Taxed as ordinary income | Tax-free (if qualified) |
| Required Minimum Distributions (RMDs) | Required starting at age 73 (per current SECURE 2.0 timelines) | Not required during the lifetime of the original owner |
| Early Withdrawal Penalties | 10% penalty plus ordinary income tax before age 59½ (with standard exceptions) | Contributions can be withdrawn anytime penalty-free; earnings subject to rules |
Eligibility and Contribution Requirements
To open and fund a Vanguard IRA, you must meet specific federal regulatory guidelines regarding earned income and age. Understanding these parameters prevents costly over-contribution penalties and ensures compliance with tax laws.
Income and Earned Income Prerequisites
The fundamental requirement for contributing to any IRA is having earned income. Earned income includes wages, salaries, tips, professional fees, bonuses, and other amounts received as compensation for services rendered. Passive income sources—such as rental income, interest, dividends, capital gains, or pension and annuity payments—do not qualify as earned income for IRA contribution purposes.
- Spousal IRA Rule: If you are married filing jointly and your spouse has little to no earned income, you can typically open and fund a "Spousal IRA" on their behalf, provided your combined compensation equals or exceeds the total contributions made to both accounts.
Current Contribution Limits
The IRS establishes annual contribution limits that apply across all of your traditional and Roth IRAs combined. For the 2026 tax year, the standard contribution limit is $7,000, with an additional catch-up contribution of $1,000 allowed for individuals who reach age 50 or older by the end of the calendar year.
It is vital to monitor these limits closely. If you contribute to multiple accounts across different brokerages, your cumulative contributions cannot exceed the statutory maximum.
Step-by-Step Guide: How to Open a Vanguard IRA
Setting up a retirement account digitally requires preparing specific personal documentation and following a structured enrollment workflow.
Prerequisites and Information Needed
Before navigating to the Vanguard platform, gather the following information to ensure a frictionless application process:
- Social Security Number (SSN) or Individual Taxpayer Identification Number (ITIN).
- Valid Residential Address (P.O. Boxes are generally restricted for primary verification).
- Employment Information (Employer name, address, and occupation status).
- Bank Account Details (Routing number and checking or savings account number for initial and ongoing funding).
Application Workflow
- Navigate to the Official Portal: Go to the official Vanguard website and select the "Open an account" or retirement products section.
- Select the Account Type: Choose between a Traditional IRA or a Roth IRA based on your tax planning strategy.
- Complete the Identity Verification (KYC): Enter your personal identification data. Vanguard utilizes secure verification databases to confirm your identity in compliance with federal anti-money laundering and Know Your Customer regulations.
- Establish Login Credentials: Create a secure username, a complex password, and set up multi-factor authentication (MFA) to protect your financial assets.
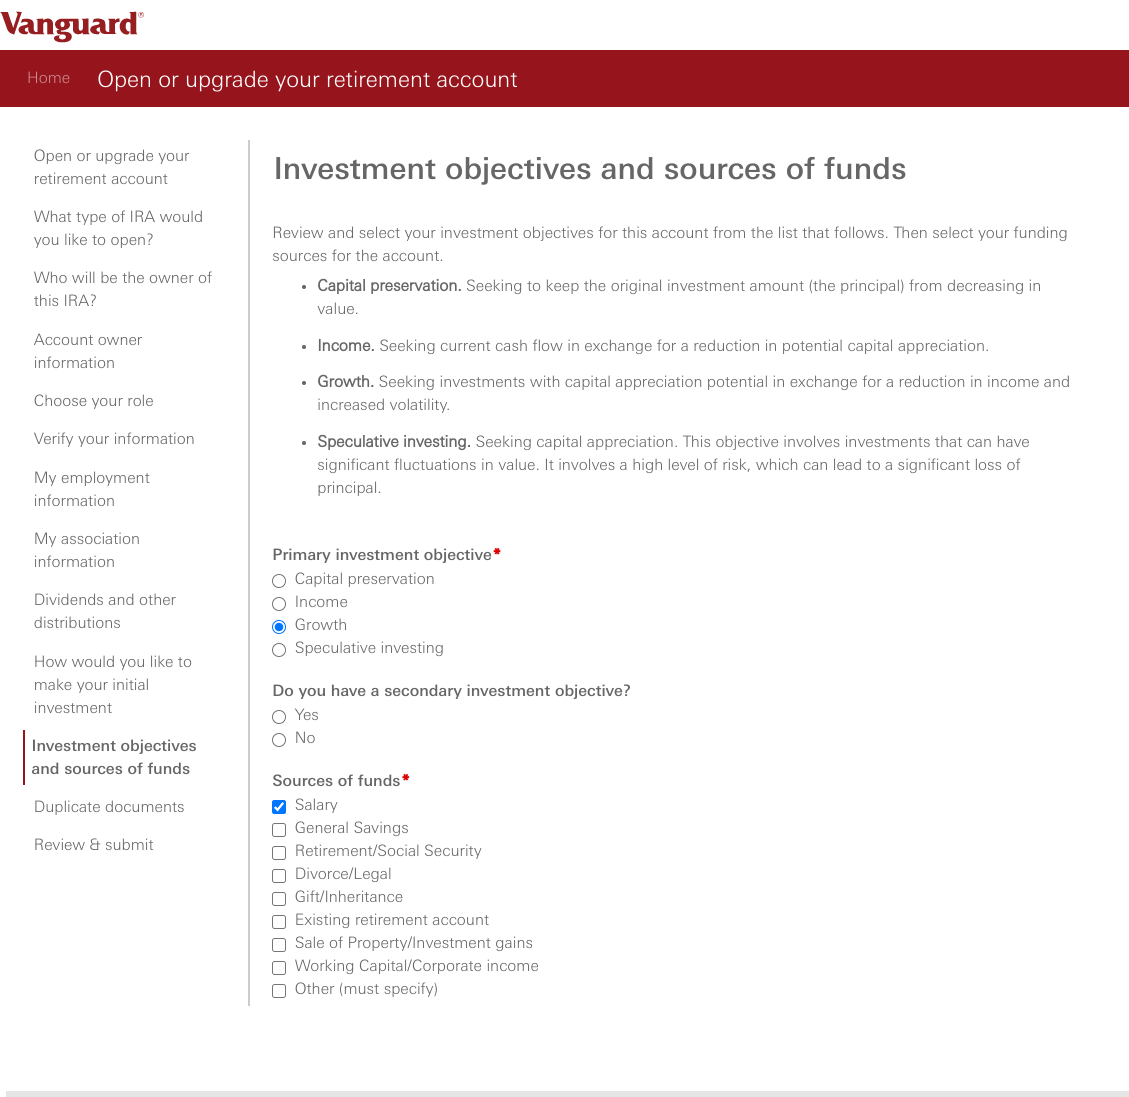
- Fund the Account: Link your external bank account via Automated Clearing House (ACH) transfer or initiate an electronic funds transfer. You can make a one-time contribution for the current or previous tax year (prior to the April tax filing deadline) or set up recurring monthly contributions.
Investment Options Available in a Vanguard IRA
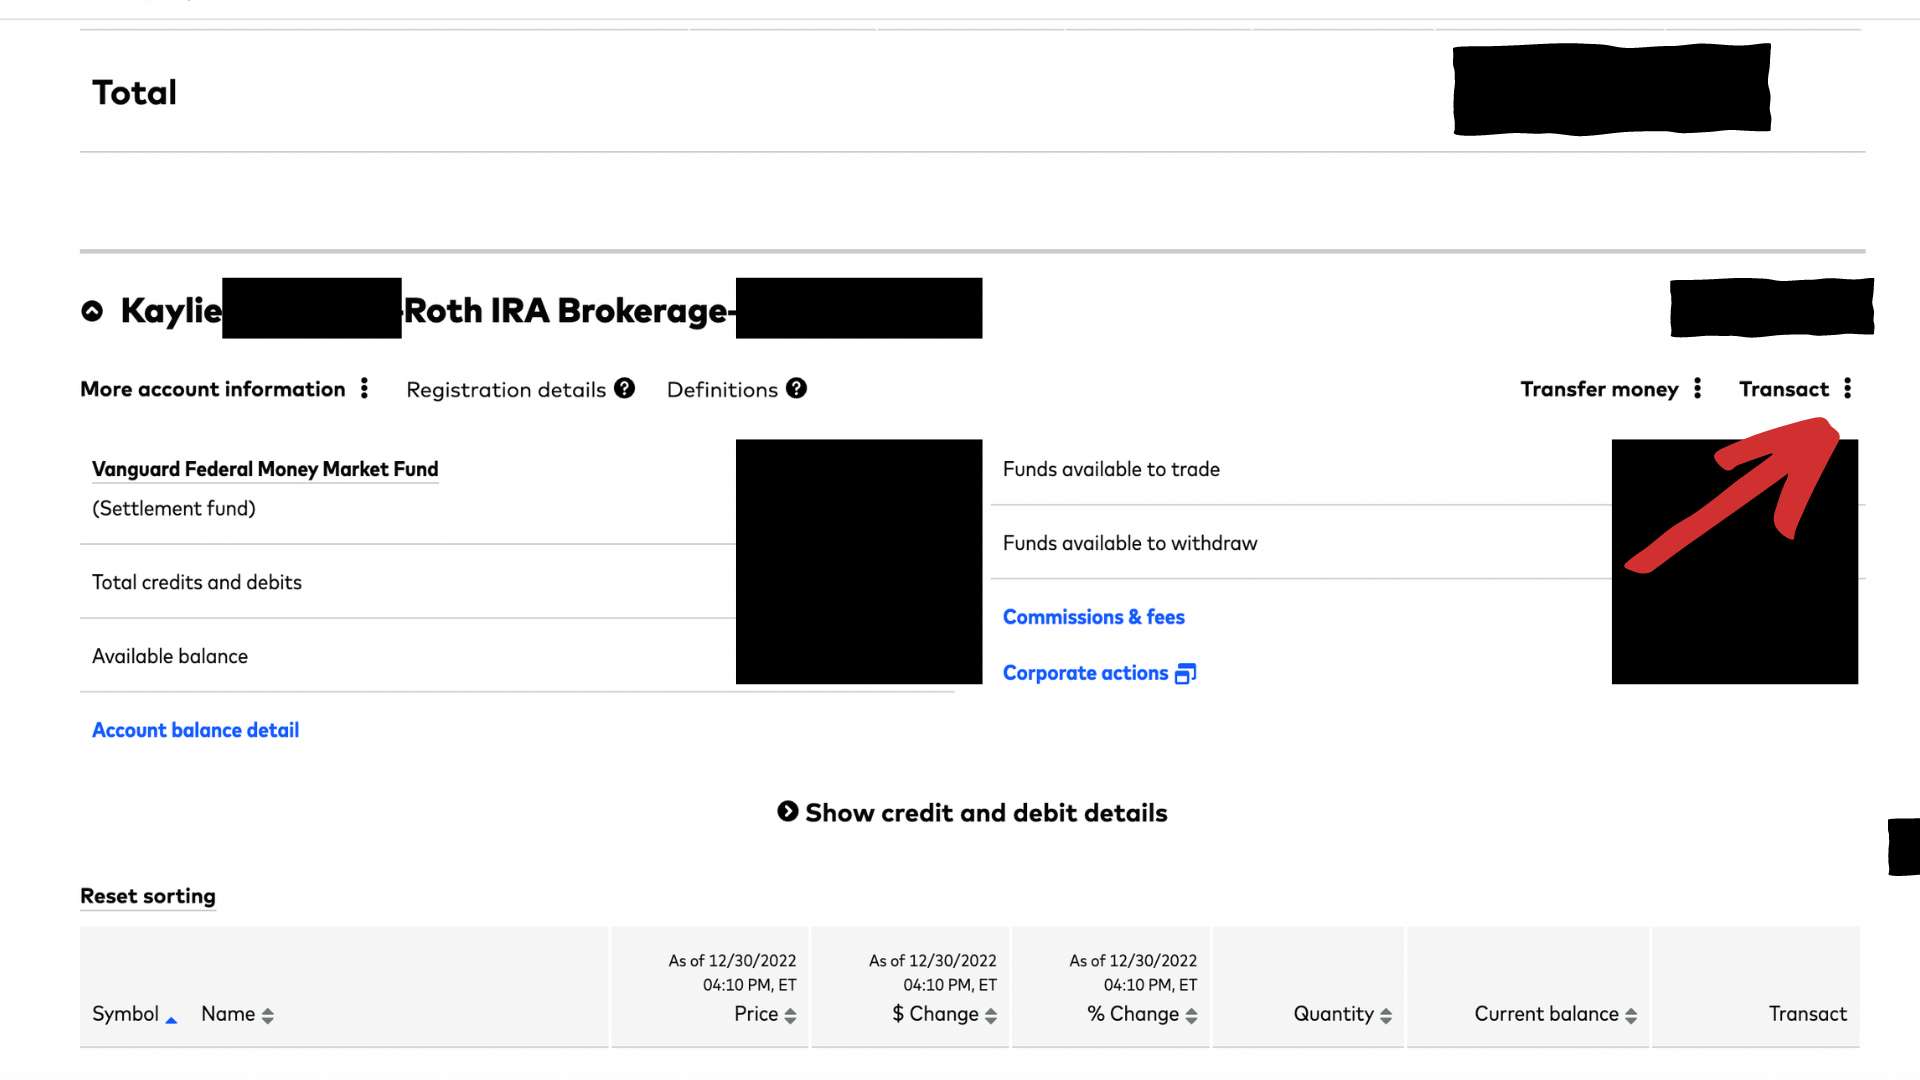
Once funds arrive in your Vanguard IRA settlement fund (such as the Vanguard Federal Money Market Fund), you must actively direct those dollars into specific investments. Vanguard provides several distinct asset classes and product categories tailored to different investor profiles.
Vanguard Mutual Funds and ETFs
Vanguard is globally recognized for pioneering low-cost index investing. Investors can choose from a vast array of index mutual funds and exchange-traded funds that track major benchmarks, such as the S&P 500, total stock market indexes, and international equity indexes.
- Broad-Market Index Funds: Funds like the Vanguard Total Stock Market Index Fund or Vanguard Total International Stock Index Fund provide instant diversification across thousands of global corporations.
- Sector and Specialty Funds: Investors seeking targeted exposure can allocate capital to specific sectors, such as real estate, healthcare, or technology.
Target-Retirement Funds
For investors who prefer a hands-off, automated approach, Vanguard Target Retirement Funds serve as all-in-one portfolios. When you select a target-retirement fund (e.g., Target Retirement 2055 Fund), the underlying asset allocation automatically adjusts over time—gradually shifting from an aggressive equity posture to a more conservative mix of bonds and cash equivalents as you approach and pass your targeted retirement date.
Brokerage Services and Individual Securities
Beyond proprietary Vanguard funds, the brokerage platform allows investors to purchase individual stocks, corporate and municipal bonds, certificates of deposit (CDs), and third-party ETFs, though transaction fees or commissions may apply to specific non-Vanguard assets.
Rollovers and Transfers: Moving Existing Retirement Accounts
Many investors encounter Vanguard IRAs when consolidating past retirement assets. Moving funds from an old employer-sponsored plan (such as a 401(k) or 403(b)) into a Vanguard IRA can simplify portfolio management and often unlock lower fee structures.
Direct Rollovers vs. Indirect Rollovers
- Direct Rollover (Recommended): The administrator of your old retirement plan sends the funds directly to Vanguard, either via an electronic transfer or a check made payable to Vanguard FBO (For Benefit Of) your name. This method avoids mandatory tax withholdings and eliminates the risk of missing strict IRS rollover windows.
- Indirect Rollover: The former custodian issues a check directly to you. You then have exactly 60 calendar days to deposit the full amount into a new or existing IRA. Failing to complete this transfer within 60 days can result in the entire distribution being treated as taxable income, alongside a potential 10% early withdrawal penalty.
Transfer of Assets (TOA)
If you already hold an IRA at another brokerage firm (such as Fidelity, Charles Schwab, or Merrill Lynch) and wish to move it to Vanguard, you initiate a Transfer of Assets. You complete a Vanguard TOA form, and Vanguard contacts your current institution to request a "in-kind" or cash transfer. An in-kind transfer moves your existing securities directly without forcing you to sell them, minimizing market timing risks and potential tax realizations.
Costs, Fees, and Expense Ratios
Understanding the fee structure of your retirement account is critical, as fees compound over decades and directly erode net investment returns.
Expense Ratios
Vanguard funds are famous for maintaining expense ratios significantly below the industry average. For example, broad-market index funds often feature expense ratios under 0.05% annually (meaning you pay less than $5 per year for every $10,000 invested). Always verify the specific expense ratio of any fund before executing a trade.
Account Maintenance and Service Fees
Vanguard has largely eliminated standard account maintenance fees for clients who opt-in to electronic delivery for statements and trade confirmations. However, certain specialized services, wire transfers, or outbound full-account transfers to other institutions may trigger nominal administrative fees. Review Vanguard's current fee schedule during account setup to ensure complete transparency.
Common Mistakes to Avoid
Managing an IRA requires strict adherence to federal tax codes and administrative timelines. Avoiding common missteps protects your financial standing and preserves your tax advantages.
- Exceeding Annual Contribution Limits: Accidentally contributing more than the statutory maximum triggers an excess contribution penalty of 6% per year on the excess amount until it is corrected. If you over-contribute, contact Vanguard customer service immediately to process a corrective distribution before tax filing deadlines.
- Neglecting Asset Allocation: Simply depositing cash into a Vanguard IRA settlement fund does not generate long-term growth. Cash holdings lose purchasing power to inflation over long horizons. Ensure your capital is actively invested in index funds, ETFs, or target-date portfolios that match your risk tolerance.
- Failing to Designate Beneficiaries: Neglecting to assign primary and contingent beneficiaries can force your IRA through prolonged probate proceedings upon your death, complicating estate planning and altering the distribution timelines mandated for heirs.
- Confusing Contribution Years: During the early months of the calendar year (January 1 through the April tax deadline), ensure you clearly specify whether your contribution applies to the prior tax year or the current tax year.
Frequently Asked Questions
Can I hold both a Traditional IRA and a Roth IRA at Vanguard simultaneously?
Yes, you can maintain both types of IRAs at Vanguard. However, remember that the annual statutory contribution limit applies to your total contributions across all IRAs combined, not per account. You cannot contribute the maximum limit to a Traditional IRA and the maximum limit to a Roth IRA in the same tax year unless combined contributions stay within the federal cap.
What is the minimum initial investment required to open a Vanguard IRA?
Most Vanguard mutual funds carry minimum initial investment requirements ranging from $1,000 to $3,000, though specific flagship or specialized institutional shares may require higher thresholds. Conversely, Vanguard ETFs can be purchased for the price of a single share, making them highly accessible for investors starting with smaller initial balances.
How do I initiate a Backdoor Roth IRA strategy at Vanguard?
A "Backdoor Roth" is a strategy utilized by high-income earners whose earnings exceed the direct Roth IRA contribution limits. It involves making a non-deductible contribution to a Traditional IRA and subsequently converting those funds into a Roth IRA. To execute this at Vanguard, you open both accounts, fund the Traditional IRA with non-deductible cash, and initiate a Roth conversion request online or via phone. Note: Consult a certified tax professional before executing backdoor strategies to navigate the IRS pro-rata rule correctly.
Are Vanguard IRA investments insured by the FDIC?
No. Mutual funds, ETFs, and individual stocks and bonds held within a Vanguard brokerage account are not insured by the Federal Deposit Insurance Corporation (FDIC). Instead, cash balances held in the settlement fund may be protected by FDIC insurance up to statutory limits via partner banks, while securities are protected against brokerage failure by the Securities Investor Protection Corporation (SIPC) up to $500,000 (including a $250,000 limit for cash). SIPC does not protect against normal market losses.
What happens to my Vanguard IRA if I move to another country?
If you expatriate or move permanently overseas, your ability to make new contributions to a Vanguard IRA may be restricted based on your residency status and local tax treaties. While existing holdings can typically remain within the account, Vanguard enforces specific compliance rules regarding foreign addresses, and certain account functions may require additional identity verification or restriction of non-resident transactions.
Next Actions and Implementation
To successfully establish or optimize your retirement planning path with Vanguard, follow these prioritized next steps:
- Assess Your Tax Situation: Determine whether a Traditional IRA (immediate tax deduction) or a Roth IRA (tax-free retirement income) aligns better with your current financial bracket and long-term tax expectations.
- Gather Documentation: Secure your Social Security number, banking details, and employment history.
- Complete the Digital Application: Visit the official Vanguard portal to open and fund your chosen account.
- Deploy Capital: Select diversified, low-cost index funds, ETFs, or an automated target-retirement fund to ensure your money is actively working toward your retirement goals.