Payfort, a prominent payment processing entity in the MENA region, is now integrated into the Amazon Payment Services infrastructure. Businesses utilizing Payfort technology benefit from a robust suite of payment processing tools designed to handle multi-currency transactions, fraud detection, and localized payment methods. This guide clarifies the transition, current operational status, and essential considerations for merchants managing their payment infrastructure within this ecosystem.
Understanding the Evolution of Payfort
To understand the current functionality of "payfort com," it is necessary to recognize its history as an independent payment service provider (PSP) and its subsequent acquisition. Originally founded to bridge the gap in secure online payment processing across the Middle East and North Africa, Payfort provided merchants with the ability to accept credit cards, debit cards, and local payment methods via a unified interface.
In 2017, Amazon acquired Souq.com, which included Payfort as a core component of its financial services technology. By 2020, the brand officially transitioned to operate as Amazon Payment Services. Consequently, for any organization or developer searching for "payfort com," it is important to note that the domain and services have been migrated into the Amazon Payment Services umbrella. The infrastructure, API documentation, and support systems are now managed under this corporate framework. Merchants seeking to integrate these services must now interface with the Amazon Payment Services portals to access the legacy features that were formerly exclusive to the Payfort brand.
Core Services and Technical Capabilities
The primary function of the platform is to facilitate secure financial transactions between merchants and their customers. The technical depth of the system remains tailored toward e-commerce enterprises, service providers, and digital platforms that require high-availability payment gateways.
Payment Processing and Integration
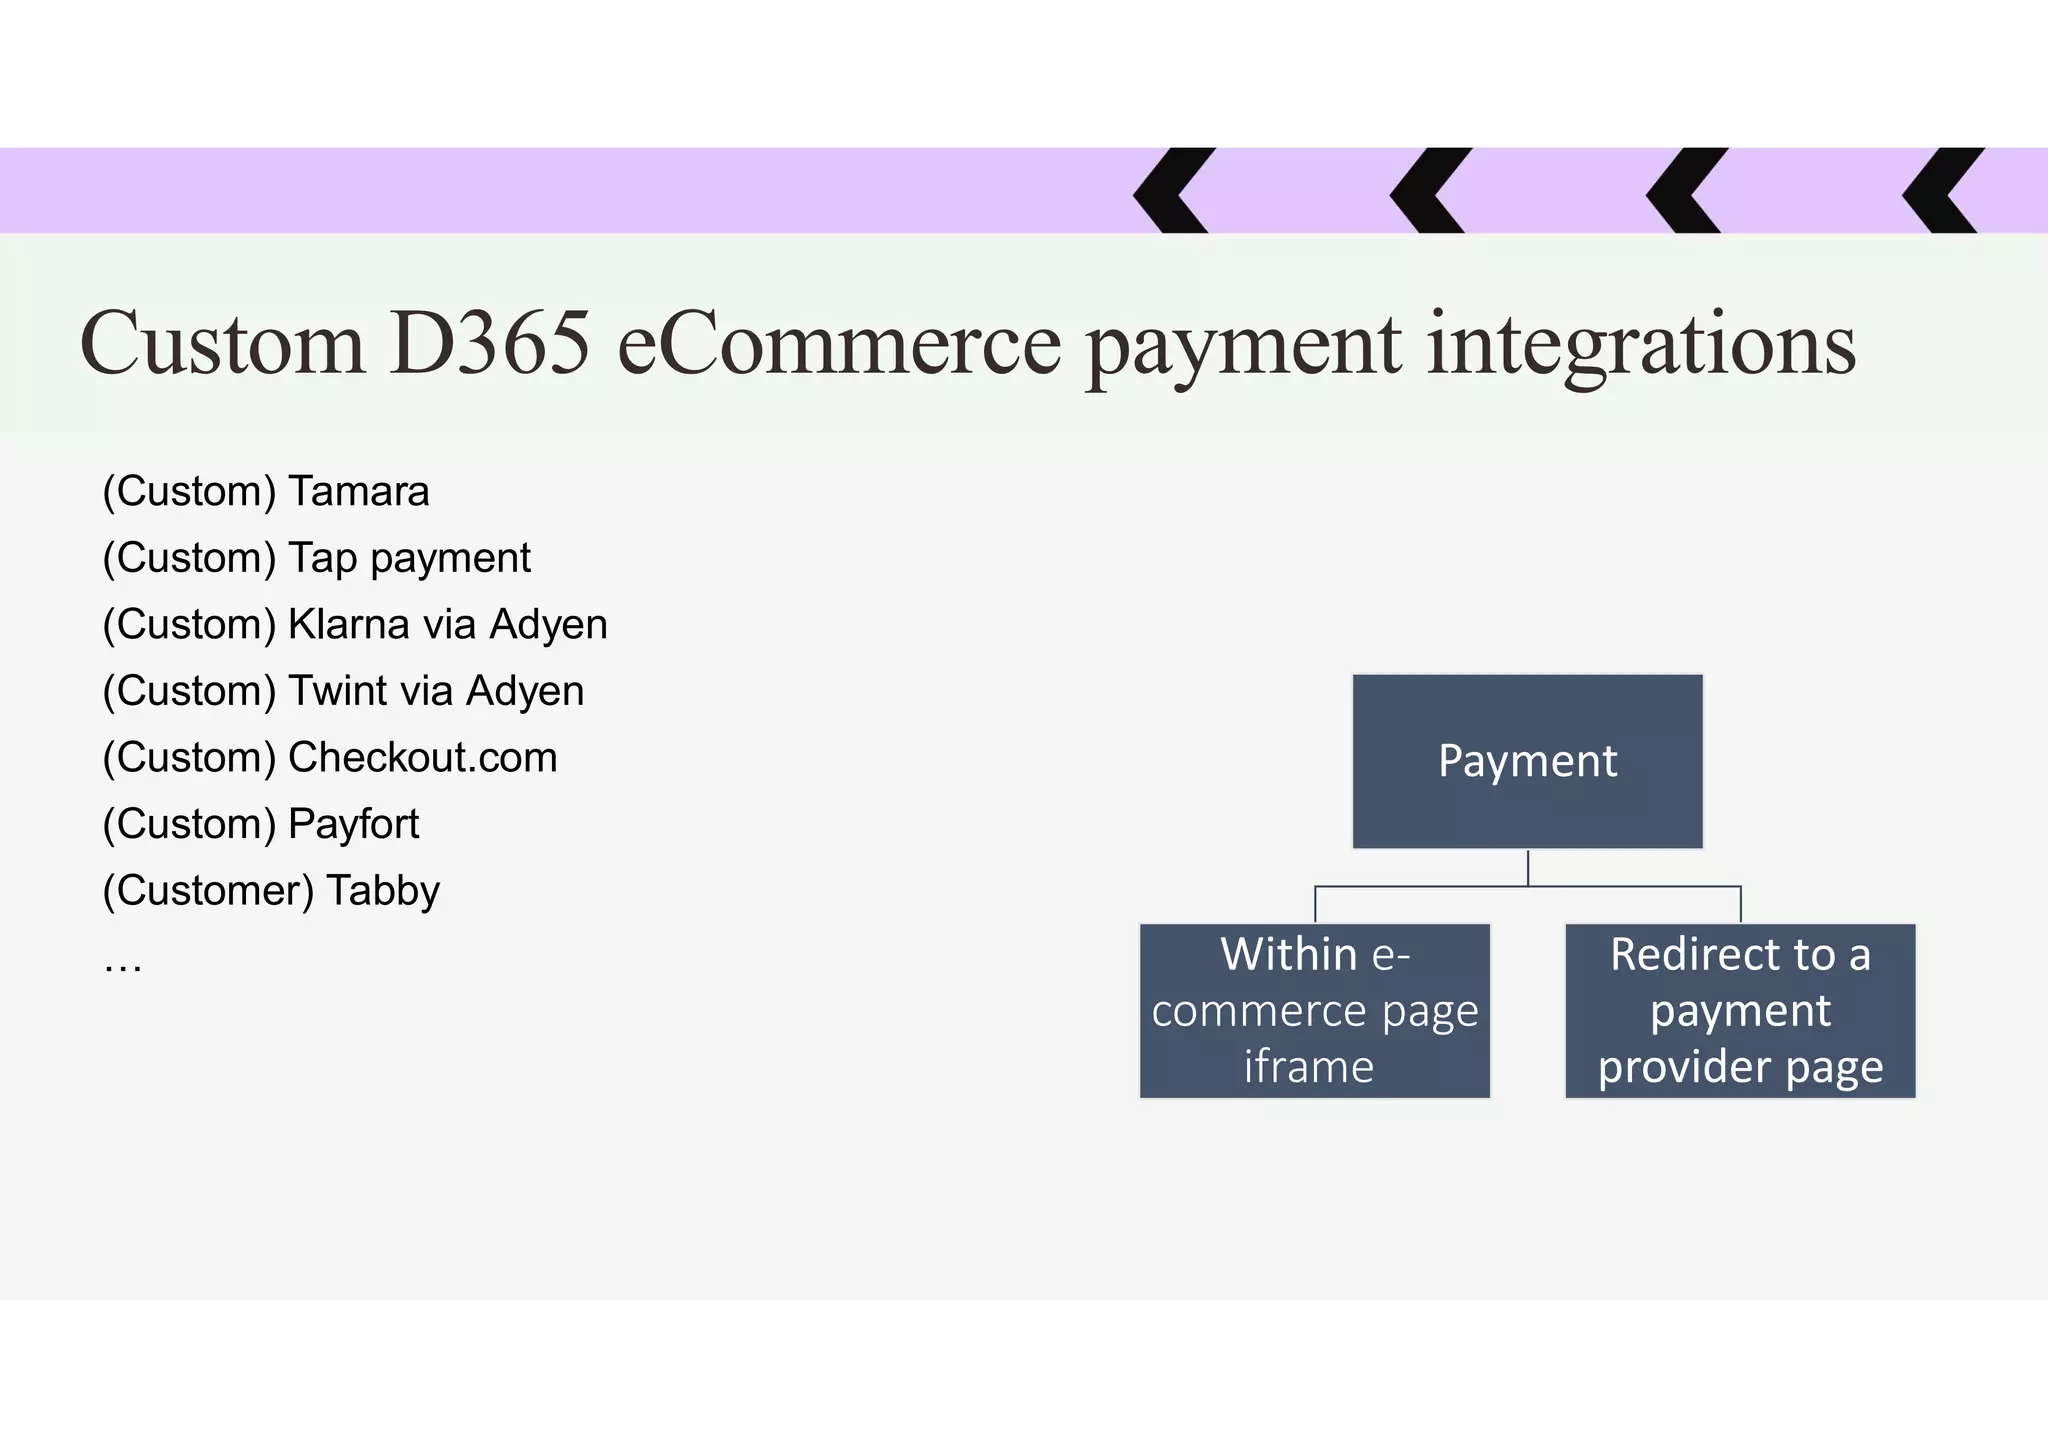
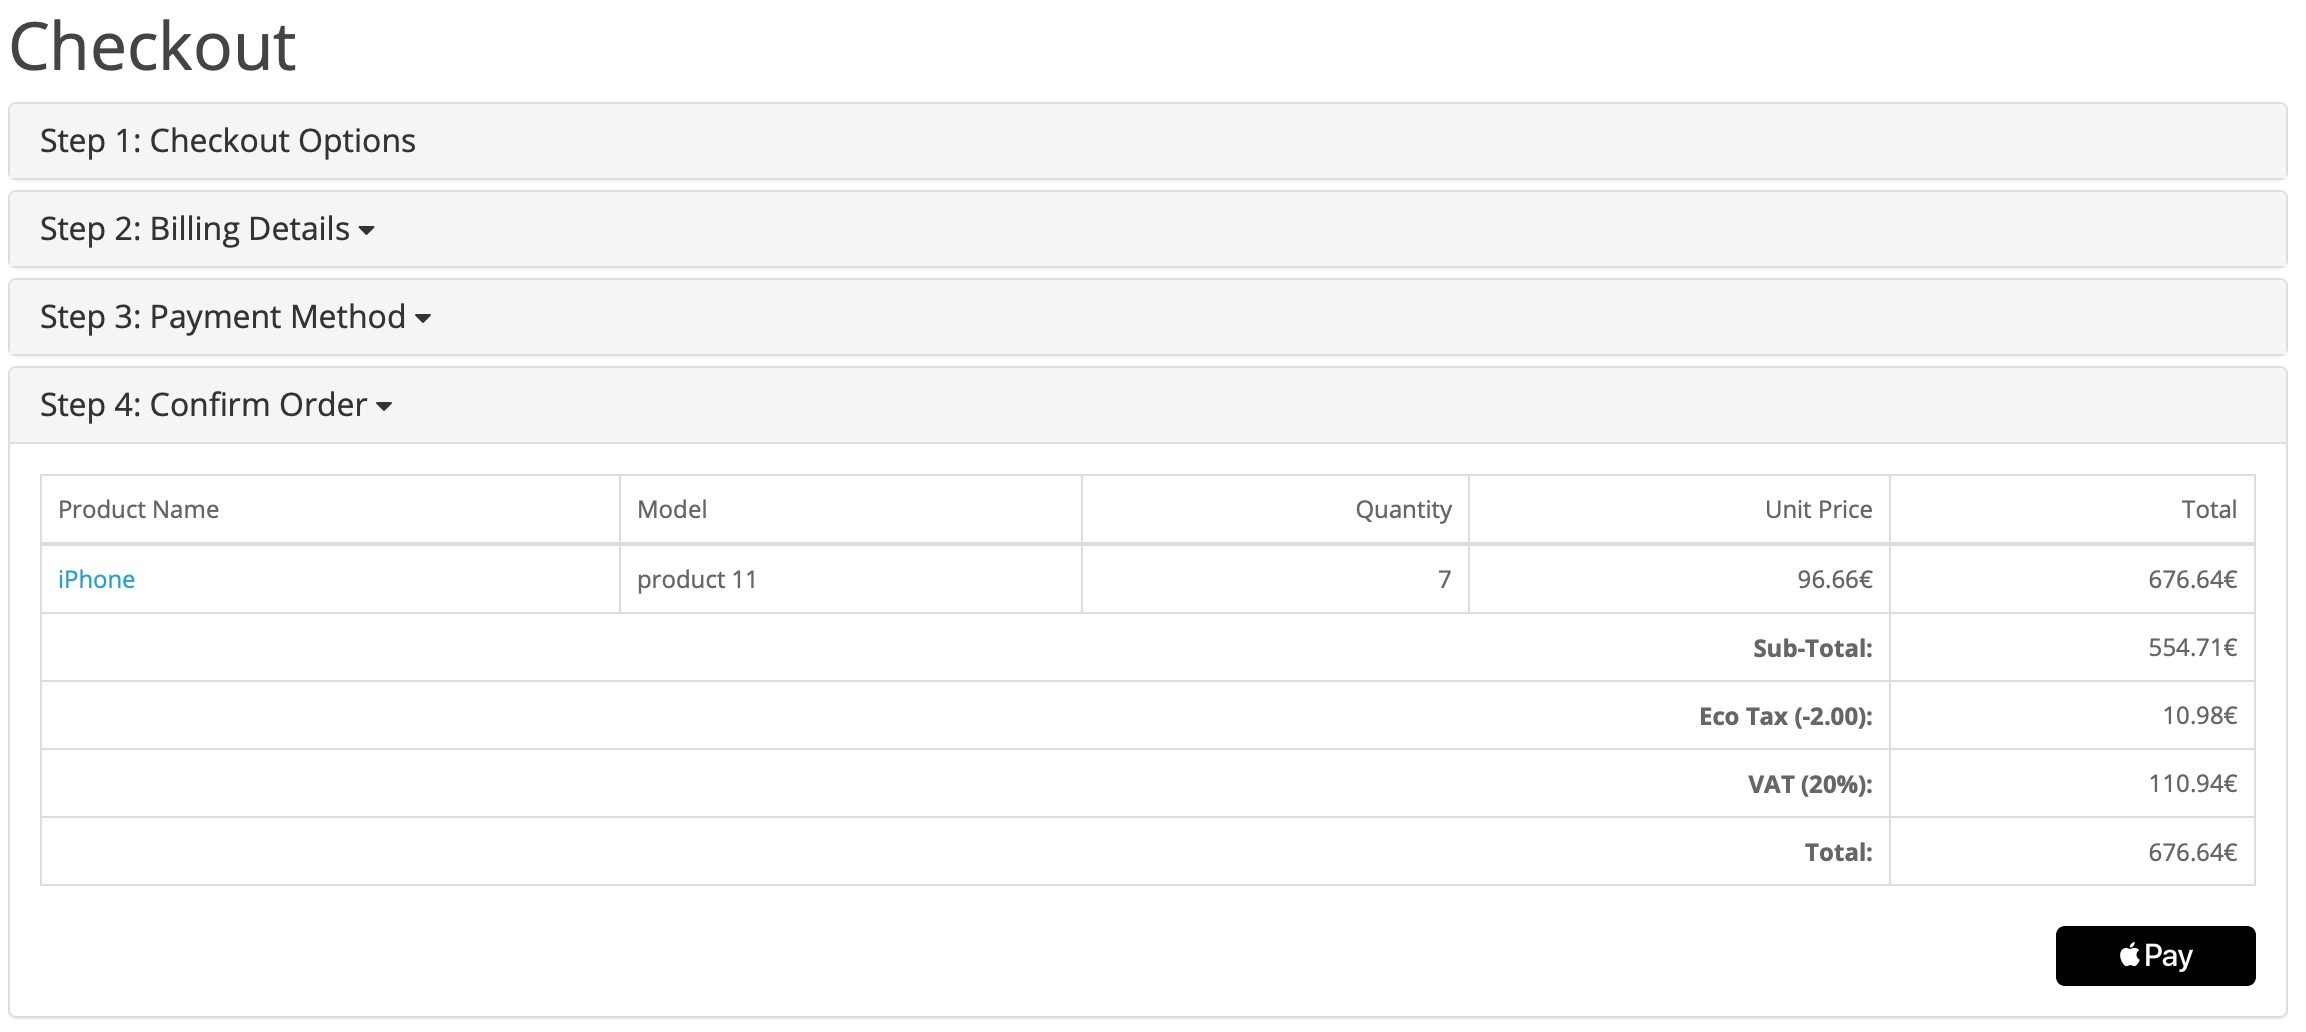
The platform supports a variety of integration methods, including Hosted Payment Pages (HPP) and direct API integration. Hosted solutions are ideal for businesses looking to reduce their Payment Card Industry Data Security Standard (PCI DSS) compliance burden, as the sensitive card data input occurs on a secure page hosted by the provider. Direct API integration, conversely, allows merchants full control over the checkout user interface, though this requires more rigorous adherence to security standards and infrastructure audits.
Fraud Protection and Security
A significant feature inherited from the Payfort legacy is the Fort Fraud Shield. This system uses machine learning and rule-based logic to analyze transactions in real-time. By evaluating behavioral data, IP geolocation, and transaction velocity, the system identifies potentially fraudulent activities before they are finalized. This is crucial for merchants operating in regions where digital payment fraud risks can fluctuate.
Multi-Currency and Localization
A major factor in the popularity of the original Payfort service was its deep integration with regional banking infrastructures. This includes support for various local payment methods (such as Mada in Saudi Arabia or KNET in Kuwait) and the ability to settle transactions in multiple currencies. For businesses scaling across the GCC (Gulf Cooperation Council) region, the platform provides the necessary liquidity and regional banking connectivity to ensure settlements are processed efficiently.
Technical Prerequisites for Merchants
Before attempting to connect to the payment ecosystem, organizations must ensure they meet specific legal and technical requirements. Because the platform facilitates financial movement, the onboarding process is strictly regulated.
- Legal Entity Verification: Merchants must provide valid commercial registration documents for the jurisdiction in which they operate.
- PCI DSS Compliance: Regardless of the integration method, a baseline level of security infrastructure is required. If storing, processing, or transmitting card data directly, merchants must undergo an annual audit to demonstrate compliance.
- Bank Account Requirements: The merchant must hold a valid corporate bank account in the region supported by the service. Settlement timelines and fees are contingent upon the banking agreement established during the onboarding phase.
- Technical Environment: The merchant’s website or mobile application must feature a valid SSL certificate. Furthermore, the development team must be capable of handling server-to-server communication using standard RESTful API protocols.
Comparison of Payment Integration Options
Choosing the right integration path depends on the merchant’s technical capacity and desired level of control over the user experience.
| Feature | Hosted Payment Page | API Integration |
|---|---|---|
| Control over UI | Limited (Customizable styles only) | Full (Custom design) |
| PCI DSS Scope | Lower (Service provider handles data) | Higher (Merchant infrastructure involved) |
| Development Time | Short (Rapid deployment) | Long (Extensive coding/testing) |
| Customization | Basic Branding | High (Deep integration) |
Operational Challenges and Troubleshooting
Managing payment gateways requires consistent monitoring of transaction success rates and system health. Merchants often encounter common issues related to network timeouts, incorrect API configurations, or transaction declines due to banking restrictions.
Handling Declined Transactions
Transactions are typically declined due to insufficient funds, expired cards, or the bank’s internal security triggers. When a decline occurs, the API returns a response code. It is essential for developers to parse these codes correctly and present user-friendly error messages rather than raw system error strings.
API Versioning and Updates
As the infrastructure is part of a larger ecosystem, API endpoints and security protocols are updated periodically. Merchants must monitor official communication channels for deprecated endpoints. Hard-coding API versions without a plan for updates is a common mistake that can lead to sudden service outages during platform maintenance or security upgrades.
Testing and Sandbox Environments
Before moving to production, merchants must utilize the provided sandbox environment. This environment mirrors the production API but uses test card credentials. Developers should perform end-to-end testing, including edge cases such as partial refunds, voided transactions, and currency conversions, to ensure the backend logic can handle diverse outcomes.
Frequently Asked Questions
Is Payfort still an active brand for new sign-ups? No. Payfort has been integrated into Amazon Payment Services. New merchants must apply for services directly through the Amazon Payment Services portal, as the legacy "payfort com" systems are fully transitioned.
Does the service handle currency exchange automatically? Yes, the platform supports multi-currency processing. The exchange rates used are typically determined by the underlying banking settlement agreements and can be configured through the merchant dashboard.
What is the role of the Fort Fraud Shield? The Fort Fraud Shield acts as a risk mitigation layer. It evaluates transactions based on hundreds of data points to block suspicious activity, reducing the rate of chargebacks and protecting the merchant from financial loss.
How do I handle PCI compliance if I use their services? If using the Hosted Payment Page, the provider assumes the bulk of the PCI burden. However, you must still maintain a secure web environment and complete the relevant Self-Assessment Questionnaire (SAQ) required by your acquiring bank.
Can I integrate these services into a custom mobile application? Yes, the platform provides mobile SDKs (Software Development Kits) for iOS and Android, which allow developers to integrate the payment flow directly into native mobile applications without redirecting users to a web browser.
Strategic Next Steps for Merchants
For businesses currently evaluating their payment gateway infrastructure, the transition of legacy platforms into established global ecosystems provides both opportunities and requirements.
- Audit Your Integration: If you are using legacy codebases that still reference old Payfort libraries, prioritize an audit of your API calls. Migrate to the current Amazon Payment Services SDKs to ensure you are receiving the latest security patches and feature updates.
- Optimize the Checkout Flow: Use the provided analytics dashboards to monitor cart abandonment rates specifically during the payment step. High abandonment can indicate that the checkout page is not rendering correctly on certain mobile devices or that the payment options displayed do not align with user expectations.
- Review Settlement Procedures: Frequently verify that your settlement reports match your internal ledger. Discrepancies should be addressed through the merchant support ticketing system immediately to prevent reconciliation errors at the end of the fiscal year.
- Security Maintenance: Stay informed on PCI DSS updates. As security standards evolve in 2026 and beyond, ensure your server-side configurations for TLS (Transport Layer Security) protocols meet the minimum requirements requested by your payment processor.
By focusing on these operational areas, merchants can ensure that their payment processing remains robust, secure, and aligned with the expectations of a modern digital economy.