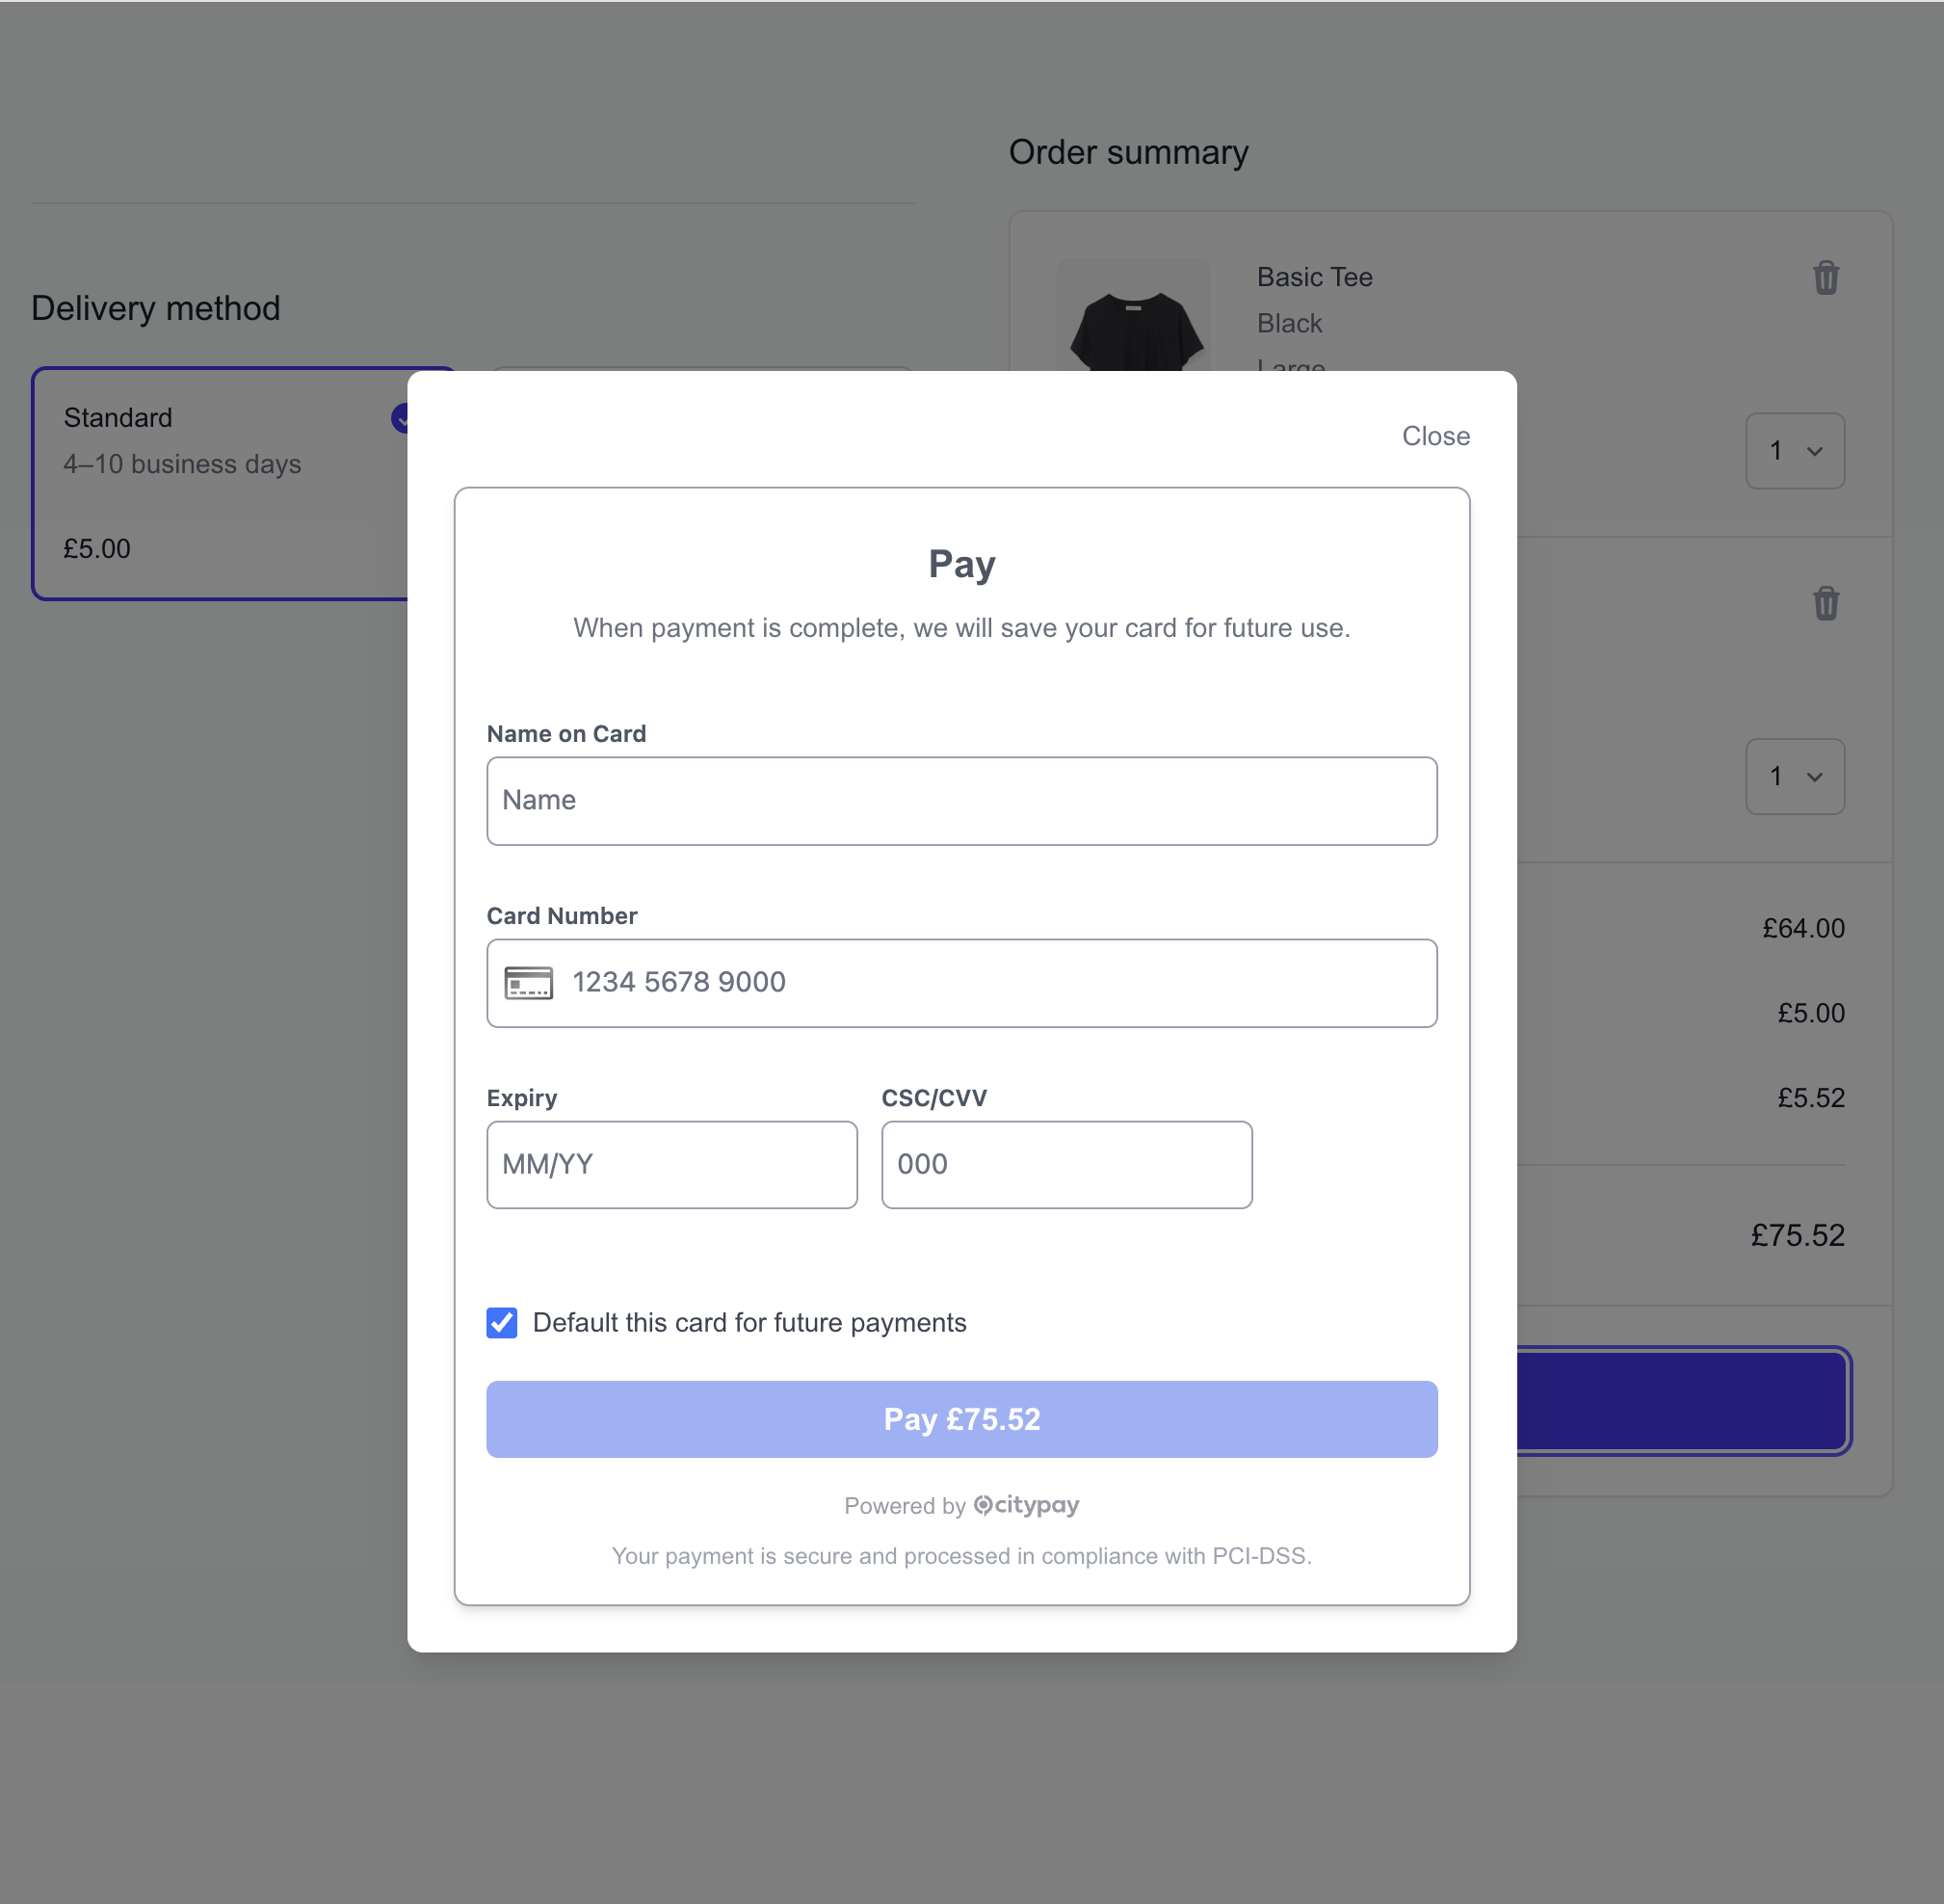
CityPay New represents a modern evolution in digital payment processing, designed to streamline transactions for businesses, municipalities, and service providers. This platform bridges traditional point-of-sale systems with advanced gateway architectures, enabling secure transactions, simplified reconciliation, and enhanced user experiences across web and mobile interfaces.
Understanding the CityPay New Payment Ecosystem
The digital payment landscape demands high availability, robust security frameworks, and seamless integration capabilities. CityPay New addresses these needs by combining legacy reliability with modern cloud-native processing infrastructure. Understanding how the system operates requires an analysis of its core architectural components, transactional workflows, and administrative controls.
At its core, the platform serves as an intermediary between the merchant, the customer, and the acquiring financial institutions. When a user initiates a transaction, CityPay New encrypts sensitive financial data, routes the authorization request through secure payment rails, and returns real-time responses. This reduces latency and minimizes transaction drop-off rates, which is crucial for high-volume service portals and municipal utility payment systems.
Core Architectural Improvements
Compared to older iterations, the new infrastructure introduces several performance optimizations:
- API-First Design: Built on RESTful principles, allowing developers to integrate payment widgets, hosted checkout pages, or custom applications with minimal friction.
- Tokenization Engines: Replaces sensitive cardholder data with unique tokens, reducing compliance burdens associated with the Payment Card Industry Data Security Standard (PCI-DSS).
- Adaptive Routing: Automatically selects the most cost-effective and reliable acquiring bank path to maximize authorization success rates.
- Real-Time Webhooks: Delivers instant transaction status updates to backend databases, preventing inventory or service provisioning discrepancies.
Eligibility, Prerequisites, and Merchant Onboarding
Implementing CityPay New requires meeting specific technical, financial, and legal prerequisites. Whether deploying the platform for a private enterprise or a public sector agency, organizations must complete a structured onboarding verification process before processing live funds.
Technical Prerequisites
Before initiating integration, technical teams must ensure their environment meets baseline operational standards:
- SSL/TLS Certification: All endpoints communicating with the payment gateway must utilize secure HTTPS protocols with valid certificates.
- IP Whitelisting: Depending on the integration tier, administrative servers may need static IP configurations registered with the gateway provider.
- Development Environment: Access to sandbox credentials for testing application programming interface (API) calls, error handling, and webhook listeners.
- Data Storage Compliance: Ensuring that backend systems do not store unencrypted primary account numbers (PAN) or card verification values (CVV2).
Onboarding and Verification Steps
The onboarding workflow involves compliance checks to prevent fraud and satisfy anti-money laundering (AML) regulations.
- Corporate Identity Verification: Submission of official business registration documents, tax identification numbers, and authorized representative credentials.
- Underwriting Review: Risk assessment conducted by financial partners to evaluate transaction volumes, chargeback histories, and business models.
- Merchant Category Code (MCC) Assignment: Correctly classifying the organization to determine applicable interchange fees and regulatory requirements.
- Contract Execution: Signing service level agreements (SLAs) and processing pricing schedules.
Integration Methods and Deployment Options
CityPay New offers multiple integration pathways to accommodate varying technical resources and business requirements. Choosing the correct method depends on security requirements, brand consistency goals, and internal development capacity.
| Integration Method | Technical Complexity | PCI-DSS Scope | Best Suited For |
|---|---|---|---|
| Hosted Checkout Fields | Low | Lowest (SAQ A) | Small businesses, rapid deployment |
| Embedded JavaScript Widgets | Moderate | Low (SAQ A) | E-commerce stores wanting custom branding |
| Direct API Integration | High | Highest (SAQ D) | Large enterprises with custom checkout flows |
| Virtual Terminal | None | Managed by Vendor | Call centers, mail-order/telephone-order (MOTO) |
Hosted Checkout Implementation
For organizations seeking to minimize PCI-DSS compliance scope, hosted solutions redirect users to a secure, PCI-compliant payment page managed entirely by the gateway. Alternatively, embedded form fields load secure input frames directly onto the merchant's checkout page while keeping sensitive data isolated from the merchant's server.
Direct API Integration
Enterprise deployments often require direct server-to-server API calls. This approach gives developers total control over the user interface and transaction workflow. However, it places the primary responsibility for security compliance on the merchant, requiring rigorous vulnerability scanning and adherence to strict data protection standards.
Transaction Management, Fees, and Reconciliation
Effective financial administration requires clear visibility into transaction statuses, fee structures, and daily settlement reports. CityPay New provides a centralized merchant dashboard designed to simplify these operational tasks.
Fee Structures and Cost Considerations
Payment processing costs typically comprise several distinct components:
- Interchange Fees: Set by card networks (such as Visa or Mastercard) and paid to the card-issuing bank.
- Scheme Fees: Direct charges levied by the payment networks for utilizing their infrastructure.
- Gateway / Processing Markup: The fee charged by CityPay New for routing, authorization, and platform maintenance.
Organizations must review their merchant agreements to understand whether fees are assessed on a flat-rate model, interchange-plus model, or tiered pricing structure. Interchange-plus pricing generally offers greater transparency for high-volume processors.
Daily Reconciliation Workflows
Reconciling gateway reports with bank deposits is critical for identifying discrepancies, chargebacks, and uncaptured funds. CityPay New generates automated settlement files (such as CSV or XML formats) that can be imported directly into enterprise resource planning (ERP) systems. Financial teams should verify that the gross transaction total minus applicable fees matches the net deposit appearing in the operating bank account.
Security, Fraud Prevention, and Compliance
Protecting sensitive financial data is a foundational requirement for any payment gateway. CityPay New incorporates multi-layered security controls designed to detect fraudulent activity and safeguard user privacy.
Fraud Mitigation Tools
- Address Verification System (AVS): Compares the billing address provided by the customer with the address on file at the card-issuing bank.
- Card Verification Value (CVV/CVC) Checks: Validates the three- or four-digit security code printed on the physical card.
- Velocity Checks: Monitors transaction frequency from specific IP addresses, device fingerprints, or card numbers to flag automated bot attacks or card-testing schemes.
- 3 Secure (3DS) Authentication: Redirects users to an authentication challenge page hosted by their bank, adding an extra layer of verification for online purchases.
Regulatory Compliance
Adherence to regulatory frameworks is mandatory. Beyond PCI-DSS compliance, platforms operating in specific regions must comply with regional data protection acts, such as the General Data Protection Regulation (GDPR) in Europe or local consumer financial protection laws. Merchants are responsible for ensuring their privacy policies clearly state how customer payment data is handled, retained, and protected.
Troubleshooting Common Integration and Transaction Errors
Even with robust architecture, technical issues and transaction declines can occur. Maintaining system reliability requires a structured approach to identifying and resolving errors quickly.
Common Error Categories
- Authentication Failures: Incorrect API keys, expired authorization tokens, or unauthorized IP addresses attempting to access gateway endpoints.
- Decline Codes: Responses from issuing banks indicating insufficient funds, expired cards, or suspected fraud. Developers should map these codes to user-friendly messages rather than displaying raw technical errors.
- Webhook Delivery Failures: Situations where the gateway cannot reach the merchant's endpoint to deliver a transaction status update. Implementing exponential backoff retry logic on the server side helps mitigate missed webhooks.
- Timeout Errors: Network latency or server overloads causing transaction requests to hang. Implementing idempotent API requests ensures that retrying a timed-out transaction does not result in double-charging the customer.
Frequently Asked Questions
What is the primary difference between legacy payment gateways and CityPay New?
CityPay New utilizes a modern cloud-native, API-first architecture designed for faster response times, enhanced tokenization security, and improved mobile responsiveness compared to older legacy systems.
How does CityPay New reduce PCI-DSS compliance burdens for merchants?
By utilizing hosted checkout pages or embedded secure iframes, sensitive cardholder data bypasses the merchant's servers entirely, significantly reducing the scope of required PCI-DSS self-assessment questionnaires.
What should I do if a webhook notification fails to deliver?
Check your server logs to ensure your endpoint is reachable and returning a 200 OK status response. CityPay New typically retries failed webhook deliveries automatically using an exponential backoff schedule.
Are multi-currency transactions supported by the platform?
Yes, the platform supports multi-currency processing, allowing businesses to accept payments in various global currencies while settling funds in their primary local bank account, subject to applicable exchange rates and conversion fees.
How long do standard transaction settlements take to reach the bank account?
Standard settlement timeframes depend on the acquiring bank and the merchant agreement, typically ranging from one to three business days following the transaction capture date.
Practical Next Actions
To begin utilizing CityPay New effectively, review your organization's technical requirements and contact the platform's onboarding team to establish a sandbox account. Conduct thorough end-to-end testing of your checkout flow, verify your error-handling procedures, and confirm that your administrative team is familiar with the daily reporting and reconciliation dashboard before launching live payment processing.