Fifth Third Bank interest rates dictate the returns you earn on savings and certificates of deposit, as well as the costs associated with borrowing through mortgages and loans. Understanding these rates helps you manage your personal finances, maximize deposit yields, and minimize debt expenses in the current economic environment.
Introduction to Fifth Third Bank Interest Rates
Navigating the financial landscape requires a clear understanding of how traditional national banks structure their interest rates across various products. Fifth Third Bank, operating extensively across the Midwestern and Southeastern United States, offers a diverse suite of financial products, including standard savings accounts, interest-bearing checking accounts, Certificates of Deposit (CDs), money market accounts, and consumer loans.
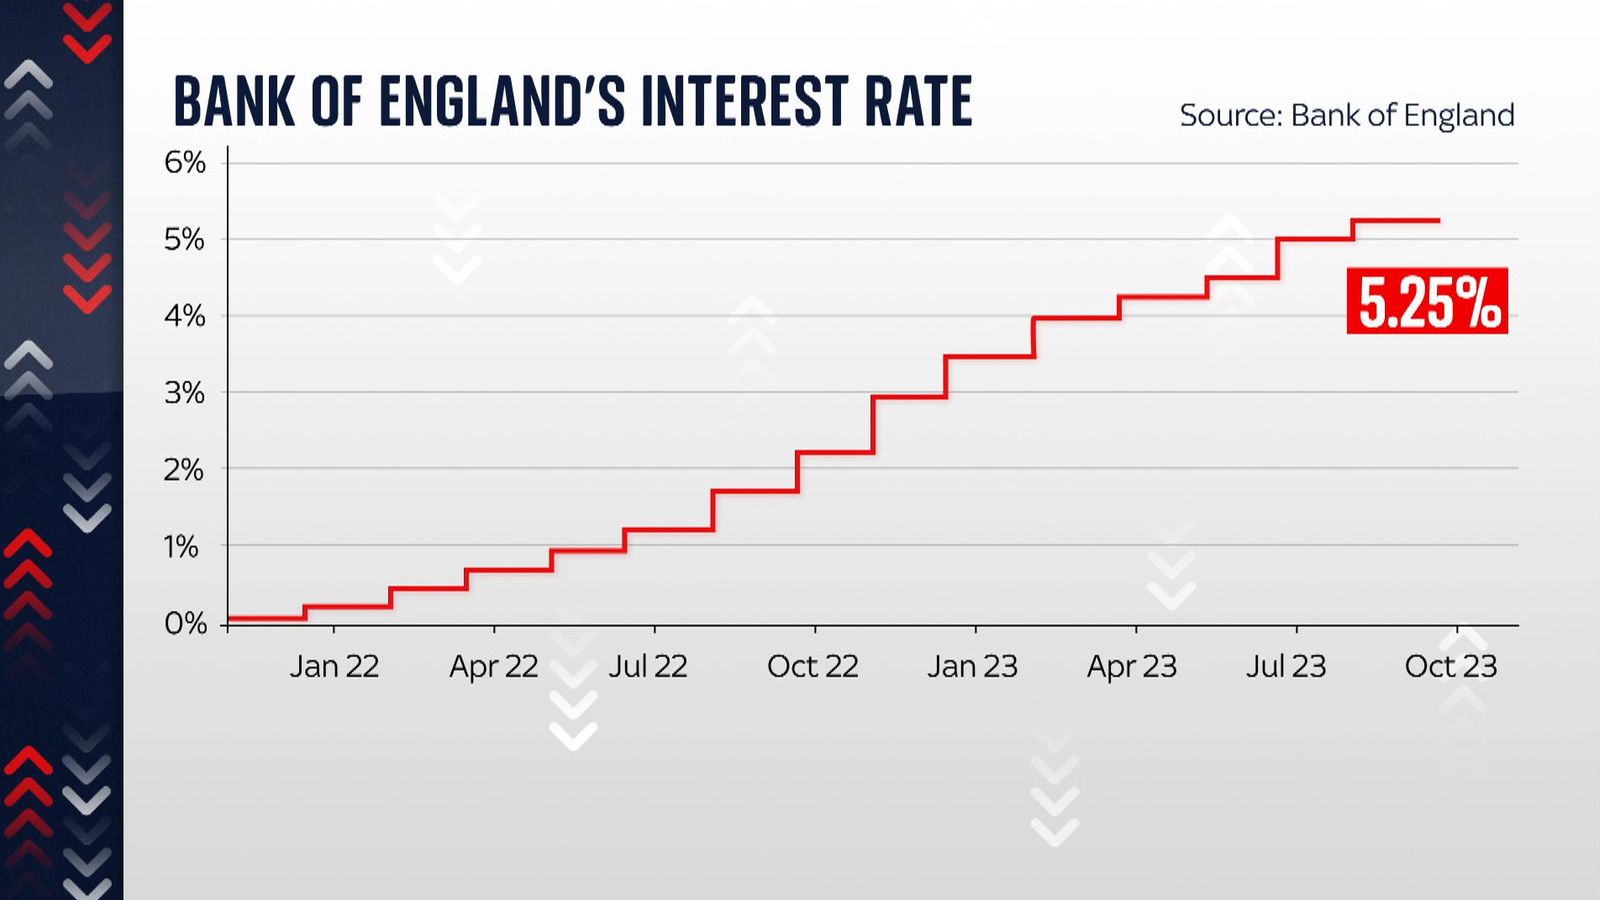
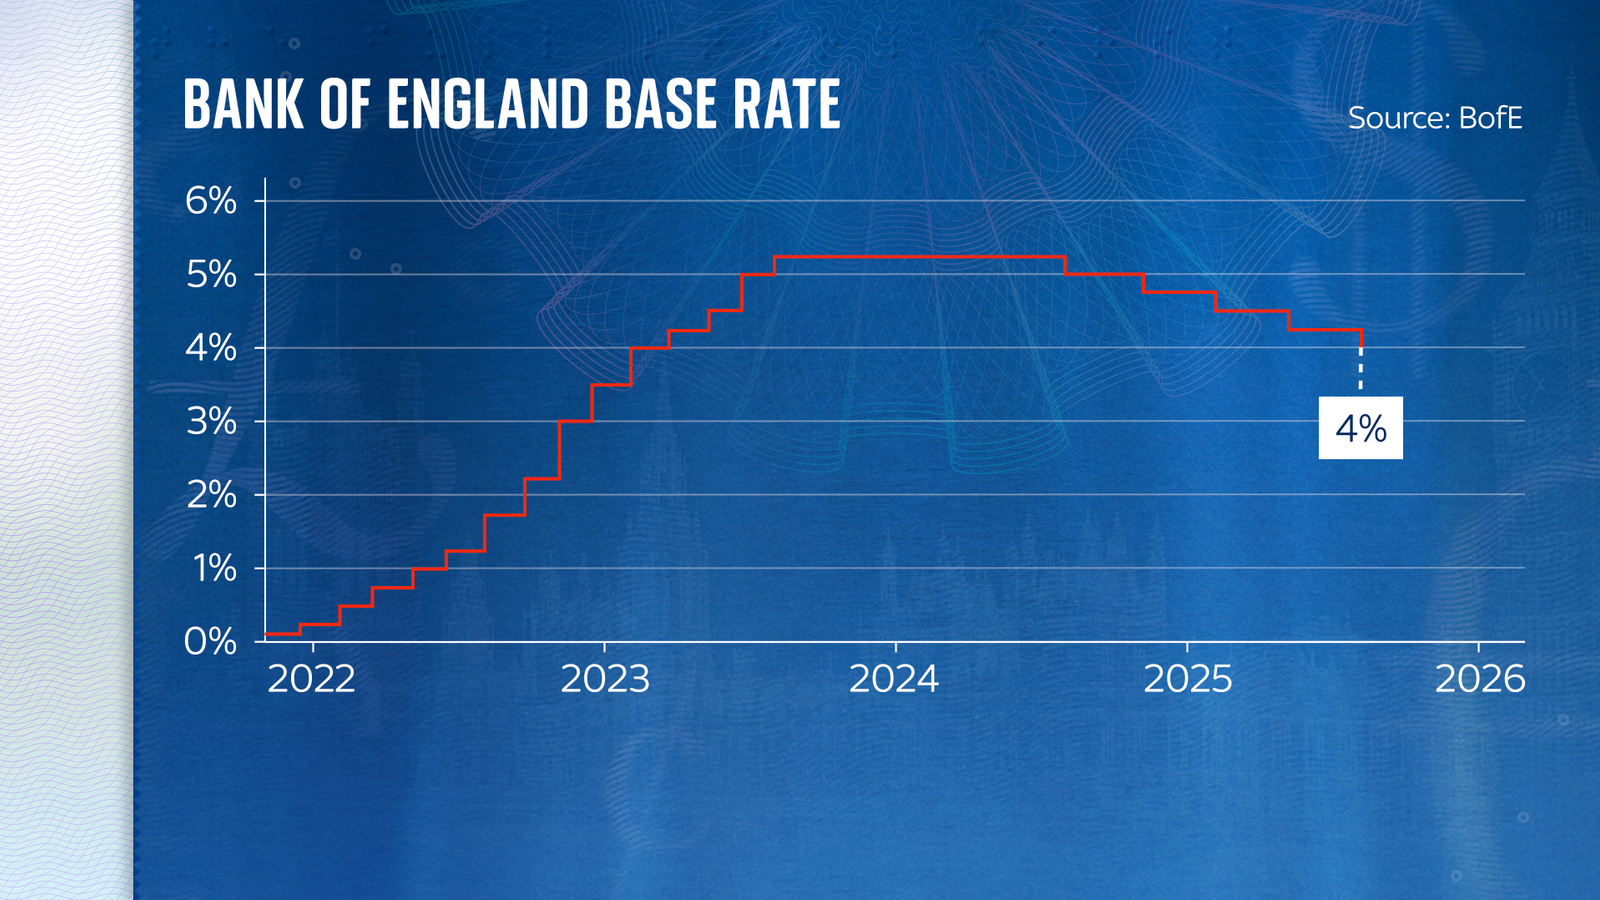
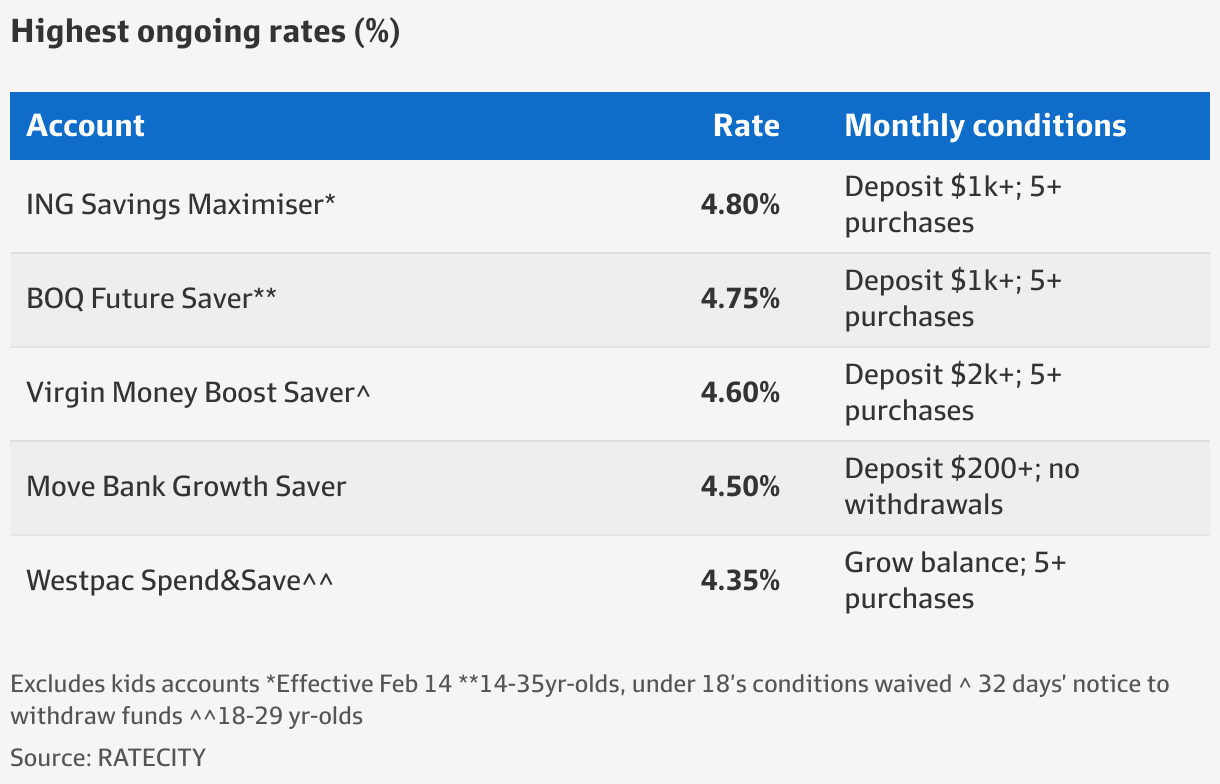
For savers and borrowers alike, Fifth Third Bank interest rates are influenced by broader monetary policy decisions set by the Federal Reserve, local market competition, and internal liquidity requirements. While online-only banks frequently advertise high-yield savings accounts that outpace traditional brick-and-mortar institutions, traditional banks like Fifth Third compete by offering integrated branch access, promotional CD terms, relationship-based interest bumps, and comprehensive wealth management services.
Whether you are looking to park emergency cash, lock in a guaranteed return with a fixed-term deposit, or finance a major purchase, evaluating Fifth Third Bank interest rates requires a granular look at account types, balance tiers, and promotional qualification criteria. This guide explores the mechanics of Fifth Third interest rates, breaks down how different products perform, examines eligibility criteria, and provides actionable insights to help you optimize your banking strategy.
Overview of Deposit Products and Yield Mechanics
Deposit accounts form the foundation of retail banking. At Fifth Third Bank, deposit interest rates vary significantly depending on the specific account tier, geographic market, and whether the account holder qualifies for relationship-banking benefits.
Standard Savings Accounts vs. High-Yield Alternatives
Traditional savings accounts at large national institutions traditionally offer baseline interest rates that remain relatively low compared to online alternatives. Fifth Third’s standard savings account typically yields a modest baseline annual percentage yield (APY) for everyday balances.
To secure higher yields within the Fifth Third ecosystem, customers generally must look beyond basic savings and explore promotional products or tiered structures. The primary trade-off of maintaining a deposit relationship with a regional bank involves balancing liquidity and branch convenience against the pursuit of maximum yield. While an online bank might offer a substantially higher APY on a standalone savings account, Fifth Third provides immediate cash handling, physical branch support, notary services, and seamless fund transfers tied to checking accounts.
Checking Account Interest Structures
Checking accounts are primarily designed for liquidity and transactional convenience rather than wealth accumulation. However, interest-bearing checking accounts do exist within major retail banks. Fifth Third offers checking options that may feature interest-earning capabilities, though these typically require maintaining a minimum daily balance or pairing the account with qualifying direct deposits and investment services.
When evaluating an interest-bearing checking account, it is critical to look past the nominal interest rate and examine potential monthly maintenance fees. If a monthly maintenance fee outweighs the interest earned over the course of a year, the net financial benefit becomes negative, negating the purpose of an interest-bearing structure.
Certificates of Deposit (CDs) and Promotional Terms
Certificates of Deposit represent one of the most reliable ways to secure a fixed rate of return for a predetermined period. Fifth Third Bank offers a variety of CD options, ranging from short-term promotional certificates to standard long-term commitments.
How Fifth Third CDs Operate
A Certificate of Deposit requires you to deposit a lump sum of money for a fixed term—ranging from a few months to several years. In exchange, the bank pays a fixed interest rate for the duration of that term.
- Fixed Returns: Unlike savings accounts where rates can fluctuate weekly based on market conditions, a CD locks in your rate the day you fund the account.
- Early Withdrawal Penalties: Withdrawing funds before the maturity date typically triggers a penalty, which often equals a forfeiture of a specific number of months' worth of interest. Consequently, funds placed in a CD should be capital you do not expect to need before the maturity date.
Promotional CD Offerings
Regional banks frequently deploy promotional CDs to attract new deposits or retain existing capital during shifting interest rate cycles. These promotional terms—such as 7-month, 11-month, or specialized step-up structures—frequently feature higher yields than standard product offerings. Securing these promotional Fifth Third Bank interest rates often requires meeting specific funding minimums, such as depositing new money not currently held in other Fifth Third accounts.
Comparison of Deposit and Loan Rate Structures
To understand how Fifth Third Bank positions its products in the marketplace, it is helpful to examine the relationship between deposit yields and borrowing costs across different product categories.
| Product Category | Typical Rate Structure | Key Considerations & Requirements |
|---|---|---|
| Standard Savings | Variable APY (Baseline) | Low minimums, highly liquid, lower relative yield. |
| Promotional CDs | Fixed APY for set terms | Requires minimum deposit, early withdrawal penalties apply. |
| Money Market Accounts | Tiered Variable APY | Higher balances unlock better rates; check maintenance fee waivers. |
| Mortgages (Fixed) | Fixed APR over 15 or 30 years | Subject to credit score, down payment, and current bond market yields. |
| Home Equity Lines (HELOC) | Variable APR tied to Prime Rate | Initial promotional periods may apply; rates adjust with Federal Reserve benchmarks. |
Borrowing Costs: Mortgages, Home Equity, and Personal Loans
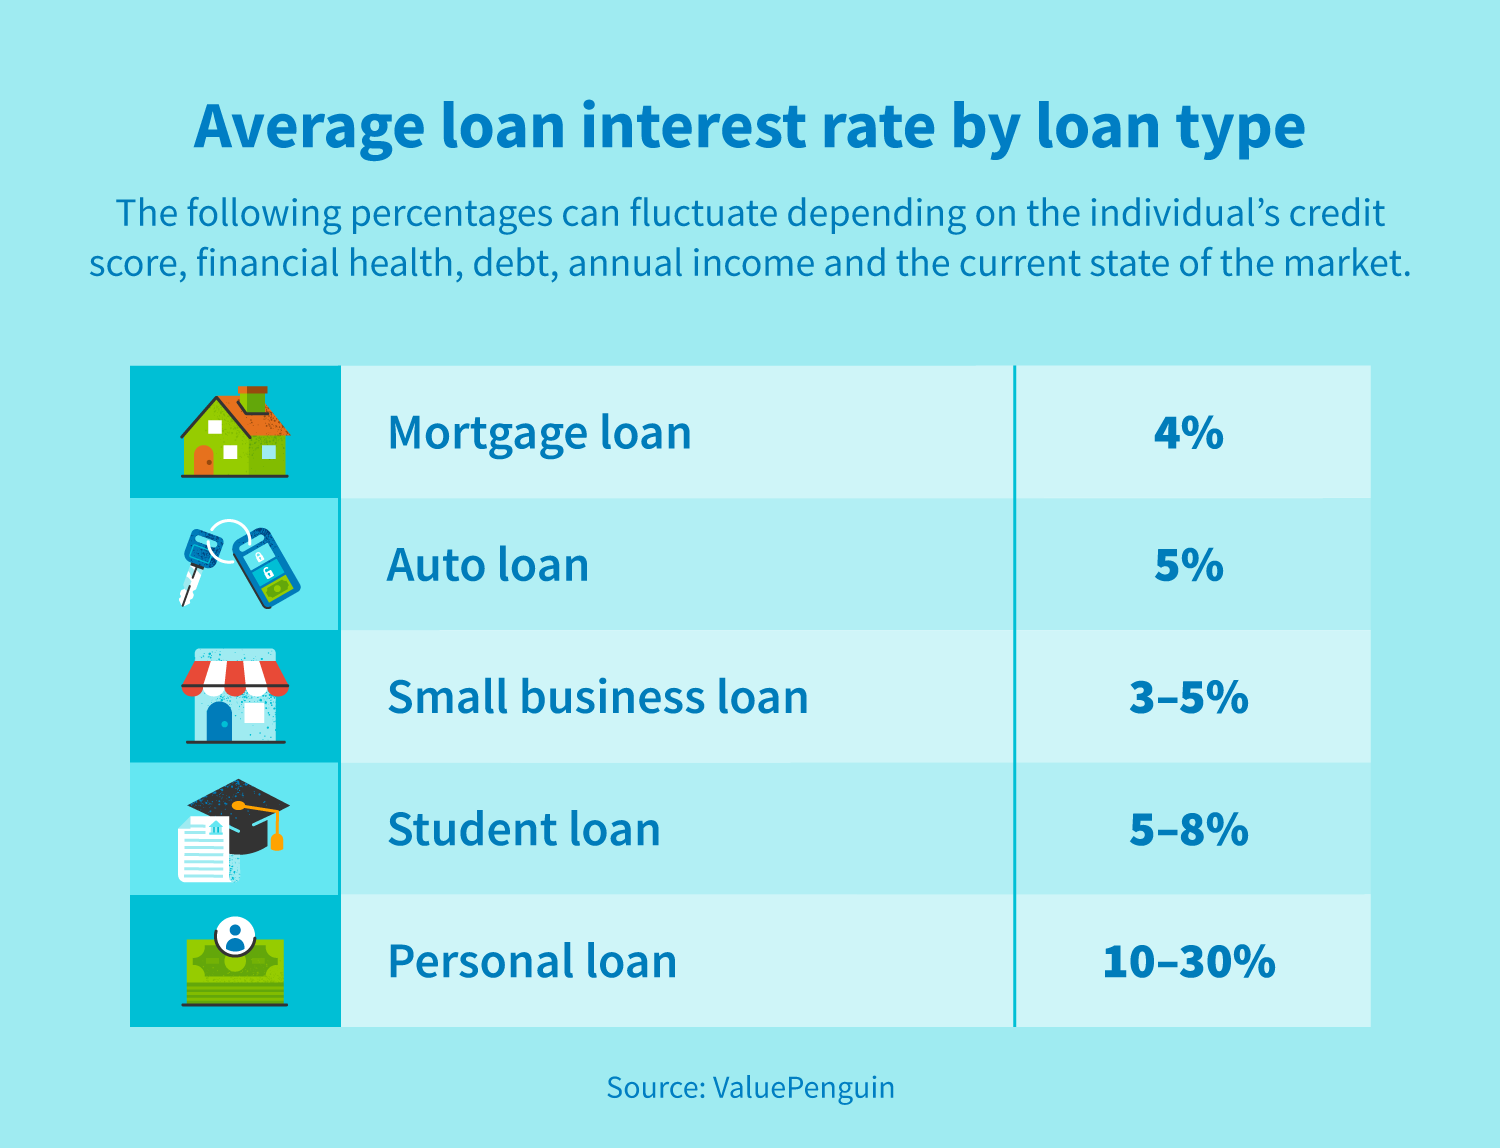
Interest rates are a two-way street; while deposit rates determine what the bank pays you, loan interest rates determine what you pay the bank. Fifth Third Bank provides a comprehensive suite of lending products, each governed by distinct rate mechanisms.
Mortgages and Refinancing
Fifth Third offers fixed-rate and adjustable-rate mortgages (ARMs).
- Fixed-Rate Mortgages: Provide stability by keeping your principal and interest payment identical for the life of the loan, typically 15 or 30 years.
- Adjustable-Rate Mortgages: Offer lower initial interest rates for a set period (e.g., 5 or 7 years) before adjusting periodically based on market indexes.
Mortgage rates offered by Fifth Third depend heavily on macroeconomic factors, such as yields on 10-year Treasury bonds, as well as borrower-specific metrics like credit scores, debt-to-income ratios, and loan-to-value percentages.
Home Equity Lines of Credit (HELOCs)
Home equity products allow homeowners to borrow against the equity built up in their property. Fifth Third HELOCs typically feature variable interest rates tied to the U.S. Prime Rate published in the Wall Street Journal.
- Borrowers should pay close attention to introductory promotional periods, during which the bank may offer a discounted fixed or variable rate for the first several months.
- Following the promotional window, the rate reverts to the standard variable margin added to the Prime Rate.
Relationship Banking and Rate Discounts
One of the most effective ways to secure better financial terms with a traditional national bank is through relationship banking tiers. Fifth Third structures its customer tiers—often branded under names like Fifth Third Momentum® Checking or private banking relationships—to reward customers who consolidate their financial lives with the institution.
Qualifying for Relationship Benefits
Maintaining higher combined balances across checking, savings, CDs, and investment accounts can unlock significant perks, which may include:
- Waived monthly maintenance fees on checking and savings accounts.
- Preferred or elevated interest rates on select savings or promotional deposit products.
- Discounts on loan origination fees or interest rate reductions on specific consumer loans and HELOCs.
Before committing large sums to achieve a relationship tier, consumers should weigh the opportunity cost. Earning a slightly higher interest rate on a deposit account through a relationship requirement might yield less overall return than investing surplus capital in diversified, higher-yield market instruments.
Strategies to Maximize Your Returns and Minimize Costs
Optimizing your interaction with Fifth Third Bank requires a proactive approach to account management and rate monitoring.
1. Monitor Rate Adjustments Periodically
Because deposit and loan rates fluctuate in response to economic conditions, check the current rate disclosures on the official Fifth Third Bank website or speak directly with a local branch representative before opening a new account or locking in a CD.
2. Leverage Promotional Windows
If you have cash reserves that you do not need for immediate daily expenses, look out for promotional CD windows. These products often provide a reliable hedge against potential drops in variable interest rate environments.
3. Factor in Fees
Always calculate net yield. A high headline interest rate on a savings or money market account is diminished if monthly account maintenance fees erode the principal balance. Ensure you meet fee-waiver criteria, such as maintaining minimum daily balances or setting up qualifying direct deposits.
Frequently Asked Questions
How often do Fifth Third Bank interest rates change?
Variable deposit and loan rates—such as those on standard savings accounts, money market accounts, and variable-rate HELOCs—can change at any time in response to shifts in the Federal Funds Rate or internal bank policies. Fixed-rate products, such as standard mortgages and fixed-term CDs, lock in your rate for the duration of the agreed term.
Are Fifth Third Bank deposits secure?
Yes. Fifth Third Bank is a member of the Federal Deposit Insurance Corporation (FDIC). Deposits held across eligible accounts are insured up to the statutory maximum of $250,000 per depositor, per ownership category, providing a government-backed guarantee against bank failure.
Can I negotiate interest rates with Fifth Third Bank?
While standard retail deposit rates are generally non-negotiable for everyday accounts, relationship managers and private banking clients with substantial liquid assets or high-value borrowing needs may have more flexibility to discuss custom pricing or loan fee waivers.
What happens when a Fifth Third CD matures?
When a Certificate of Deposit reaches maturity, Fifth Third Bank typically provides a grace period—usually around 7 to 10 days—during which you can withdraw the funds, add to them, or roll them into a new CD term without penalty. If no action is taken, the bank frequently rolls the balance into an auto-renewing CD of a similar term at the current prevailing rate.
Next Steps and Actionable Recommendations
To make the most of Fifth Third Bank interest rates, begin by auditing your current financial portfolio. Identify funds earmarked for short-term emergency reserves, medium-term goals, and long-term investments. Compare Fifth Third's current promotional deposit yields against other regional and online institutions to ensure your capital is working efficiently. If you are planning to borrow, obtain pre-approval quotes, explore relationship-discount eligibility, and evaluate the long-term impact of fixed versus variable rate structures on your household budget.