A Health Reimbursement Arrangement (HRA) is an employer-funded, tax-advantaged employer health benefit plan that reimburses employees for out-of-pocket medical expenses and, in many cases, individual health insurance premiums. Because employers own and fund the arrangement, organizations can maintain strict budget control while providing customizable health coverage support that complements traditional group health insurance or stands alone as an alternative option.
Navigating employee benefits requires a firm understanding of tax codes, compliance regulations, and reimbursement mechanics. For employers, designing an effective compensation and benefits package means finding a balance between comprehensive coverage and fiscal predictability. For employees, understanding how to maximize these accounts can significantly reduce the personal financial burden of healthcare. This guide explores the foundational mechanics of HRAs, the different types available, compliance requirements, operational considerations, and how these plans stack up against other financial healthcare vehicles.
Understanding the Fundamentals of HRAs
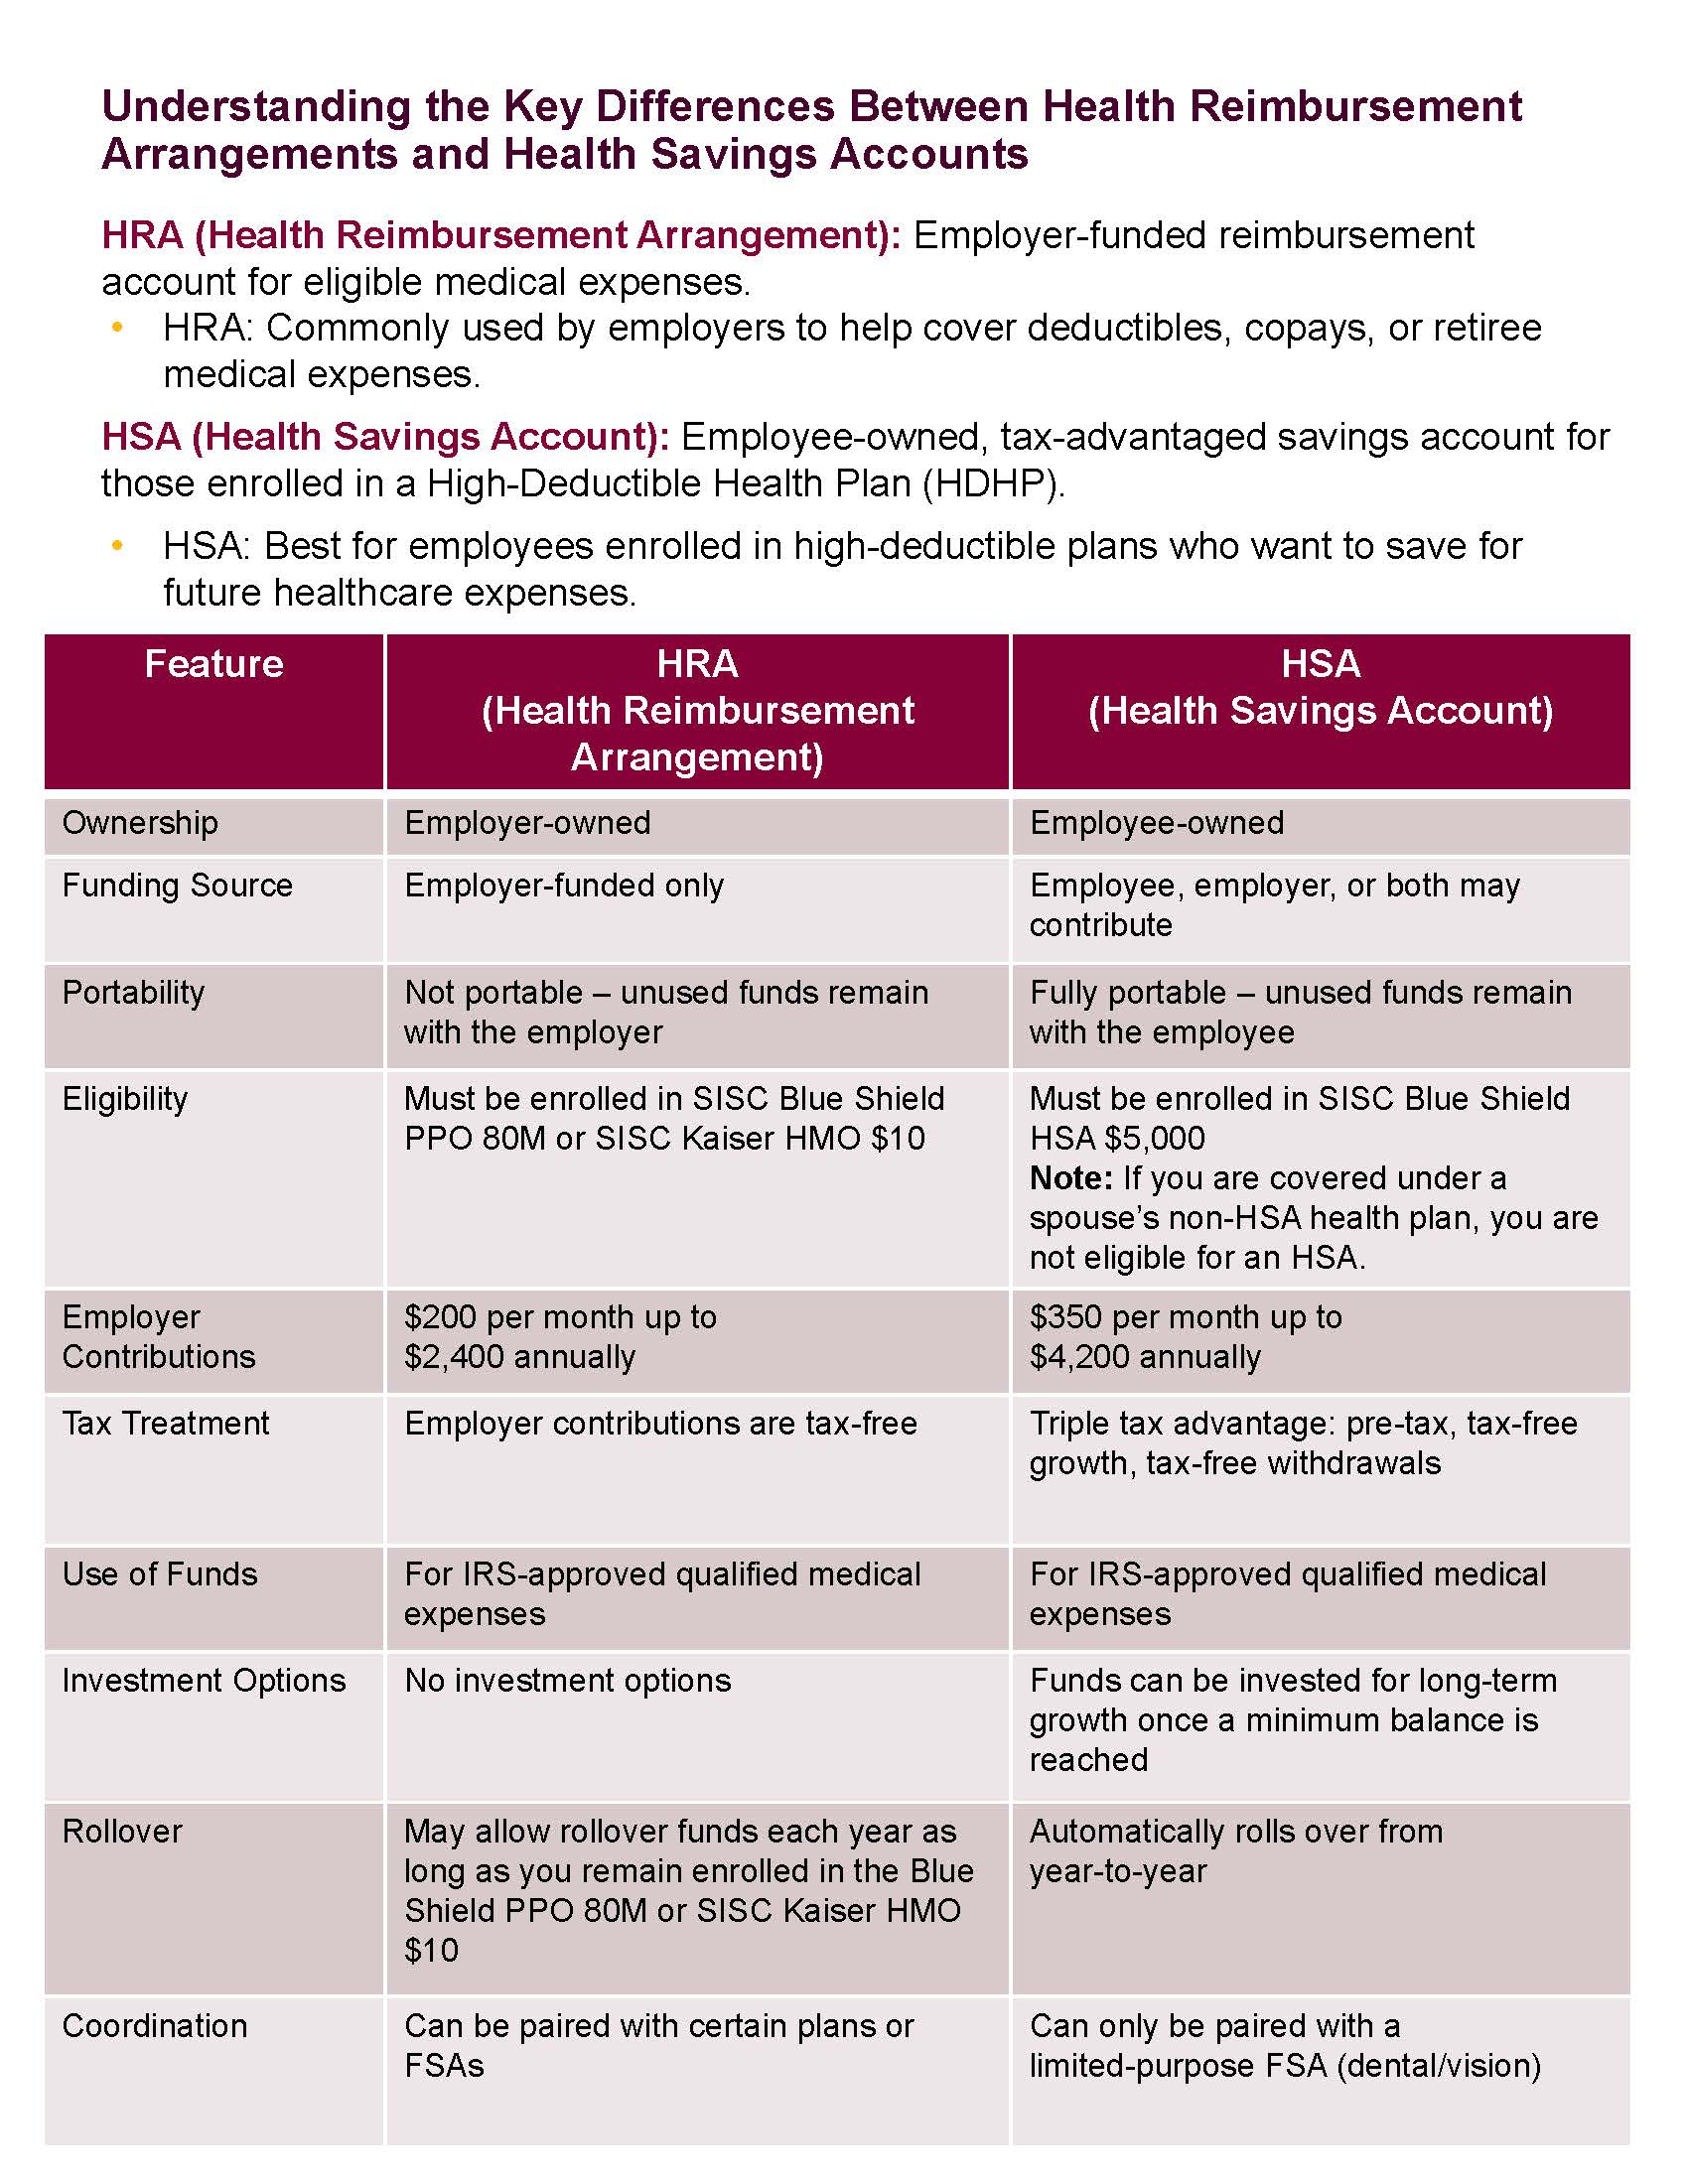
At its core, a Health Reimbursement Arrangement is an employer-sponsored benefit. Unlike a Health Savings Account (HSA) or a Flexible Spending Account (FSA), employees cannot contribute their own pre-tax dollars to an HRA. Instead, the employer establishes an allowance, and employees draw against this pool of funds by submitting proof of qualified medical expenses.
The primary allure of an HRA lies in its tax structure. Reimbursements made to employees are generally exempt from federal income and employment taxes for the employee, while employers can typically deduct these reimbursements as business expenses. This creates a mutually beneficial mechanism for handling healthcare costs outside of traditional group insurance premiums.
Ownership and Portability Rules
One of the most defining characteristics of an HRA is employer ownership. Because the employer funds the arrangement, the money belongs to the organization, not the employee.
- If an employee incurs a qualified medical expense while covered under the plan, they can seek reimbursement up to their allowance limit.
- If an employee leaves the company, unused HRA funds typically do not travel with them. Employers can choose to allow run-out periods for past expenses submitted after termination, but the remaining balance generally reverts to the employer.
- Employers have the discretion to roll over unused funds from year to year, though this is not mandatory unless specified in the plan document.
Qualified Medical Expenses
The scope of what an HRA can reimburse is governed by Internal Revenue Code Section 213(d). Generally, expenses must be incurred to mitigate or prevent a physical or mental defect or illness. Typical reimbursable expenses include:
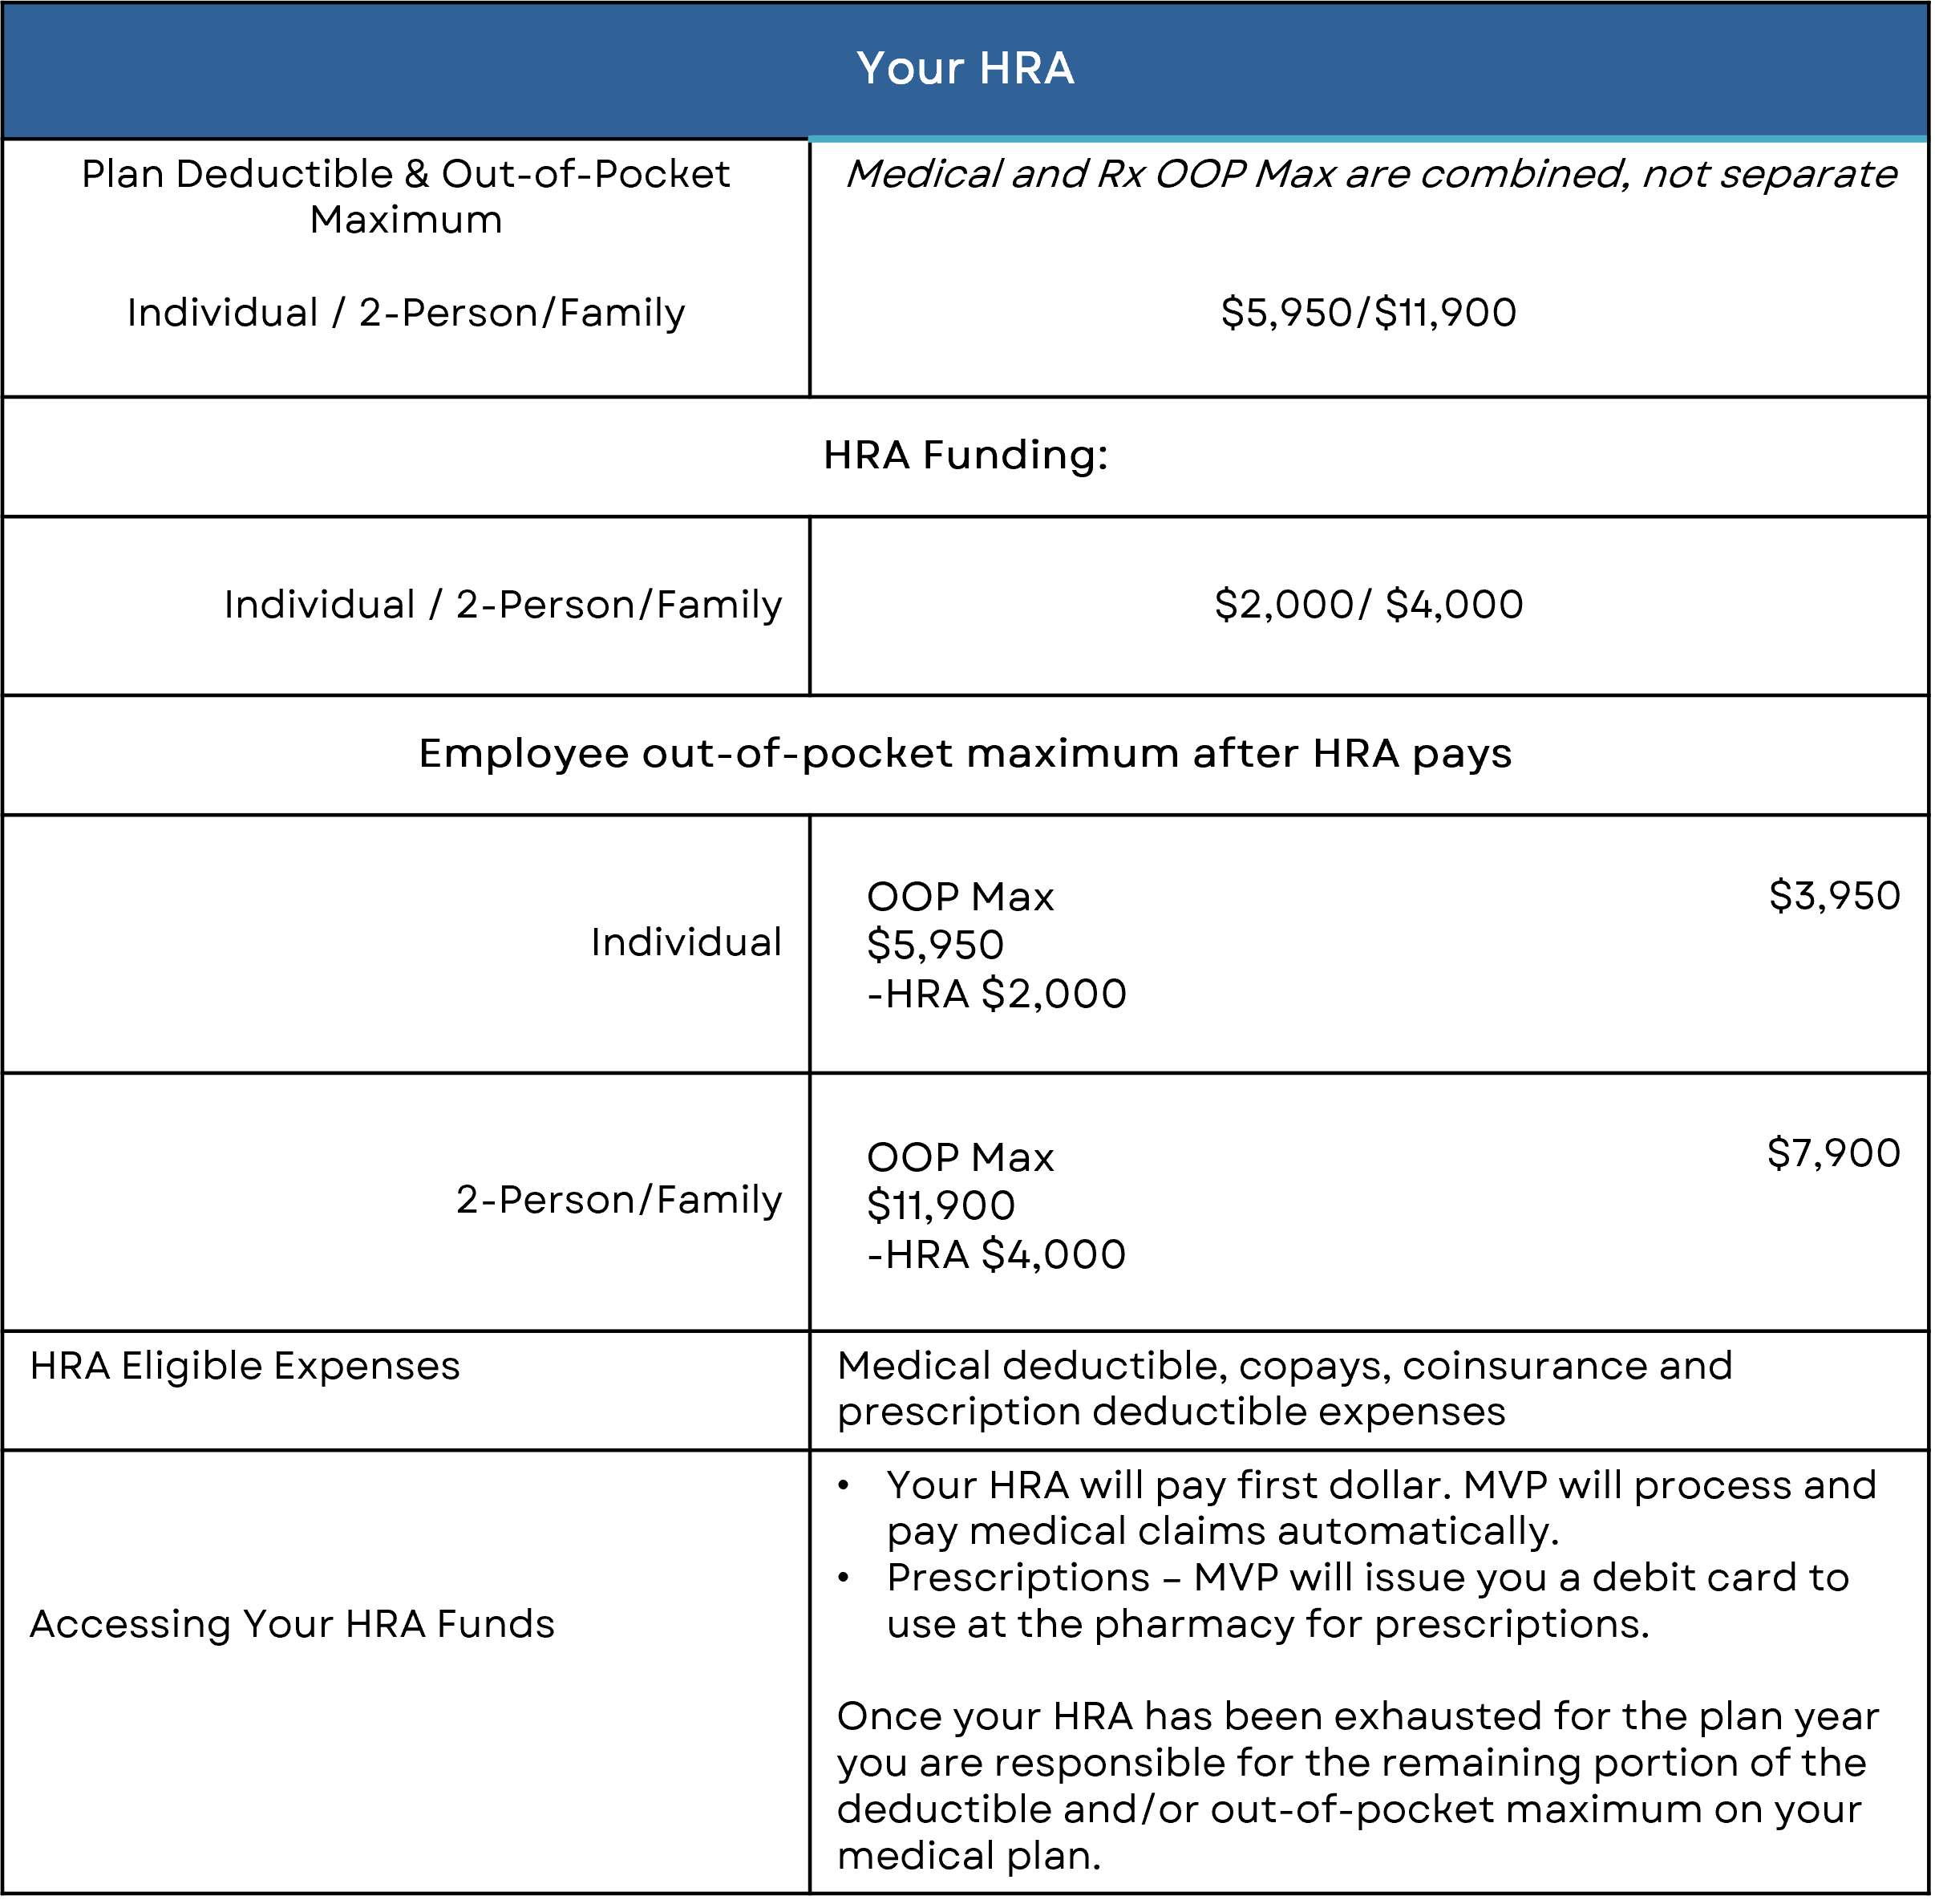
- Deductibles, copayments, and coinsurance under a health plan.
- Prescription medications and insulin.
- Vision care, including eye exams, prescription glasses, and contact lenses.
- Dental care, ranging from routine cleanings to major restorative procedures.
- Medical equipment, such as blood pressure monitors and crutches.
Cosmetic procedures, over-the-counter items without a prescription (depending on current tax law updates), and general health club memberships typically do not qualify unless prescribed by a physician to treat a specific medical condition.
Principal Types of Health Reimbursement Arrangements
Over the years, regulatory frameworks have expanded to accommodate various business models. Today, several distinct types of HRAs exist, each tailored to specific organizational structures and workforce demographics.
Integrated HRA (Traditional HRA)
An integrated HRA works alongside a traditional group health plan, such as a Preferred Provider Organization (PPO) or Health Maintenance Organization (HMO).
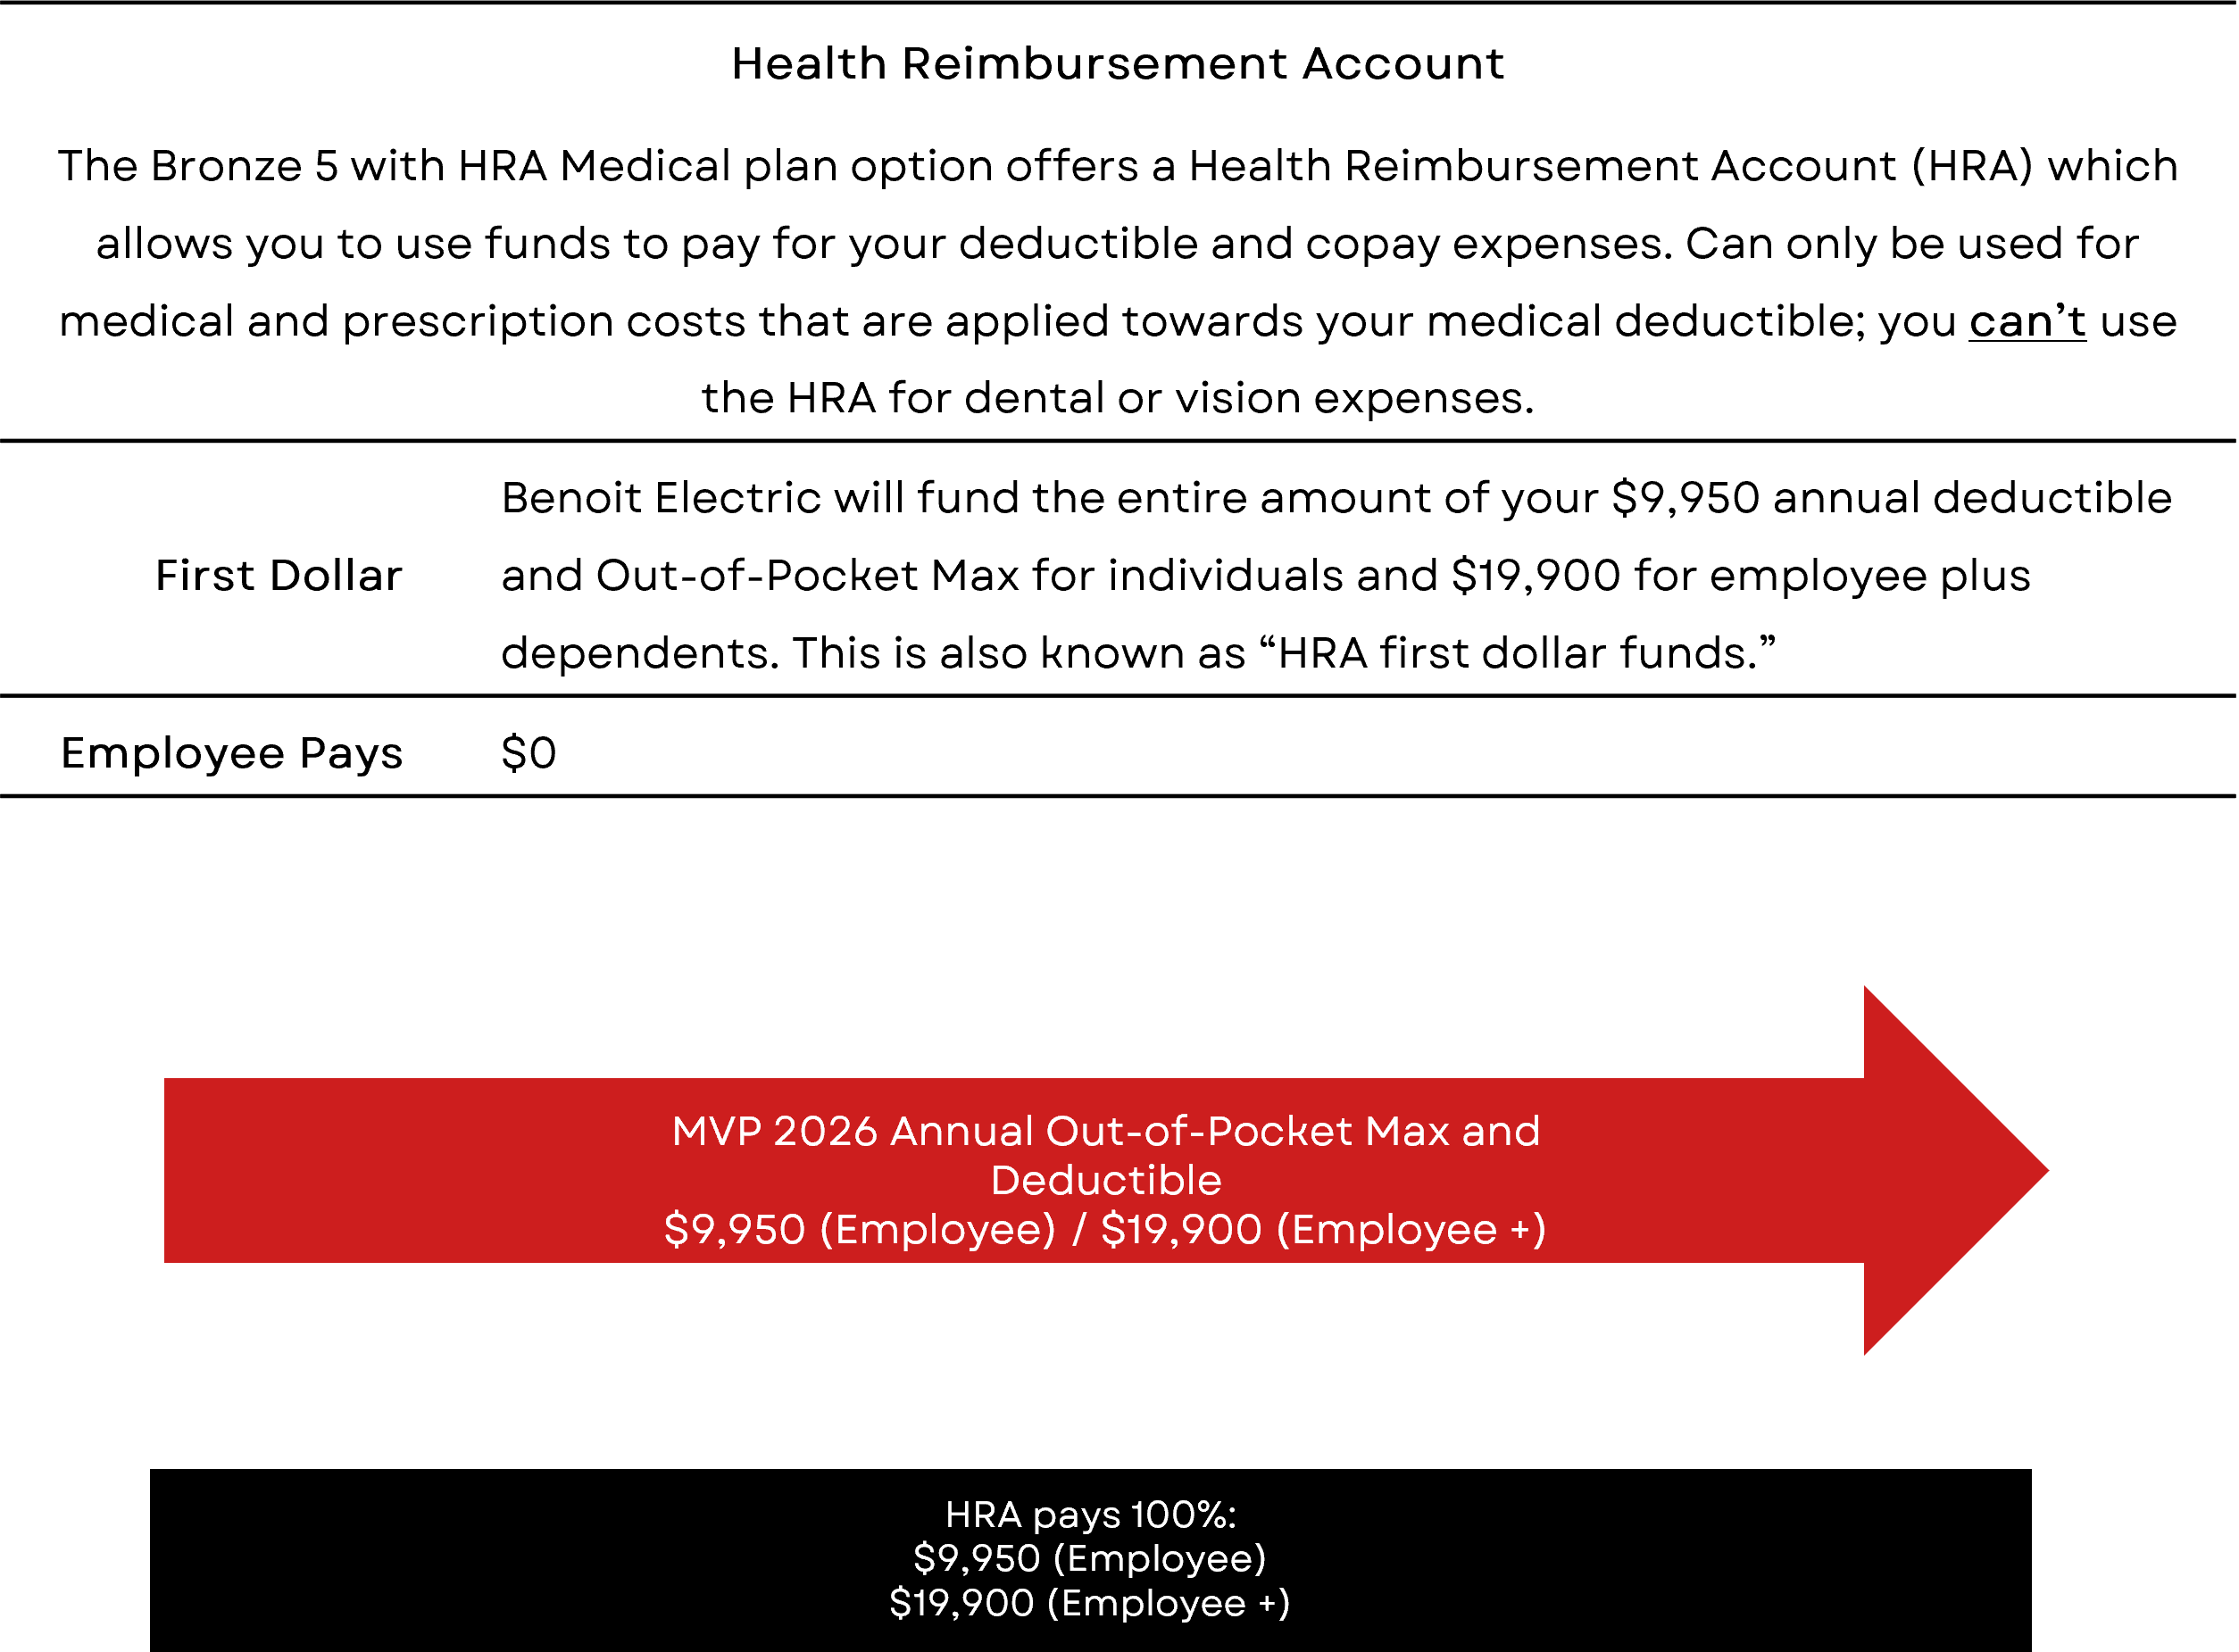
- Purpose: Designed to help offset out-of-pocket costs—such as high deductibles or copays—that employees face even with group insurance.
- Requirements: Employees must be enrolled in the employer’s group health plan to participate in the integrated HRA.
- Use Case: Organizations wishing to offer a rich health benefits package while managing corporate risk by shifting a portion of the financial exposure to a defined-contribution model.
Qualified Small Employer HRA (QSEHRA)
Introduced via federal legislation to help small businesses, the QSEHRA is specifically tailored for organizations with fewer than 50 full-time equivalent (FTE) employees that do not offer a traditional group health plan.
- Purpose: Allows small businesses to provide tax-free reimbursements for medical expenses and individual health insurance premiums.
- Requirements: Must be provided on the same terms to all eligible employees, though statutory caps on maximum reimbursement amounts apply annually.
- Use Case: Small business owners who find traditional group health insurance cost-prohibitive but want to help employees pay for individual coverage on the health insurance marketplace.
Individual Coverage HRA (ICHRA)
The ICHRA is a modern iteration that allows employers of any size to provide tax-free reimbursements for individual health insurance policies or Medicare plans instead of offering a traditional group health plan.
- Purpose: Offers maximum flexibility and personalization, allowing employees to shop for individual plans tailored to their unique medical needs.
- Requirements: Employees must maintain individual health insurance coverage (or Medicare Parts A and B / Medicare Advantage) to participate. Employers can divide employees into distinct classes (e.g., full-time, part-time, salaried, hourly) and offer different allowance amounts to each class, provided minimum class sizes are met.
- Use Case: Mid-to-large enterprises seeking to exit the traditional group market and transfer insurance purchasing decisions to employees while maintaining predictable budgeting.
Excepted Benefit HRA (EBHRA)
An EBHRA is designed to supplement a traditional group health plan, but with a specific twist: it cannot be used to purchase primary health insurance or cover comprehensive medical care.
- Purpose: Reimburses "excepted benefits" such as dental and vision care, short-term limited-duration insurance (STLDI), or COBRA premiums.
- Requirements: The employer must also offer a traditional group health plan, but employees do not need to enroll in it to participate in the EBHRA. Annual contribution limits apply.
- Use Case: Organizations looking to offer a secondary benefit perk to employees who opt out of the primary group health plan or need extra help covering ancillary health costs.
Comparison of Common HRA Structures
| Feature | Integrated HRA | QSEHRA | ICHRA | EBHRA |
|---|---|---|---|---|
| Employer Size | Any size | Fewer than 50 FTEs | Any size | Any size |
| Group Plan Required? | Yes | No | No (must offer individual coverage) | Yes (must be offered) |
| Reimburses Premiums? | No | Yes | Yes | Yes (limited to excepted/COBRA) |
| Class-Based Scaling | No | No (must be uniform) | Yes | Yes |
| Employee Contributions | No | No | No | No |
Establishing and Administering an HRA
Implementing an HRA requires adherence to strict legal, administrative, and fiduciary standards. Because these arrangements involve federal tax codes, missteps can lead to severe penalties or loss of tax-advantaged status.
Drafting the Plan Document
Every HRA must be governed by a written plan document that outlines eligibility rules, types of reimbursable expenses, maximum allowance amounts, and claim procedures. Under federal law, HRAs are generally classified as group health plans subject to Employee Retirement Income Security Act (ERISA) regulations, meaning the employer must provide a Summary Plan Description (SPD) to eligible participants.
Setting Allowance Limits
Employers possess wide latitude in structuring allowance amounts, subject to statutory limits where applicable (such as with QSEHRAs and EBHRAs). When designing allowances under an ICHRA, employers must adhere to rules regarding minimum class sizes to prevent discrimination in favor of highly compensated employees.
Substantiation and Proof of Coverage
Administrators cannot blindly disburse funds. Every reimbursement request requires proof that a qualified expense was incurred.
- For medical expenses, itemized receipts showing the date of service, provider name, description of service, and out-of-pocket cost are mandatory.
- For ICHRA and QSEHRA plans involving individual health insurance premiums, participants must submit proof of ongoing enrollment in a qualified health plan at least annually, along with regular premium invoices and payment receipts.
Third-Party Administration vs. Internal Management
While a small business might attempt to manage a straightforward QSEHRA internally, most organizations partner with a Third-Party Administrator (TPA) or specialized software platform. TPAs automate the substantiation process, ensure compliance with changing federal regulations, issue debit cards, and maintain secure records to withstand potential audits.
Advantages and Operational Considerations
Evaluating whether an HRA is the right choice for an organization involves weighing distinct strategic advantages against operational complexities.
Key Benefits for Employers
- Budget Predictability: By setting a fixed monthly or annual allowance, employers cap their financial exposure. Unlike traditional group health plans where premium spikes are common, HRA budgets remain entirely under employer control.
- Tax Efficiency: Reimbursed funds are exempt from payroll taxes (FICA), reducing the overall cost of providing compensation compared to standard salary increases.
- Customization: Plans like the ICHRA allow organizations to tailor benefits to specific employee classes, supporting targeted recruitment and retention strategies.
Key Benefits for Employees
- Tax-Free Dollars: All reimbursements received for qualified medical expenses and eligible premiums are entirely free from federal, and often state, income taxes.
- Personalized Coverage: With individual-market HRAs, employees are no longer bound by a one-size-fits-all corporate health plan and can select insurance that matches their personal physician networks and prescription needs.
- Financial Cushion: Integrated HRAs reduce the sting of high-deductible health plans by providing employer-backed assistance for everyday medical bills.
Potential Drawbacks and Challenges
- Administrative Burden: Processing claims, verifying insurance coverage, and ensuring regulatory compliance require ongoing diligence and technology infrastructure.
- Employee Education: Transitioning a workforce from a traditional group plan to an ICHRA or introducing a complex reimbursement structure requires clear communication. Employees accustomed to turnkey group plans may find shopping for individual insurance daunting.
- Upfront Out-of-Pocket Costs: Because HRAs operate on a reimbursement model, employees must generally pay for medical services or premiums upfront and wait for the employer or TPA to process their claim payout.
Frequently Asked Questions
Can an employee contribute their own money to an HRA?
No. An HRA is strictly an employer-funded benefit. Employees cannot make pre-tax or post-tax salary deductions into an HRA. However, employees can often pair an HRA with an HSA or FSA if plan rules permit, provided coordination of benefits guidelines are met.
What happens to unused HRA money at the end of the year?
It depends on the employer's plan design. Employers are not required to allow rollovers, meaning unused funds can forfeit back to the company at the end of the plan year. However, many employers choose to permit carryovers to increase the attractiveness of the benefit.
Can an HRA be used to pay for family members' medical expenses?
Yes. An HRA can reimburse qualified medical expenses incurred by the employee, their spouse, and their tax dependents, provided the plan document permits family coverage and the expenses meet Internal Revenue Code guidelines.
Are HRA reimbursements considered taxable income?
No. As long as the reimbursements are used for qualified medical expenses or eligible health insurance premiums under a compliant plan, the funds are entirely tax-free for the employee and tax-deductible for the employer.
Can an employer offer both a traditional group health plan and an ICHRA to the same employees?
Generally, no. An employer cannot offer the same group of employees a choice between a traditional group health plan and an ICHRA. However, an employer can offer a traditional group plan to one class of employees and an ICHRA to a completely separate class of employees, provided the classes meet legal minimum size and definition criteria.
What is the difference between an HRA and an HSA?
While both offer tax advantages for healthcare, an HRA is owned and funded exclusively by the employer, whereas a Health Savings Account (HSA) is owned by the individual, requires enrollment in a High-Deductible Health Plan (HDHP), and allows both employer and employee contributions. Furthermore, HSA funds are fully portable when an employee leaves a job.
Next Steps for Employers and Employees
Maximizing the value of an HRA requires careful planning and continuous monitoring. For employers, the immediate next step is to conduct a workforce demographic analysis and consult with a licensed benefits broker or TPA to determine which HRA structure aligns with organizational goals and budget constraints. Drafting a compliant plan document and establishing clear internal communication channels will ensure a smooth rollout.
For employees, reviewing your employer’s Summary Plan Description is essential. Take inventory of your recurring medical expenses, check whether your plan allows for premium reimbursements or deductible offsets, and establish a system for saving itemized receipts to ensure you capture every tax-free dollar to which you are legally entitled.