A TIAA account is a centralized financial portal designed primarily for employees in the academic, research, medical, and cultural sectors to manage retirement savings, insurance, and brokerage investments. It provides access to employer-sponsored plans like 403(b)s, individual retirement accounts (IRAs), and unique fixed-annuity products like TIAA Traditional, enabling long-term wealth accumulation and lifetime income planning.
Understanding the TIAA Account Ecosystem
The Teachers Insurance and Annuity Association of America (TIAA) remains a cornerstone of the American retirement landscape, specifically tailored for those who serve the public good. Unlike a standard retail brokerage account, a TIAA account is often the primary vehicle for institutional retirement plans. In 2026, these accounts have evolved into highly integrated digital hubs that balance complex annuity products with modern, user-friendly investment tools.
When you open a TIAA account, you are typically entering into a contractual relationship that involves both accumulation (saving money) and distribution (receiving income). The core of the TIAA philosophy is the transition from a "defined contribution" model during your working years to a "guaranteed income" model during retirement. This is largely achieved through the use of variable and fixed annuities, which differ significantly from the mutual funds found in a standard 401(k).
The TIAA portal serves as the command center for these activities. Whether you are a tenured professor, a laboratory researcher, or a non-profit administrator, your account is the gateway to tracking your "vintages" in fixed accounts, rebalancing your variable annuity allocations, and updating your legacy through beneficiary designations.
Prerequisites and Initial Account Registration
Accessing a TIAA account requires specific eligibility, usually tied to employment at a participating 501(c)(3) organization or a public educational institution. If you are a new employee, your institution will generally initiate the plan setup, but you must complete the registration to take control of your investments and designate beneficiaries.
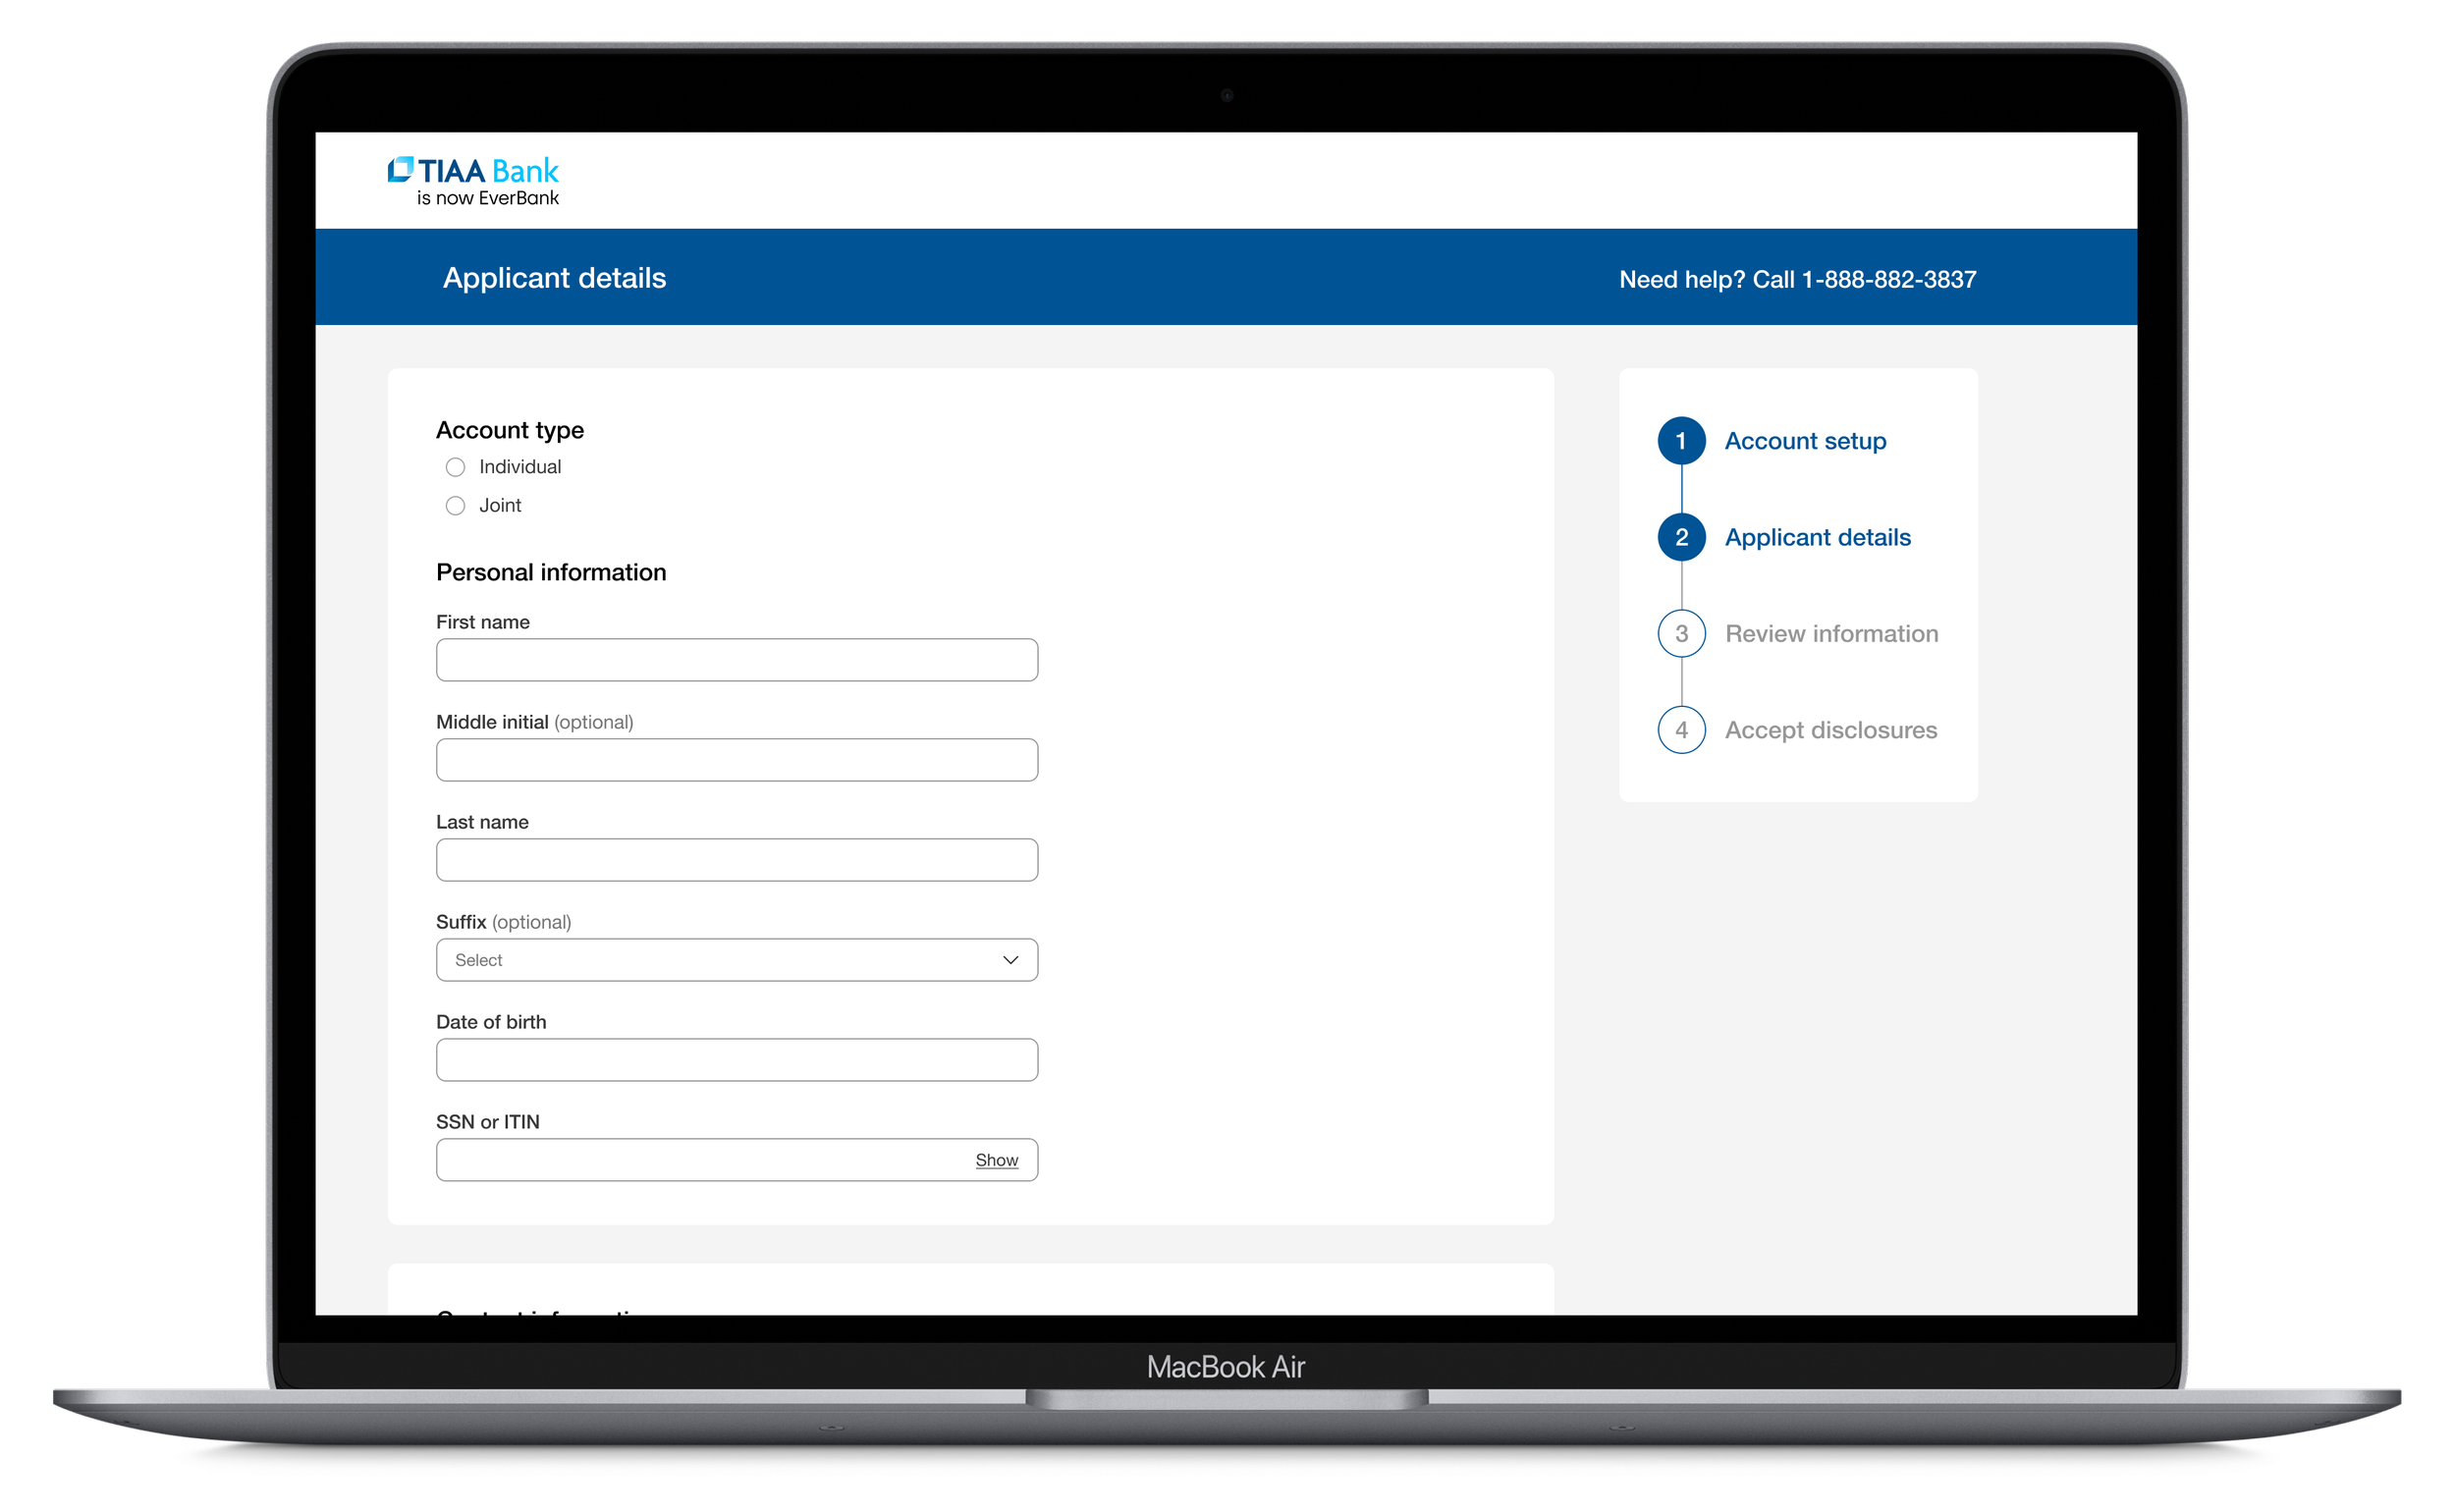
To register your account in 2026, you will need your Social Security Number (SSN) or Taxpayer Identification Number (TIN), your date of birth, and your primary ZIP code. During the digital onboarding process, you will create a unique user ID and a robust password. TIAA now mandates enhanced multi-factor authentication (MFA) for all users to combat the rising sophistication of financial identity theft.
During registration, pay close attention to the distinction between "Plan Enrollment" and "Account Access." Enrollment involves choosing your contribution percentage and investment mix, whereas Account Access refers to the digital credentials used to view your balance. For those with multiple employers throughout their careers, TIAA allows for the consolidation of various plan IDs under a single login, providing a holistic view of your retirement readiness across different institutional epochs.
Navigating the TIAA Digital Dashboard
The 2026 TIAA dashboard is designed to provide immediate clarity on three major fronts: your total balance, your projected retirement income, and your current asset allocation. The interface uses a "holistic wealth" approach, often integrating external accounts if you choose to link them via secure Open Banking protocols.
The "Summary" tab provides a snapshot of all your holdings, categorized by plan type. For example, you may see a 403(b) Retirement Annuity (RA) from a previous employer alongside a Supplemental Retirement Annuity (SRA) from your current one. Each plan carries its own rules regarding withdrawals and loans, which are detailed in the "Plan Rules" section of the dashboard.
The "Performance" section offers more than just a history of gains and losses. It provides a benchmark comparison, allowing you to see how your chosen CREF (College Retirement Equities Fund) variable annuities or TIAA-managed mutual funds are performing against broader market indices like the S&P 500 or the Bloomberg Aggregate Bond Index. Understanding these metrics is essential for determining if your current strategy aligns with your risk tolerance as you approach your target retirement date.
Types of Accounts Within the TIAA Framework
One of the most common points of confusion for TIAA participants is the variety of account structures available. Because TIAA serves a diverse range of institutions, your account might house several different legal entities simultaneously.
Employer-Sponsored Plans: 403(b) and 401(k)
The 403(b) is the flagship product for TIAA, functioning similarly to a 401(k) but tailored for non-profit and tax-exempt organizations. Contributions are made via payroll deduction, often with an employer match. In 2026, the IRS contribution limits remain a critical metric to track, as maximizing these contributions is the most efficient way to lower your taxable income while building a nest egg.
Individual Retirement Accounts (IRAs)
Many participants open supplemental IRAs within their TIAA account to further their savings or to roll over funds from previous employers. TIAA offers both Traditional IRAs (tax-deferred) and Roth IRAs (tax-free growth), providing flexibility for different tax brackets.
Brokerage and Managed Accounts
For those seeking investments beyond the standard TIAA/CREF lineup, the TIAA Brokerage account provides access to thousands of stocks, ETFs, and third-party mutual funds. Additionally, TIAA offers managed account services where professional advisors adjust your portfolio based on market conditions and your personal goals, a service that has become increasingly automated through AI-driven rebalancing in 2026.
Core Investment Vehicles: TIAA Traditional and CREF
The defining feature of a TIAA account is the access to proprietary investment vehicles that are not available through other providers. Understanding these is the key to mastering your account.
TIAA Traditional (The Fixed Annuity)
TIAA Traditional is a guaranteed fixed annuity. It offers a guaranteed minimum interest rate plus the potential for additional amounts declared by the TIAA Board of Trustees. Unlike a bond fund, the principal in TIAA Traditional does not fluctuate with market interest rates. However, it is important to note the liquidity constraints: some versions of TIAA Traditional (like those in RA contracts) require you to withdraw funds over a 10-year period (a Transfer Payout Annuity), while others (like those in SRA contracts) offer full liquidity.
CREF Variable Annuities
The College Retirement Equities Fund (CREF) offers variable annuities, which were the first of their kind in the world. These accounts, such as the CREF Stock Account or the CREF Global Equities Account, allow you to participate in equity and bond markets while maintaining the option to convert the balance into a lifetime income stream later. Because they are annuities, they have different expense structures and regulatory oversight than standard mutual funds.
Managing Beneficiaries and Legal Designations
A critical, yet often overlooked, aspect of TIAA account management is the maintenance of beneficiary designations. Because these accounts are governed by ERISA (the Employee Retirement Income Security Act) and specific contract laws, your TIAA beneficiaries generally supersede any instructions left in a will.
In your account settings, you can designate primary and contingent beneficiaries. A primary beneficiary is first in line to receive your assets, while the contingent beneficiary receives them only if the primary is deceased. In 2026, TIAA’s digital process allows for "per stirpes" designations, which ensures that if a beneficiary predeceases you, their share passes to their children rather than being redistributed among other surviving beneficiaries.
Failing to update beneficiaries after major life events—such as marriage, divorce, or the birth of a child—can lead to significant legal complications and tax burdens for your heirs. It is recommended to review these designations annually during your "financial check-up" in the TIAA portal.
2026 Security Protocols and Account Protection
Financial institutions face constant threats, and your TIAA account contains sensitive personal and financial data. In 2026, TIAA has implemented a multi-layered security architecture to protect participant assets.
- Biometric Authentication: The TIAA mobile app utilizes FaceID, TouchID, and voice biometrics to verify identity.
- Security Keys: Users can now register physical security keys (like YubiKeys) for hardware-based MFA, which is significantly more secure than SMS-based codes.
- The TIAA Digital Guarantee: TIAA offers a guarantee to reimburse accounts for losses due to unauthorized transactions, provided the user has followed basic security hygiene, such as not sharing passwords and reporting suspicious activity promptly.
To further secure your account, you should enable "Alerts" for any profile changes or withdrawals. If you receive an alert for an action you did not initiate, contact the TIAA Fraud Department immediately.
Withdrawals, Loans, and Retirement Income
Accessing the funds in your TIAA account is governed by both IRS regulations and the specific provisions of your employer’s plan. Generally, you cannot withdraw employer-sponsored funds without penalty until age 59½, unless you meet specific criteria like disability or separation from service.
Required Minimum Distributions (RMDs)
As of 2026, the age for Required Minimum Distributions continues to be a focal point for retirees. You must begin taking a certain amount from your tax-deferred accounts annually once you reach the age specified by the SECURE Act 2.0 and subsequent updates. The TIAA portal includes an RMD calculator that automatically determines your required withdrawal based on your account balance and life expectancy.
Lifetime Income Options
The "Annuity" in TIAA’s name refers to the ability to turn your savings into a "paycheck for life." When you decide to retire, you can choose to "annuitize" all or part of your balance. This process involves a permanent transfer of your balance to TIAA in exchange for guaranteed monthly payments. The TIAA account dashboard provides "Income Illustrations" that show exactly how much monthly income your current balance would generate under various scenarios, such as "Life with a 20-Year Period Certain" or "Joint and Survivor" options.
Comparison of Common TIAA Account Types
| Feature | 403(b) Retirement Annuity (RA) | 403(b) Supplemental (SRA) | TIAA IRA (Traditional/Roth) |
|---|---|---|---|
| Primary Purpose | Main employer-sponsored plan | Voluntary extra savings | Personal individual savings |
| Liquidity | Often restricted (10-year payout) | Fully liquid (with tax rules) | Fully liquid (with tax rules) |
| Contribution Source | Employer and Employee | Employee only | Individual |
| TIAA Traditional Rate | Generally higher | Generally lower | Variable by vintage |
| Loan Availability | Dependent on employer plan | Usually available | Not available |
Frequently Asked Questions
How do I reset my TIAA account password?
To reset your password, visit the TIAA login page and select the "Forgot Password" link. You will be prompted to verify your identity via a one-time passcode sent to your registered mobile phone or email. In 2026, if you have biometrics enabled on the mobile app, you can often use those to authorize a password reset from a trusted device.
Can I consolidate other retirement accounts into TIAA?
Yes, TIAA allows you to roll over funds from 401(k), 403(b), or governmental 457(b) plans into a TIAA IRA or, in some cases, your current employer-sponsored plan. Consolidating accounts can simplify your Required Minimum Distributions (RMDs) and provide a clearer picture of your overall asset allocation. However, you should compare the fees and investment options of your old plan against TIAA’s offerings before initiating a rollover.
What is the "TIAA Traditional" vintage system?
TIAA Traditional interest rates are not uniform across your entire balance. Instead, the money you contribute is assigned to a "vintage" based on the time of the contribution. Each vintage may earn a different interest rate based on the economic conditions at that time. Your account statement provides a breakdown of these vintages and their respective current yields.
How do I change my contribution amount?
If you are contributing to an employer-sponsored plan like a 403(b), you usually need to change your contribution percentage through your employer’s benefits portal or HR system, rather than the TIAA website. TIAA receives the instructions from your employer and adjusts the incoming funds accordingly. For individual IRAs, you can manage contributions directly through the "Transfers" section of the TIAA portal.
Are TIAA accounts protected by the FDIC?
No, TIAA accounts are not FDIC-insured. FDIC insurance applies to bank deposit accounts. Most TIAA products are either insurance contracts (annuities) or securities (mutual funds/CREF accounts). Annuities are backed by the claims-paying ability of the issuing company (TIAA or Nuveen), while securities are subject to market risk and are typically protected by SIPC in the event of a brokerage failure, though SIPC does not protect against market losses.
Practical Recommendation for TIAA Participants
To maximize the value of your TIAA account in 2026, you should move beyond simply checking your balance. Begin by using the "Retirement Advisor" tool within the portal to run a "What-If" analysis. This tool allows you to simulate different retirement ages and contribution levels to see their impact on your projected lifetime income.
Furthermore, if you have a significant portion of your portfolio in TIAA Traditional, review your contract type (RA, SRA, or RCP). Understanding whether your fixed account is liquid or requires a multi-year payout is essential for your short-term emergency planning. Finally, ensure your "Communication Preferences" are set to digital delivery for statements and tax forms to reduce the risk of mail-based identity theft and to maintain an organized digital archive of your financial history.