Sales credit is the formal attribution of a revenue-generating transaction or pipeline milestone to a specific sales representative, team, or channel partner for compensation, quota attainment, and performance tracking. Properly structuring this attribution ensures fair commission payouts, motivates commercial teams, and prevents internal disputes over revenue ownership.
The Fundamentals of Sales Credit
In modern commercial operations, sales credit dictates how compensation plans, performance bonuses, and career advancements are calculated. When a customer executes a contract or makes a purchase, the underlying revenue rarely captures the entire story of how that deal was won. Multiple individuals often contribute to a single account across its lifecycle, spanning prospecting, technical demonstrations, contract negotiations, and ongoing account management.
To manage this complexity, organizations establish rules of engagement and compensation policies that govern how credit is split or assigned. Without a clear framework, sales teams experience friction, territory overlapping leads to channel conflict, and top performers grow frustrated by unaccounted contributions. Establishing a transparent credit system bridges the gap between raw enterprise revenue and individual accountability.
Credit vs. Revenue: Understanding the Distinction
A common misconception in revenue operations is that sales credit and recognized revenue are interchangeable terms. While they are intrinsically linked, they serve distinct organizational purposes:
- Sales Credit: A motivational and administrative metric used for quota attainment, commission calculations, and performance evaluation. It can be weighted, split, or modified based on company policies to drive specific behaviors.
- Recognized Revenue: An accounting and financial reporting metric governed by strict standards such as GAAP (Generally Accepted Accounting Principles) or IFRS (International Financial Reporting Standards). It reflects when a product or service is actually delivered and earned, regardless of who sold it.
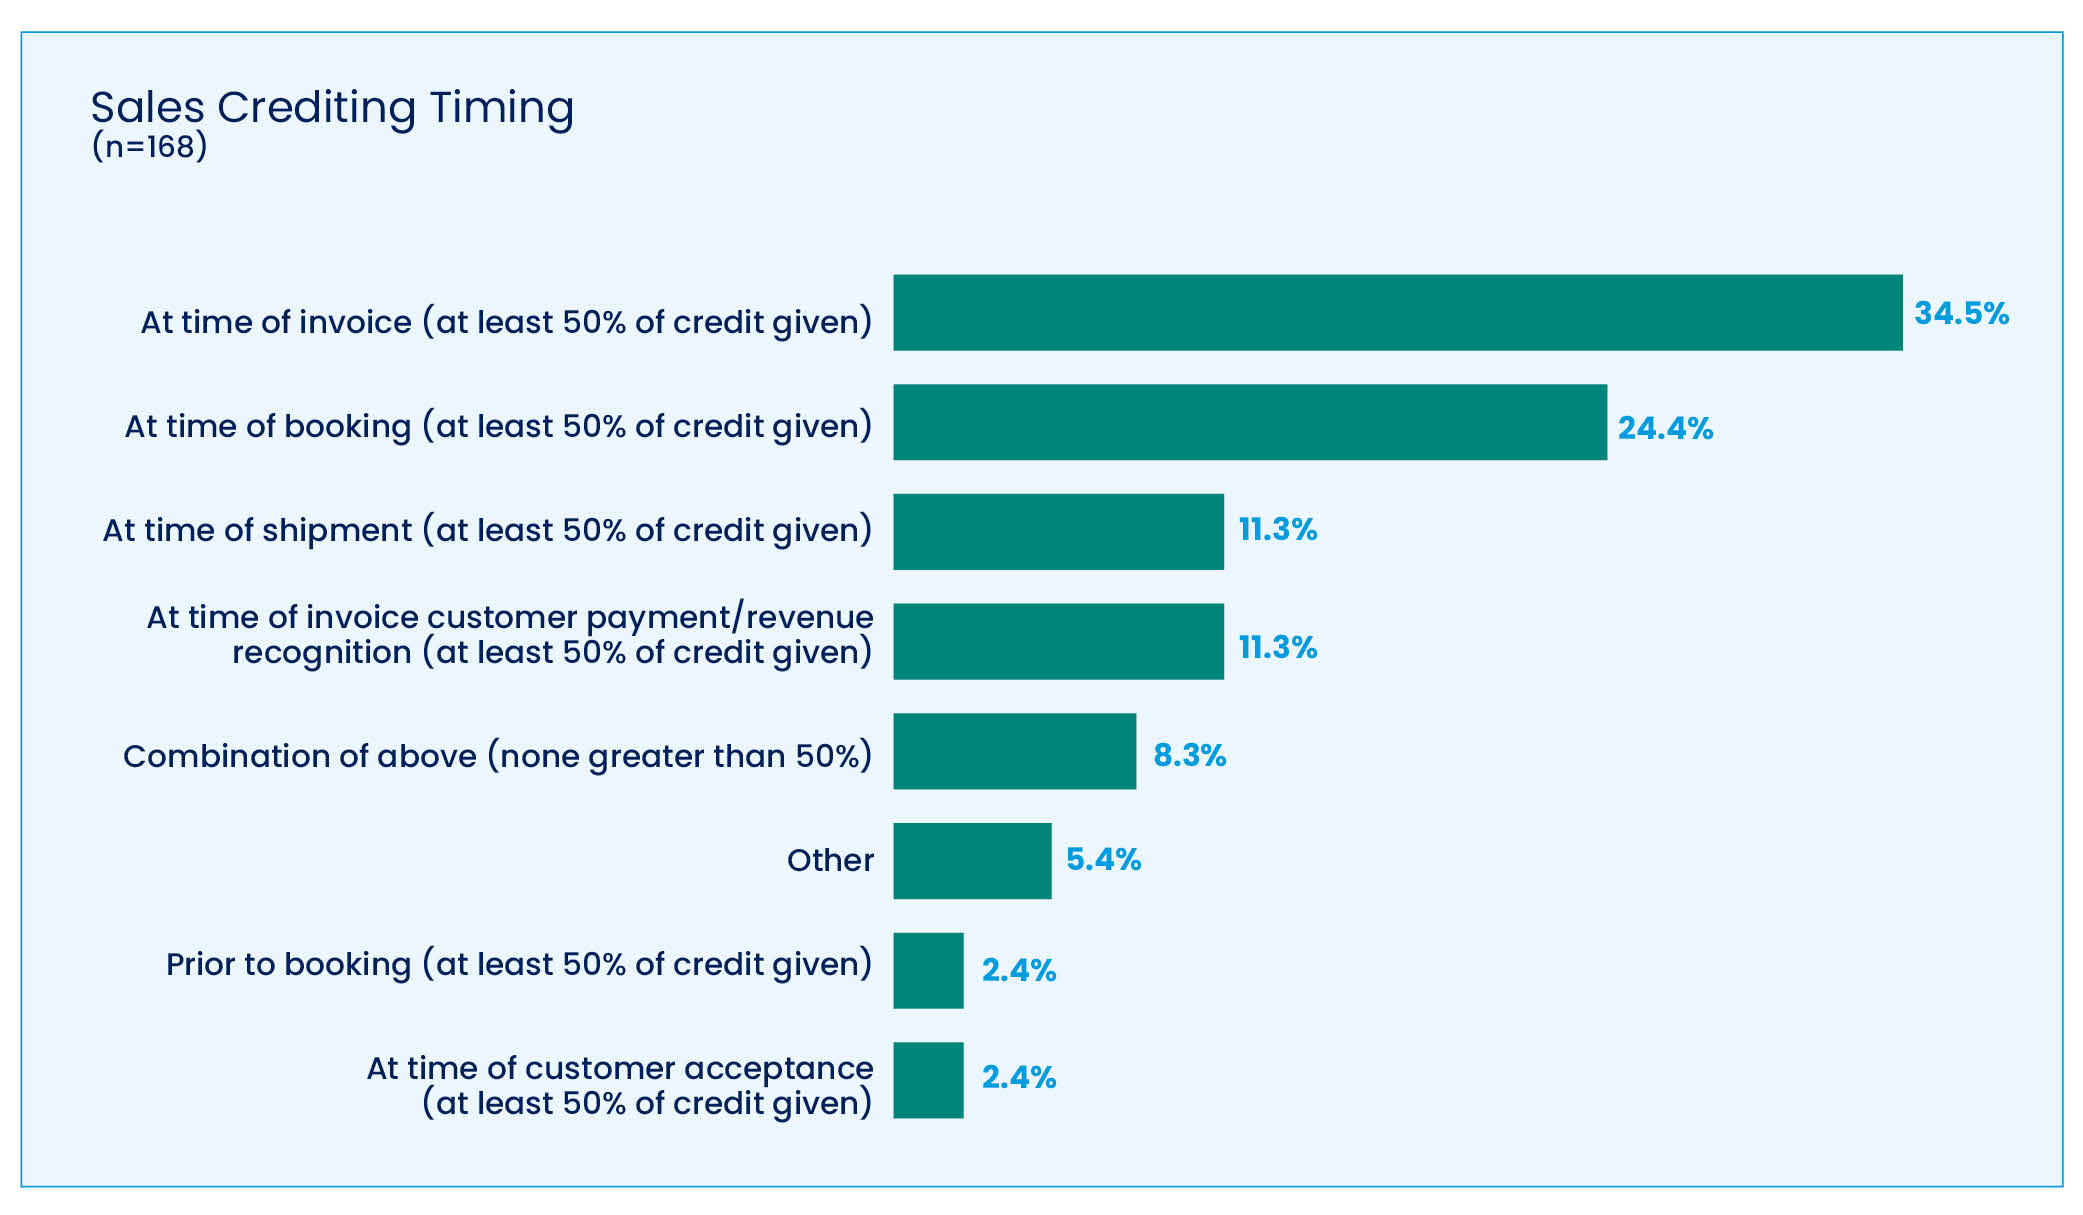
For instance, a software company might award 100% of the sales credit to an account executive upon contract signing, whereas finance recognizes that revenue ratably over a multi-year subscription term.
Core Types of Sales Credit Allocation
Organizations tailor their credit allocation models to fit their go-to-market strategies, sales cycles, and team structures. The method chosen directly influences how sales professionals collaborate and prioritize their efforts.
1. Direct Sales Credit
Direct credit is assigned to the primary representative or team that closes the deal. This is the most common model in transactional sales environments with short sales cycles and single-threaded decision-making. The primary owner shepherds the opportunity from initial discovery to contract execution and receives 100% of the credit.
2. Split Sales Credit
When multiple team members contribute to winning an enterprise account, organizations utilize split credit. Splits can be configured in various ways:
- Equal Splits: Dividing credit evenly among all participating members.
- Weighted Splits: Assigning percentages based on predefined roles or assessed contribution (e.g., 60% to the Account Executive, 40% to the Solutions Architect).
- Overlay Splits: Awarded to specialists—such as security consultants or product overlay teams—without reducing the primary representative's quota credit, often funded through a corporate overlay pool.
3. Channel and Partner Credit
In indirect sales models, credit must be managed between internal direct sales teams and external partners, such as value-added resellers (VARs), system integrators, or referral partners. Rules often dictate whether a partner receives sourcing credit, influencing credit, or fulfillment credit, ensuring both internal teams and external channels remain incentivized to cooperate.
Common Allocation Models and Policies
To maintain fairness and predictability, revenue operations (RevOps) teams implement standardized policies governing credit distribution.
| Allocation Model | Primary Use Case | Advantage | Potential Risk |
|---|---|---|---|
| Sole Ownership | High-velocity, transactional sales | Simple to administer; zero ambiguity | Discouraged collaboration on complex deals |
| Role-Based Splits | Enterprise sales involving technical pre-sales | Rewards cross-functional teamwork accurately | Can become administratively complex to audit |
| Overlay Credit | Specialized product lines or upselling | Encourages domain experts to assist deals | Can inflate total company commission liability |
| Sourcing vs. Closing | Teams with dedicated SDR and AE roles | Aligns incentives with top-of-funnel work | Disputes over handoff boundaries and timing |
Managing Credit Across the Sales Lifecycle
In extended B2B sales cycles, the handoff between departments is critical. Organizations often split credit across functional handoffs:
- Prospecting/Sourcing: Sales Development Representatives (SDRs) receive initial credit or pipeline generation credit when a meeting is booked or an opportunity is qualified.
- Execution/Closing: Account Executives (AEs) receive credit for contract value upon deal closure.
- Retention/Expansion: Customer Success Managers (CSMs) or Account Managers (AMs) receive credit for renewals, cross-sells, and upsells.
Resolving Disputes and Managing Exceptions
Even with comprehensive rules in place, edge cases arise. Complex enterprise deals often involve multi-region buying committees, unexpected executive intervention, or account reassignments due to territory restructuring.
Dispute Resolution Frameworks
Organizations typically establish a Sales Compensation Committee or a formal arbitration process to resolve grey-area disputes. Effective dispute resolution relies on:
- Documented Rules of Engagement: A readily accessible repository outlining exactly how edge cases (e.g., territory realignments, mid-flight account reassignments) are handled.
- Audit Trails: Leveraging Customer Relationship Management (CRM) and Configure, Price, Quote (CPQ) logs to verify activity history, last-touch attribution, and communication records.
- Timely Submissions: Enforcing strict windows (e.g., within 30 days of deal close) for representatives to contest credit allocations.
Frequently Asked Questions
What happens to sales credit if a customer cancels or churns?
Most compensation plans include clawback provisions. If a customer cancels within a specified window (typically 30 to 90 days), or fails to pay their invoice, the company may claw back or adjust the sales credit and associated commission paid to the representative.
Can sales credit exceed 100% of the deal value?
Yes, in organizations utilizing overlay structures or team selling models, total distributed credit may sum to more than 100% (e.g., an AE gets 100% and a specialist gets 50%). However, this is an administrative accounting practice; it does not mean the company recognizes more revenue than the contract is worth.
How do CRM systems track sales credit?
Modern CRM and sales performance management (SPM) platforms allow administrators to attach multiple split percentages to a single opportunity record. These systems automatically route the appropriate credit values to designated compensation calculation engines at the close of a fiscal period.
What is the difference between quota credit and commission credit?
While often used interchangeably, quota credit applies toward hitting a defined performance target (which may trigger accelerators or bonuses), whereas commission credit determines the actual monetary payout based on commission rates tied to specific revenue streams.
Conclusion and Next Actions
Mastering sales credit requires balancing financial governance with sales motivation. Revenue leaders must establish transparent rules, leverage automated CRM tooling to track contributions accurately, and review allocation policies regularly to match evolving go-to-market strategies.
To optimize your organization's approach, audit your current compensation plan for policy gaps, document clear rules of engagement for cross-functional deals, and ensure your CRM enforces these standards automatically before the next fiscal planning cycle.