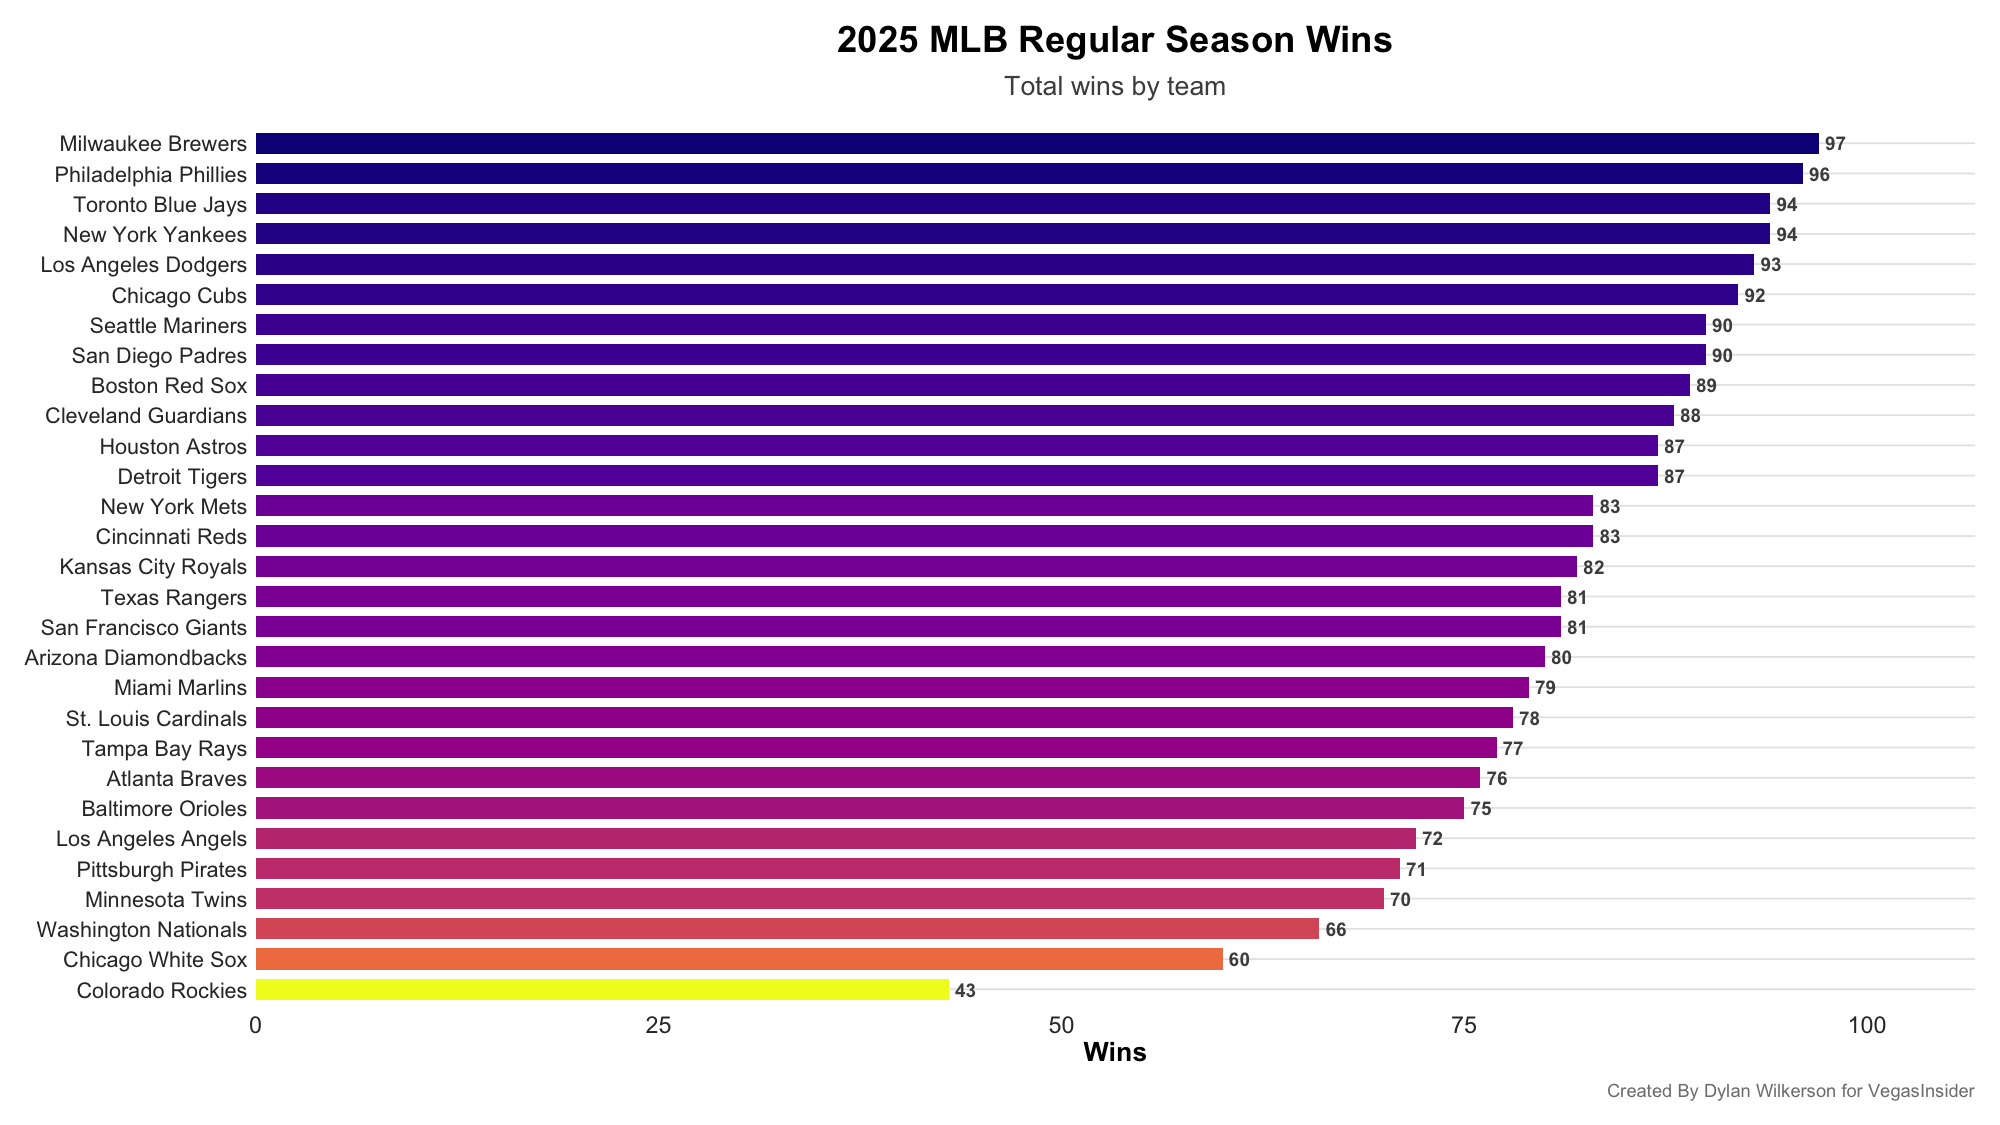
Major League Baseball payrolls reflect a complex interplay of player compensation, collective bargaining agreements, revenue sharing, and competitive strategy. While total spending varies drastically from club to club, each organization operates within a structured economic framework designed to balance competitive incentives with financial sustainability across the league.
Introduction to Major League Baseball Team Economics
Major League Baseball (MLB) payrolls represent the total financial commitment a franchise makes toward player compensation in a given season. Unlike leagues with strict, hard salary caps, MLB utilizes a luxury tax system—officially known as the Competitive Balance Tax (CBT)—which allows teams to exceed spending thresholds subject to progressive financial penalties.
Understanding how an MLB payroll functions requires looking beyond basic annual salaries. Club spending includes base salaries for players on the 26-man active roster and 40-man roster, pro-rated shares of signing bonuses, performance and award bonuses, options buyouts, and the cost of retaining players on the injured list or minor league assignments who occupy 40-man roster spots. Furthermore, teams must account for benefits, insurance, and the valuation of luxury tax thresholds when calculating their final CBT figures.
The Components of an MLB Payroll
An organization's total financial layout for a roster is built upon several distinct components. Each category impacts both the short-term competitiveness of the major league team and the long-term financial health of the franchise.
1. Active Roster and 40-Man Roster Salaries
The core of any MLB payroll is the cumulative sum of player salaries. Every player signed to a Major League contract receives a guaranteed base salary. For players on the 26-man active roster or the injured list, this salary counts fully toward the team’s payroll ledger. Players on the 40-man roster who are optioned to the minor leagues receive different salary rates, though these still contribute to overall organizational payroll calculations.
2. Signing Bonuses and Deferred Compensation
When teams sign marquee free agents or top international prospects, contracts often include upfront signing bonuses. For accounting and luxury tax purposes, signing bonuses are prorated evenly across the total life of the contract rather than counted entirely in the year the pen meets paper.
Conversely, deferred money—where a portion of a player's salary is paid out years after their playing days conclude—is heavily regulated under the current Collective Bargaining Agreement (CBA). The present-day value of deferred compensation is calculated using specific discount rates to determine its accurate impact on the Competitive Balance Tax payroll.
3. Arbitration and Pre-Arbitration Salaries
Younger players in MLB progress through a predictable economic lifecycle before reaching unrestricted free agency:
- Pre-Arbitration: Players with less than three years of service time (typically) earn salaries close to the league minimum. However, elite pre-arbitration performers may qualify for the pre-arbitration bonus pool, a centralized fund designed to reward top young talent.
- Arbitration: Players with three to six years of service time who have not signed extensions can submit salary figures to independent arbiters if they cannot agree on terms with their club. This process heavily correlates past performance with financial compensation, often causing sudden payroll spikes for clubs transitioning prospects into core veterans.
The Competitive Balance Tax (CBT) and Luxury Tax Thresholds
The defining regulatory mechanism of MLB payroll management is the Competitive Balance Tax. Rather than forbidding teams from spending past a certain ceiling, the CBT penalizes high-spending franchises by levying financial surcharges that escalate based on how many consecutive years a club has exceeded the threshold.
Threshold Tiers and Surcharges
The baseline CBT threshold adjusts according to parameters established in the reigning Collective Bargaining Agreement. Teams that cross this primary threshold face progressive taxation rates:
- First-Time Offenders: Pay a standard percentage tax on the overage amount.
- Repeat Offenders: Face higher tax rates for each consecutive year they exceed the threshold.
- Threshold Surcharges: Additional penalties apply to clubs that exceed the base threshold by significant margins (e.g., $20 million or $40 million over), which can also impact where a team selects in the subsequent Major League Amateur Draft.
How CBT Salary is Calculated
Crucially, a team's CBT payroll is not identical to the cash payroll paid out to players in a single calendar year. The CBT calculates the Average Annual Value (AAV) of each player's contract.
For example, a player signed to a five-year, $100 million contract carries a CBT salary of $20 million per year, regardless of whether they earn $10 million in year one and $30 million in year five. This AAV smoothing prevents clubs from manipulating single-year cash flows to dodge luxury tax penalties.
Payroll Disparities: Small-Market vs. Large-Market Economics
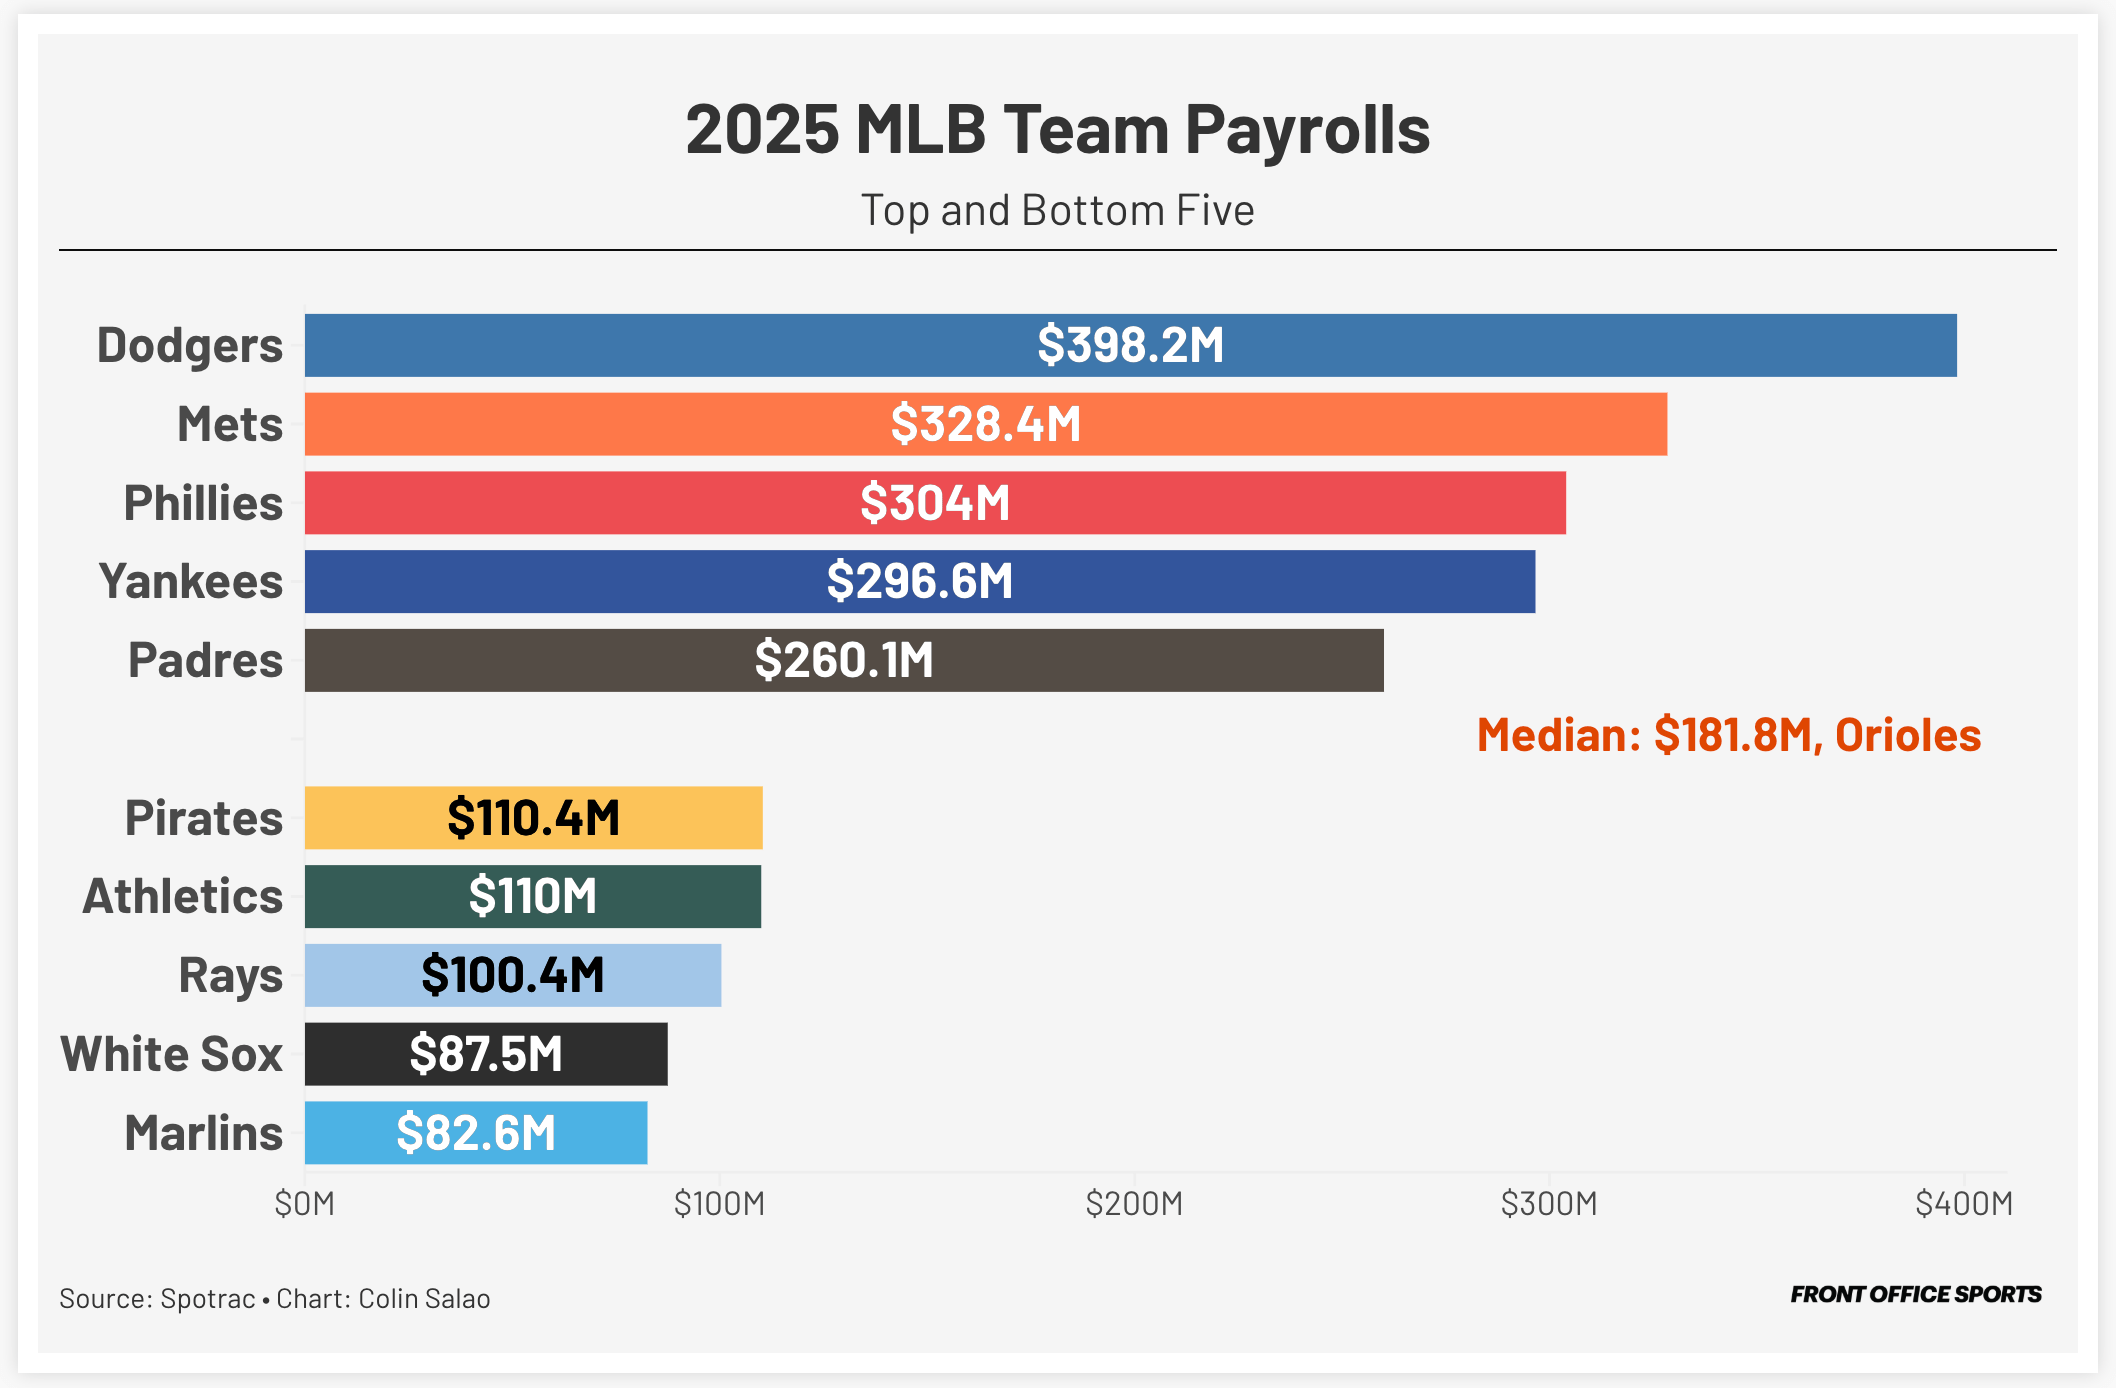
One of the most persistent discussions surrounding MLB payroll is the vast disparity in spending between top-tier market franchises and small-market clubs. Teams in major media markets—such as New York, Los Angeles, and Chicago—generate massive local television revenues, ticket sales, and corporate sponsorships, allowing them to support annual payrolls exceeding $250 million.
Conversely, small-market clubs often rely heavily on revenue sharing—a system where high-revenue teams pool a portion of their local receipts to distribute to lower-revenue organizations. While revenue sharing is intended to give every club the financial foundation to field competitive rosters, spending habits diverge significantly based on organizational philosophy, ownership willingness to absorb operating losses, and rebuilding cycles.
| Payroll Tier | Estimated Annual Range | Typical Roster Strategy | Example Franchise Profiles |
|---|---|---|---|
| Luxury Tax Payers | $240M+ | Aggressive pursuit of marquee free agents, retaining high-priced core veterans, willingness to pay CBT penalties. | High-revenue major market clubs. |
| Mid-Tier Competitors | $140M – $230M | Strategic spending, selective free-agent acquisitions, locking up core arbitration-eligible players. | Contenders with moderate local revenue streams. |
| Rebuilding / Low-Tier | Under $100M | Focus on minor league development, acquiring cost-controlled assets, trading away high-salary veterans. | Clubs prioritizing future asset accumulation. |
Frequently Asked Questions
What is the difference between cash payroll and luxury tax payroll?
Cash payroll is the actual dollar amount a franchise pays to its players in a given calendar year. Luxury tax payroll (CBT payroll) calculates the average annual value (AAV) of all players on the 40-man roster, plus prorated benefits, to determine if the club crosses league-mandated spending limits.
Do all MLB teams spend the same amount on player payrolls?
No. MLB does not feature a hard salary cap, meaning there is no strict ceiling or floor mandated by a uniform spending limit. Consequently, payrolls range from under $80 million for rebuilding teams to well over $250 million for clubs competing for championships.
What happens when a team exceeds the Competitive Balance Tax threshold?
Teams that exceed the CBT threshold must pay financial penalties to the league. These tax revenues are distributed to fund player benefits and industry growth initiatives. Furthermore, teams that exceed the threshold by wide margins face severe penalties, including having their highest draft pick moved back 10 spots.
How do signing bonuses affect an MLB team's annual payroll?
Signing bonuses do not count entirely against the payroll or the luxury tax in the year they are paid. Instead, the total bonus amount is divided evenly across the entire length of the player's guaranteed contract years, creating a predictable annual AAV impact.
Are minor league players included in major league payroll calculations?
Players assigned to the minor leagues who are not on the 40-man roster do not count toward the Major League Luxury Tax payroll, though they are supported by separate minor league compensation structures and collective agreements established in recent years.
Conclusion and Strategic Next Actions
Navigating MLB payroll requires a sophisticated balance of financial forecasting, talent evaluation, and risk management. Whether analyzing a club's pursuit of elite free agents or evaluating the long-term impact of multi-year contract structures, understanding the nuances of AAV, roster composition, and luxury tax thresholds provides a clear view of how modern baseball organizations operate. To dive deeper into specific club finances, analysts and fans should review official MLB collective bargaining documents, annual financial disclosures, and verified roster resource platforms such as Cot's Baseball Contracts or Spotrac.