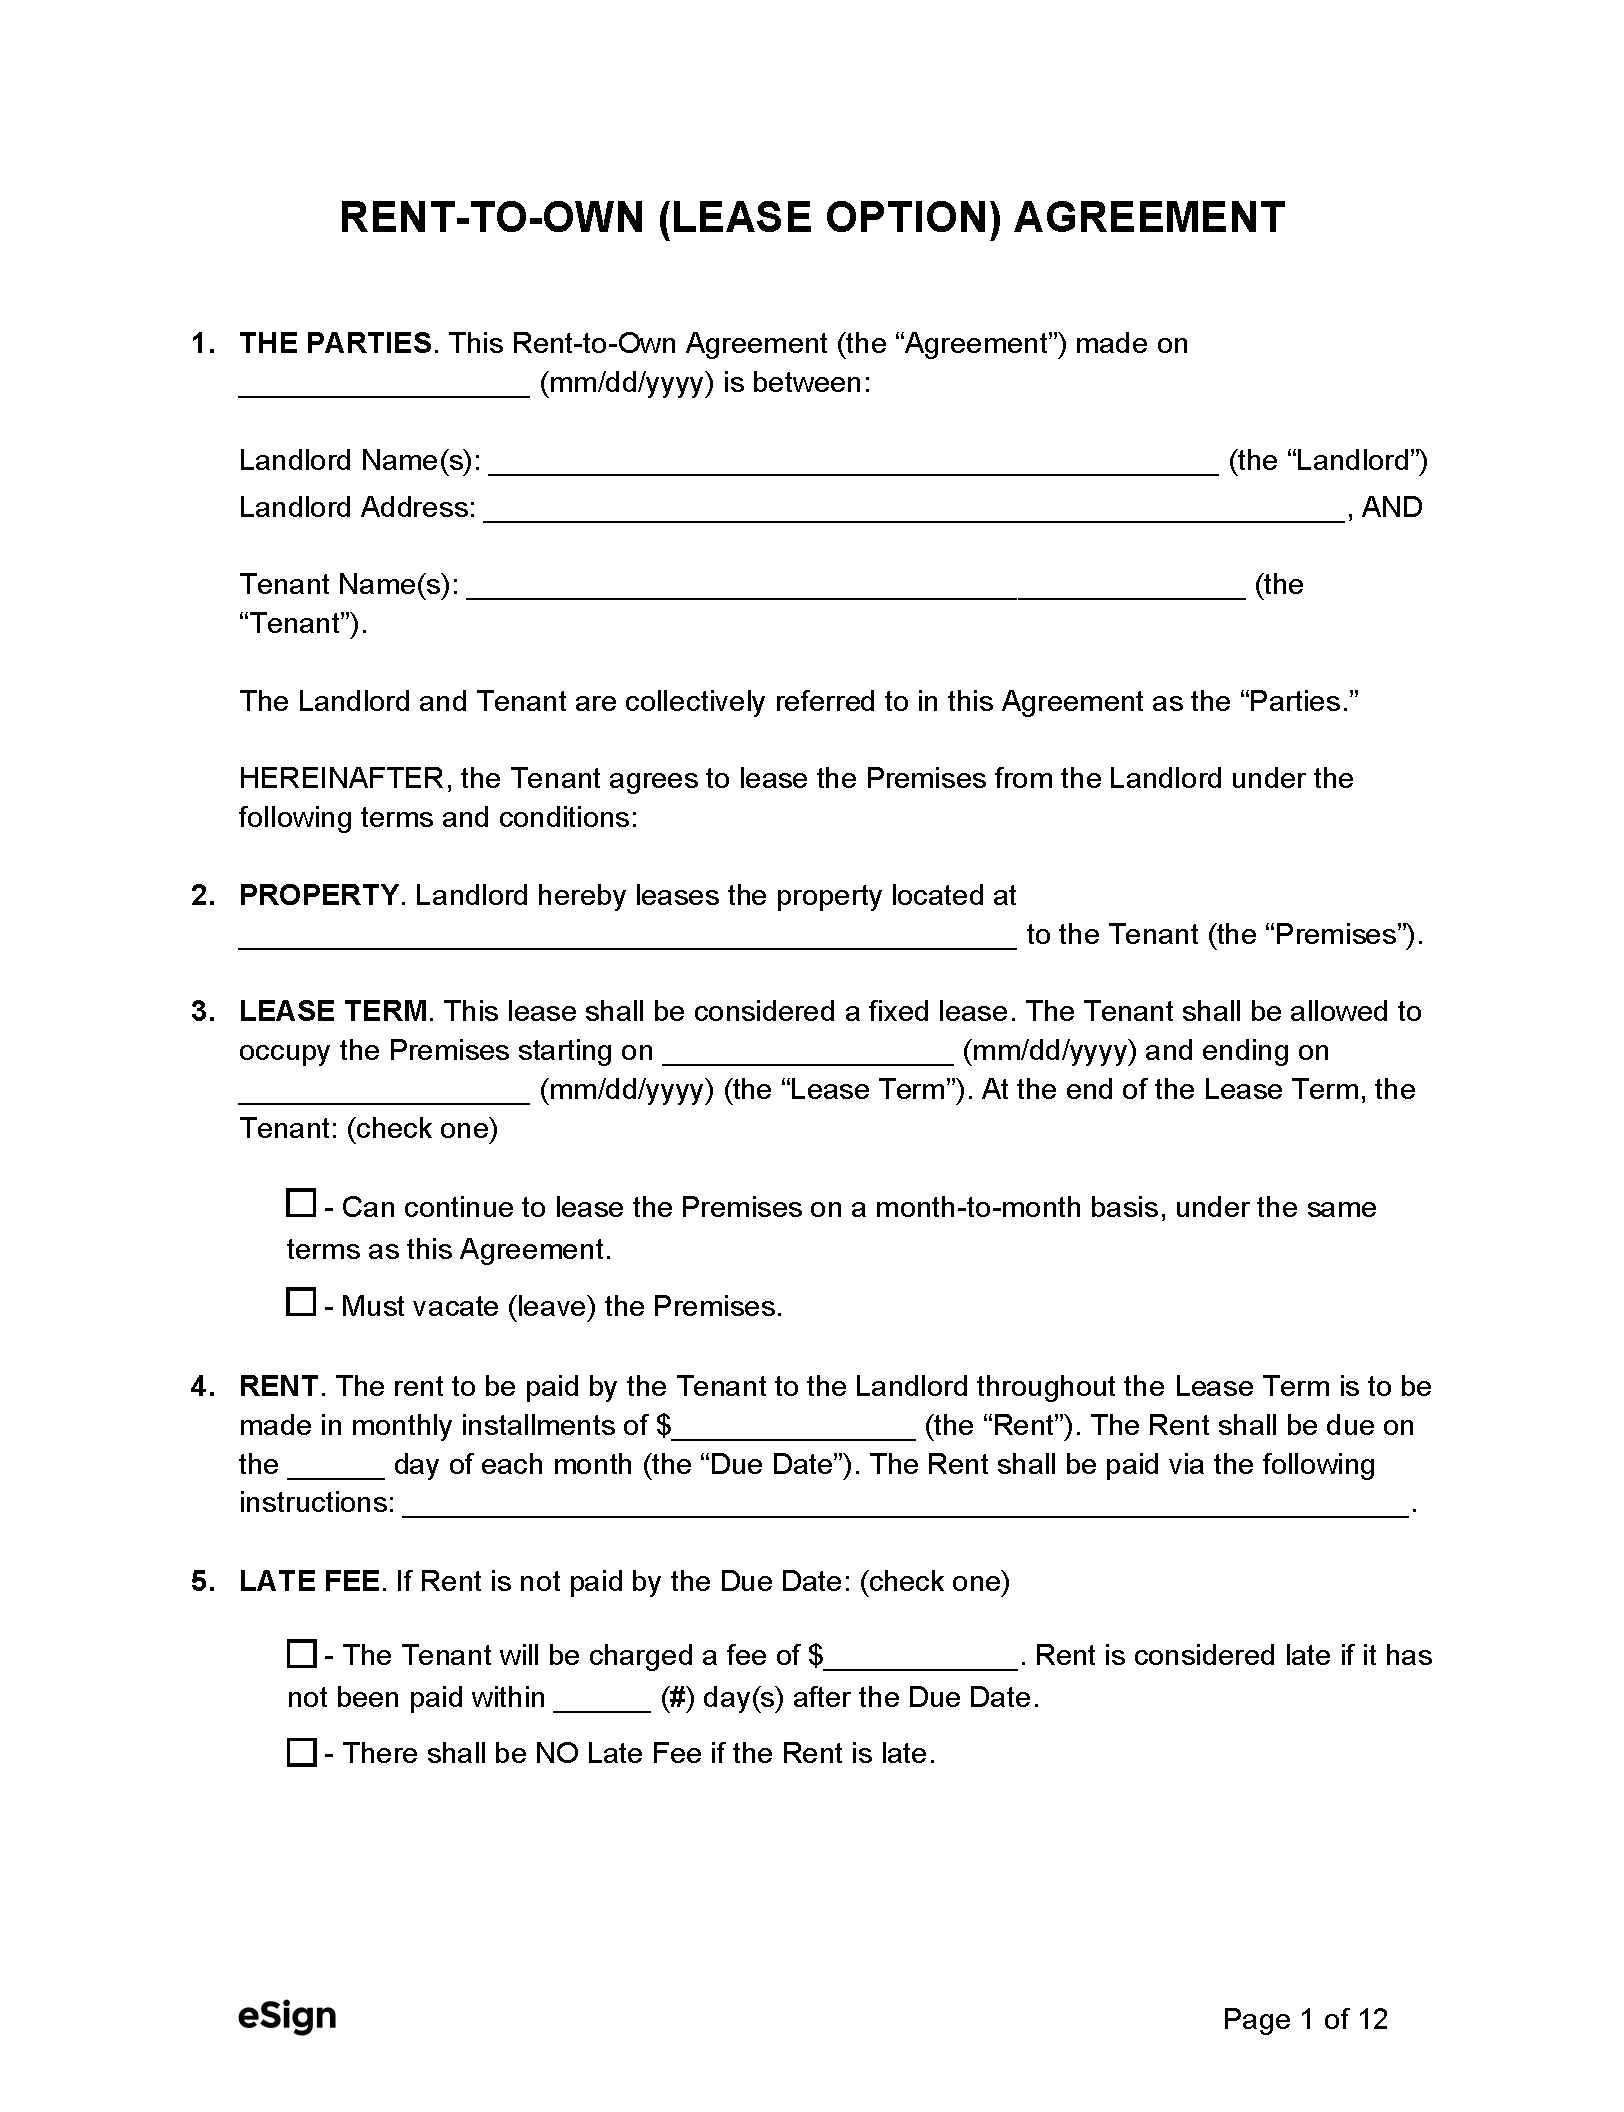
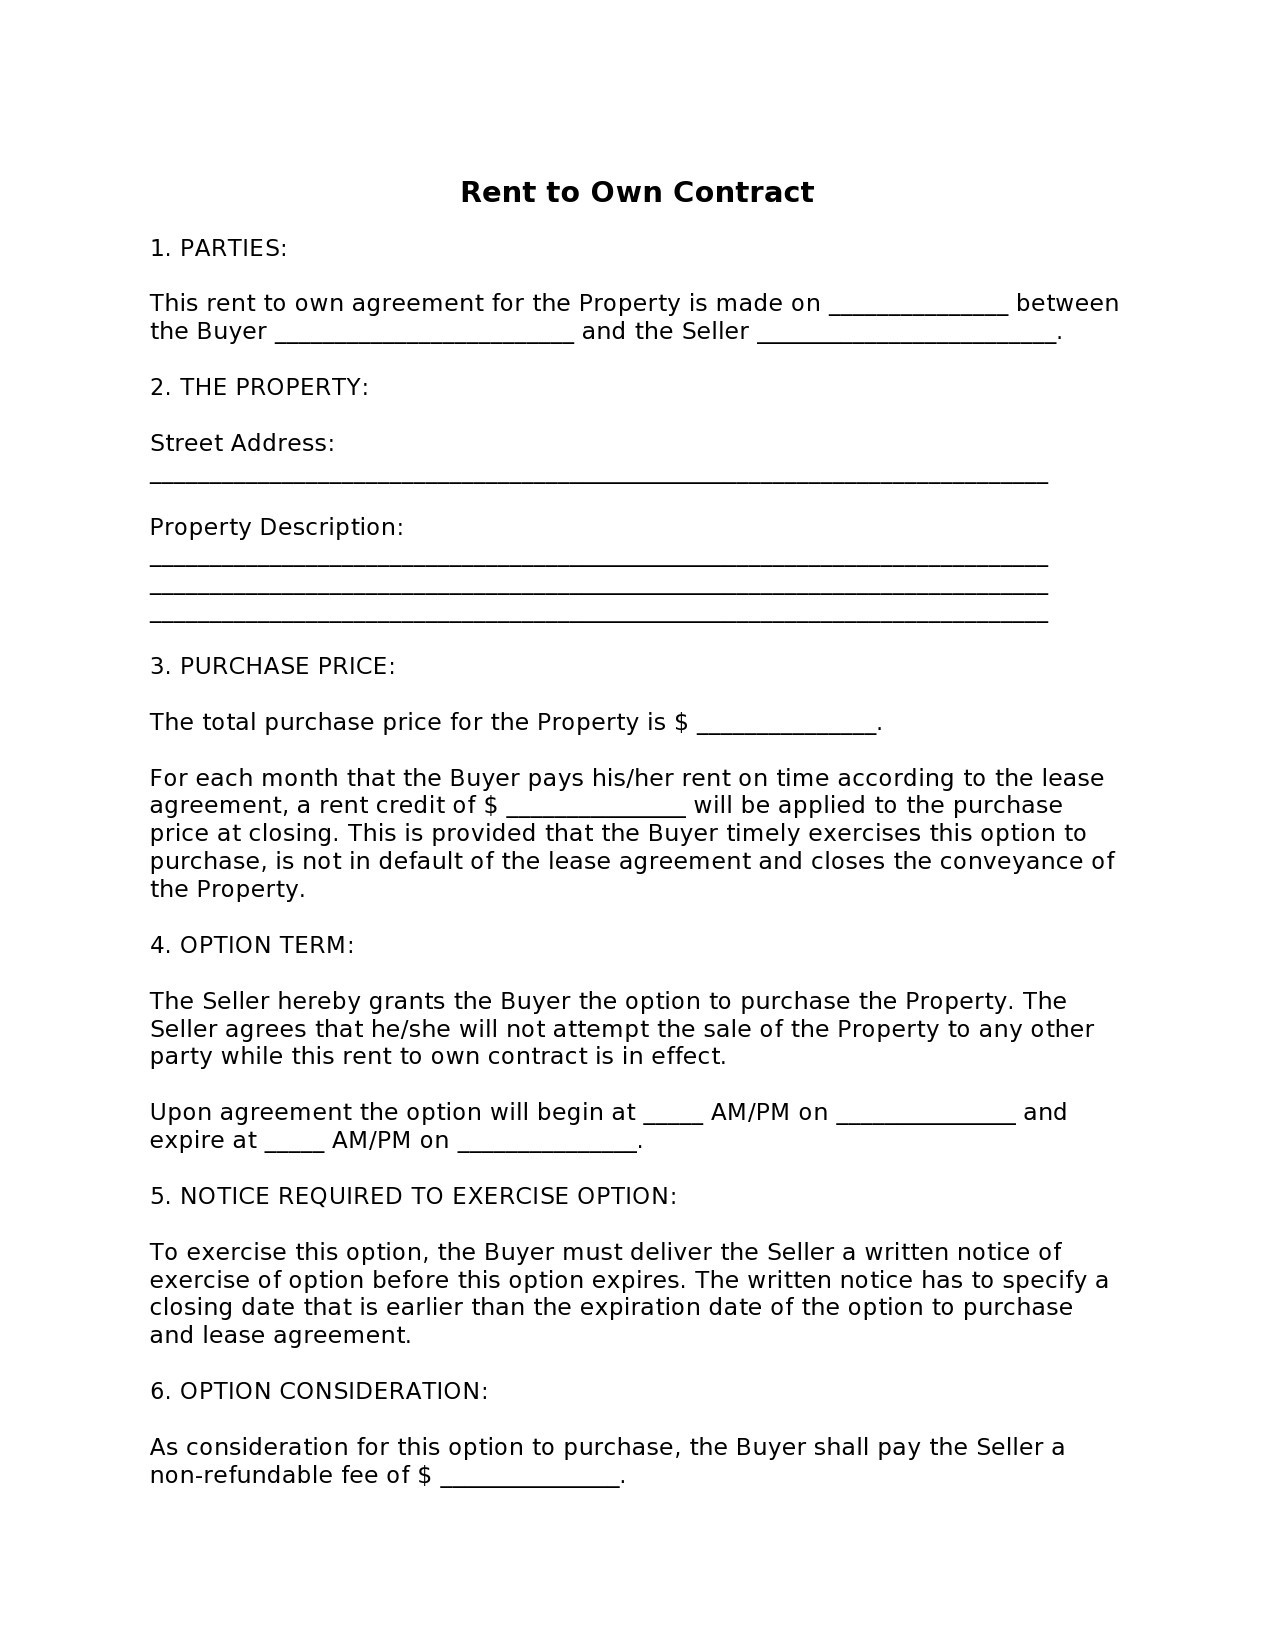
A rent-to-own agreement is a contract combining elements of a standard residential lease with an option to purchase the property at a predetermined price within a set timeframe. It provides a pathway for prospective homeowners to occupy a home while saving for a down payment or improving credit scores, though it involves unique financial risks and legal complexities that require careful verification of contract terms.
Understanding the Rent-to-Own Mechanism
At its core, a rent-to-own arrangement—often referred to as a lease-option or lease-purchase agreement—is designed to bridge the gap between renting and buying. For many in 2026, where housing affordability remains a significant hurdle, this structure offers a way to secure a property without the immediate need for a traditional mortgage approval.
The agreement is split into two primary components: the lease and the option. During the lease portion, you pay rent to the landlord, just as you would in a traditional rental. However, you also pay an additional fee known as an "option fee" or "option consideration." This fee gives you the exclusive right to purchase the home at the end of the term. In some contracts, a portion of your monthly rent payment—referred to as "rent credits"—is set aside to be applied toward the purchase price of the home when you decide to exercise your option.
Lease-Option vs. Lease-Purchase: Identifying the Difference
Distinguishing between these two formats is essential, as the legal implications for the buyer are drastically different.
- Lease-Option: This provides the buyer with the choice to purchase the property by the end of the term. If you decide not to buy the home, you generally lose the option fee and any accumulated rent credits, but you are not legally obligated to complete the purchase.
- Lease-Purchase: This is a more rigid structure where the buyer is legally obligated to complete the purchase once the lease term expires. If you fail to secure financing or decide the home no longer suits your needs, you may face severe legal or financial penalties for breach of contract.
Always review the specific language in your document. If the terminology is ambiguous, seek clarification from a real estate attorney before signing any documents.
Key Financial Components and Fees
Entering a rent-to-own agreement requires a clear understanding of the financial variables at play. Unlike a standard rental agreement, these contracts involve additional costs that are often non-refundable.
- Option Fee: This is an upfront, non-refundable payment that secures your right to buy. It typically ranges from 1% to 5% of the home's purchase price.
- Purchase Price: Most contracts lock in a purchase price at the start of the agreement. This can be beneficial if property values rise, but it may prove disadvantageous if the market declines.
- Monthly Rent Premium: Because you are effectively building equity or securing a future purchase, your monthly rent may be slightly higher than the fair market value for similar properties in the area.
- Maintenance Responsibilities: Many rent-to-own contracts shift the burden of property maintenance, repairs, and property taxes from the landlord to the tenant-buyer. You must clarify exactly which repairs are your responsibility to avoid surprise expenses.
Comparison Table: Standard Rental vs. Rent-to-Own
| Feature | Standard Rental | Rent-to-Own (Lease-Option) |
|---|---|---|
| Primary Goal | Housing occupancy | Future home ownership |
| Upfront Costs | Security deposit | Option fee + deposit |
| Maintenance | Landlord usually pays | Often tenant-buyer responsibility |
| Purchase Price | N/A | Typically fixed at contract inception |
| Equity Building | None | Possible through rent credits |
| Legal Obligation | Rent through term | Variable (Option vs. Purchase) |
Prerequisites for Success
To successfully navigate a rent-to-own arrangement, you must be prepared to manage the responsibilities of a homeowner before you actually own the home.
Credit Improvement: The primary purpose of a rent-to-own period is to improve your financial profile so you can qualify for a standard mortgage. Use this time to pay down high-interest debt, correct errors on your credit reports, and establish a consistent history of on-time payments.
Inspection and Appraisal: Never skip an independent home inspection. Since you are the likely future buyer, you need to know about latent defects in the roof, foundation, plumbing, or electrical systems. Additionally, ensure the property is appraised to verify that the locked-in purchase price is reasonable compared to the current market value in 2026.
Legal Consultation: Due to the complexity of these contracts, having a real estate attorney review the paperwork is not optional; it is a necessity. An attorney can help identify "predatory" clauses, such as those that cause you to forfeit your option fee if you are late on a single rent payment.
Potential Risks and Challenges
While rent-to-own can be a viable solution for those with credit hurdles, it is not without risk.
- Forfeiture of Funds: If you miss a payment or violate the lease agreement, the landlord may terminate the entire contract, meaning you lose the option fee and all accrued rent credits.
- Property Depreciation: If the market value of the home drops below the fixed purchase price, you may find yourself overpaying for the property.
- Financing Failure: Even if you work on your credit, there is no guarantee that you will qualify for a mortgage at the end of the term. If you cannot secure financing, you may lose your investment in the option fee and improvements.
- Landlord Default: If the landlord has a mortgage on the property and fails to make payments, the home could enter foreclosure, potentially voiding your contract despite your compliance. Verify the title status and consider requesting a memorandum of option to be recorded at the county recorder’s office.
Frequently Asked Questions
1. Is the option fee refundable? Generally, no. The option fee is the price paid for the right to remove the property from the market for a set period. Unless specifically stated otherwise in your contract, this fee is considered earned by the seller regardless of whether you choose to purchase.
2. What happens if I decide not to buy the house? In a lease-option agreement, you can simply move out at the end of the lease term. You will forfeit the option fee and any extra rent credits, but you are not obligated to complete the transaction. In a lease-purchase agreement, you may be held liable for damages or legal action if you fail to fulfill the purchase.
3. Are rent-to-own homes cheaper than buying traditionally? Usually, they are not. Because of the risk involved and the convenience of delaying a mortgage, the total cost—including rent premiums and the agreed-upon purchase price—often reflects a premium compared to the current market value.
4. How can I protect myself from a predatory seller? The best protection is a thorough contract review by a qualified attorney. Additionally, document every payment made, ensure you have a clear timeline for the option, and verify that the owner holds a clear title to the property before signing.
5. Does a rent-to-own agreement guarantee I will get a mortgage? No. A rent-to-own contract is an agreement between you and a landlord, not a guarantee of financing from a lender. You must still qualify for a conventional or government-backed loan based on your financial health at the time you decide to exercise your purchase option.
Moving Forward
If you are considering a rent-to-own path, start by evaluating your current financial readiness. Obtain a copy of your credit report, consult with a mortgage lender to see what improvements are needed for future approval, and locate a real estate attorney who specializes in lease-option law. Treat this arrangement as a business transaction, not a casual rental. By conducting your due diligence, inspecting the property, and ensuring that every financial incentive is written clearly into your contract, you can use the rent-to-own model as a legitimate stepping stone to homeownership.