Dynamic Currency Conversion (DCC) is a financial service that allows international cardholders to pay for goods and services in their home currency at the point of sale or online checkout, rather than the local currency of the merchant. While it offers immediate price transparency, DCC typically involves significantly higher exchange rates and hidden markup fees compared to processing the transaction in the local currency.
What is Dynamic Currency Conversion (DCC)?
Dynamic Currency Conversion, commonly referred to as a DCC payment, is a process that occurs when a consumer uses a foreign credit or debit card at an international terminal, ATM, or e-commerce checkout. The transaction software automatically detects the card’s Country Identification Number (BIN) and recognizes that the card was issued in a different country than the operating currency of the merchant terminal.
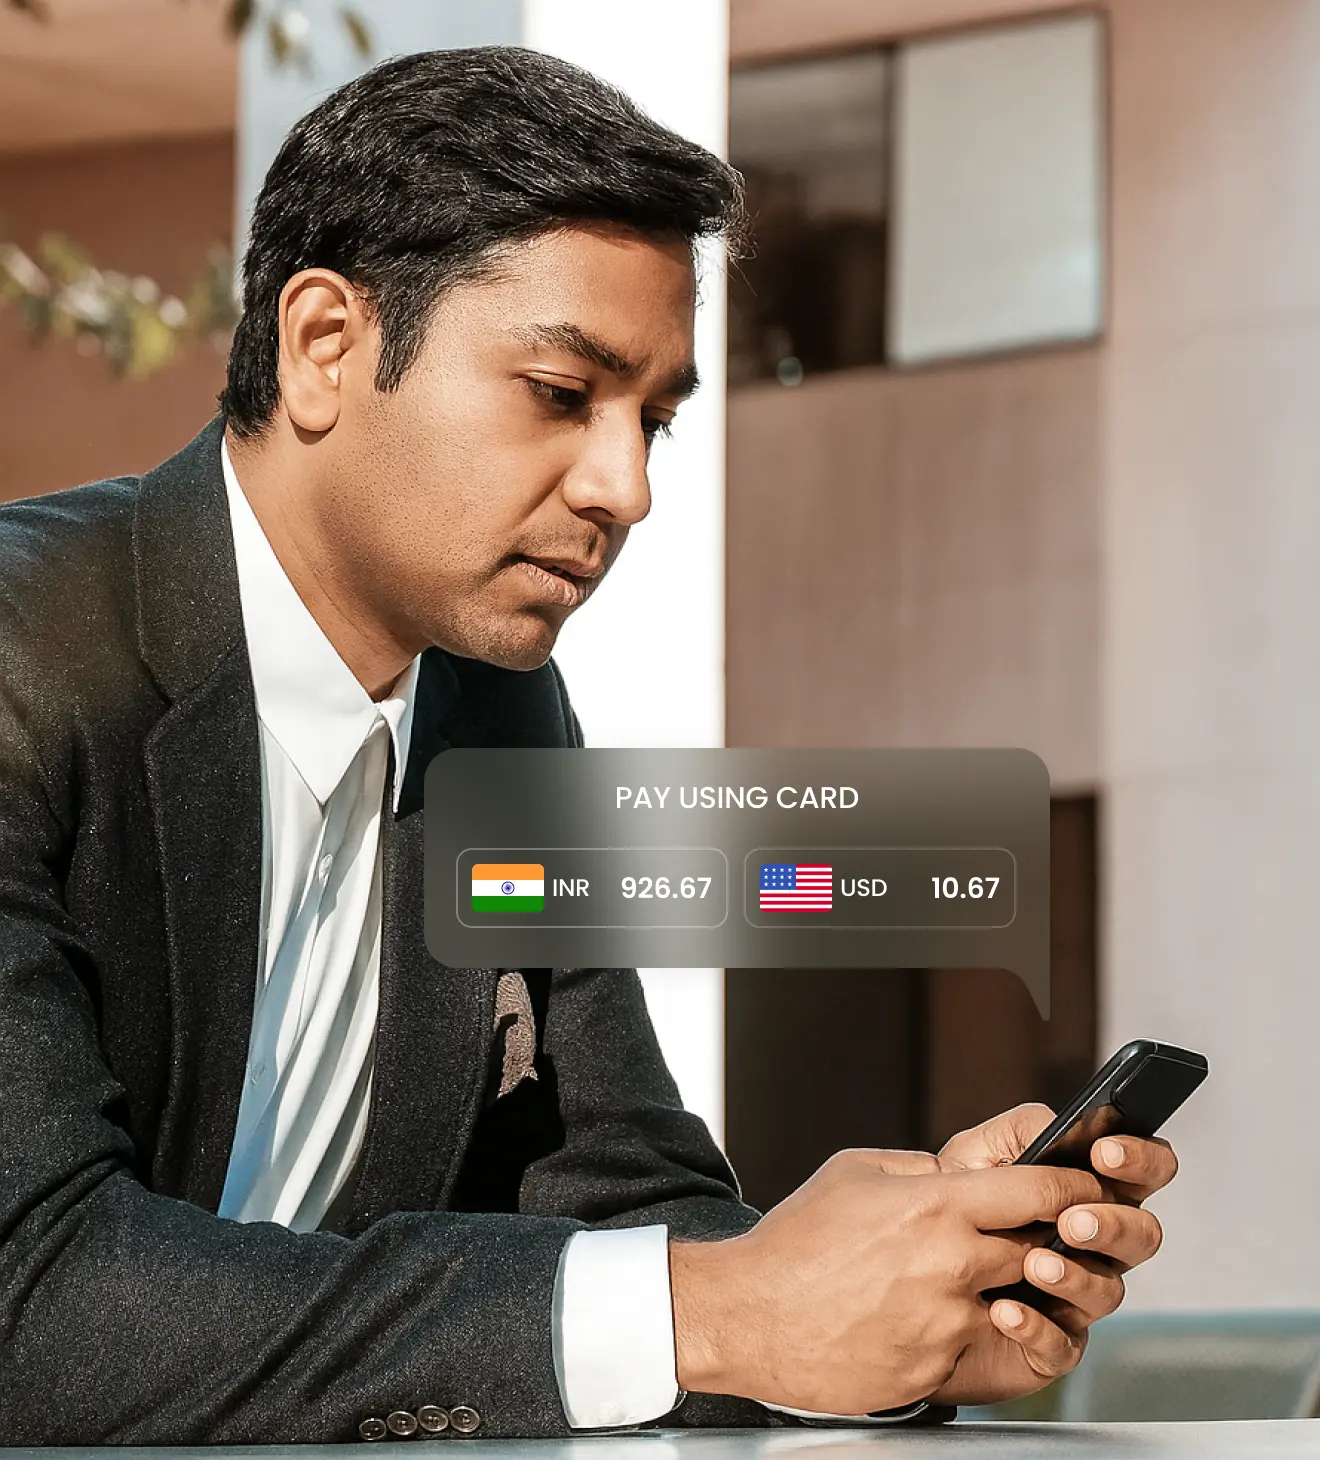
The terminal then offers the cardholder a choice: complete the transaction in the local currency of the country they are visiting, or convert the amount immediately into their home currency based on a real-time exchange rate provided by the merchant's payment processor.
While this mechanism seems helpful for travelers trying to calculate exact spending without mental math, it functions as a distinct financial product managed by third-party processors rather than the cardholder’s issuing bank. Understanding how this system works requires looking at the mechanics of currency exchange, the roles of participating financial institutions, and the distinct difference between DCC and standard multi-currency processing.
The Mechanics Behind a DCC Transaction
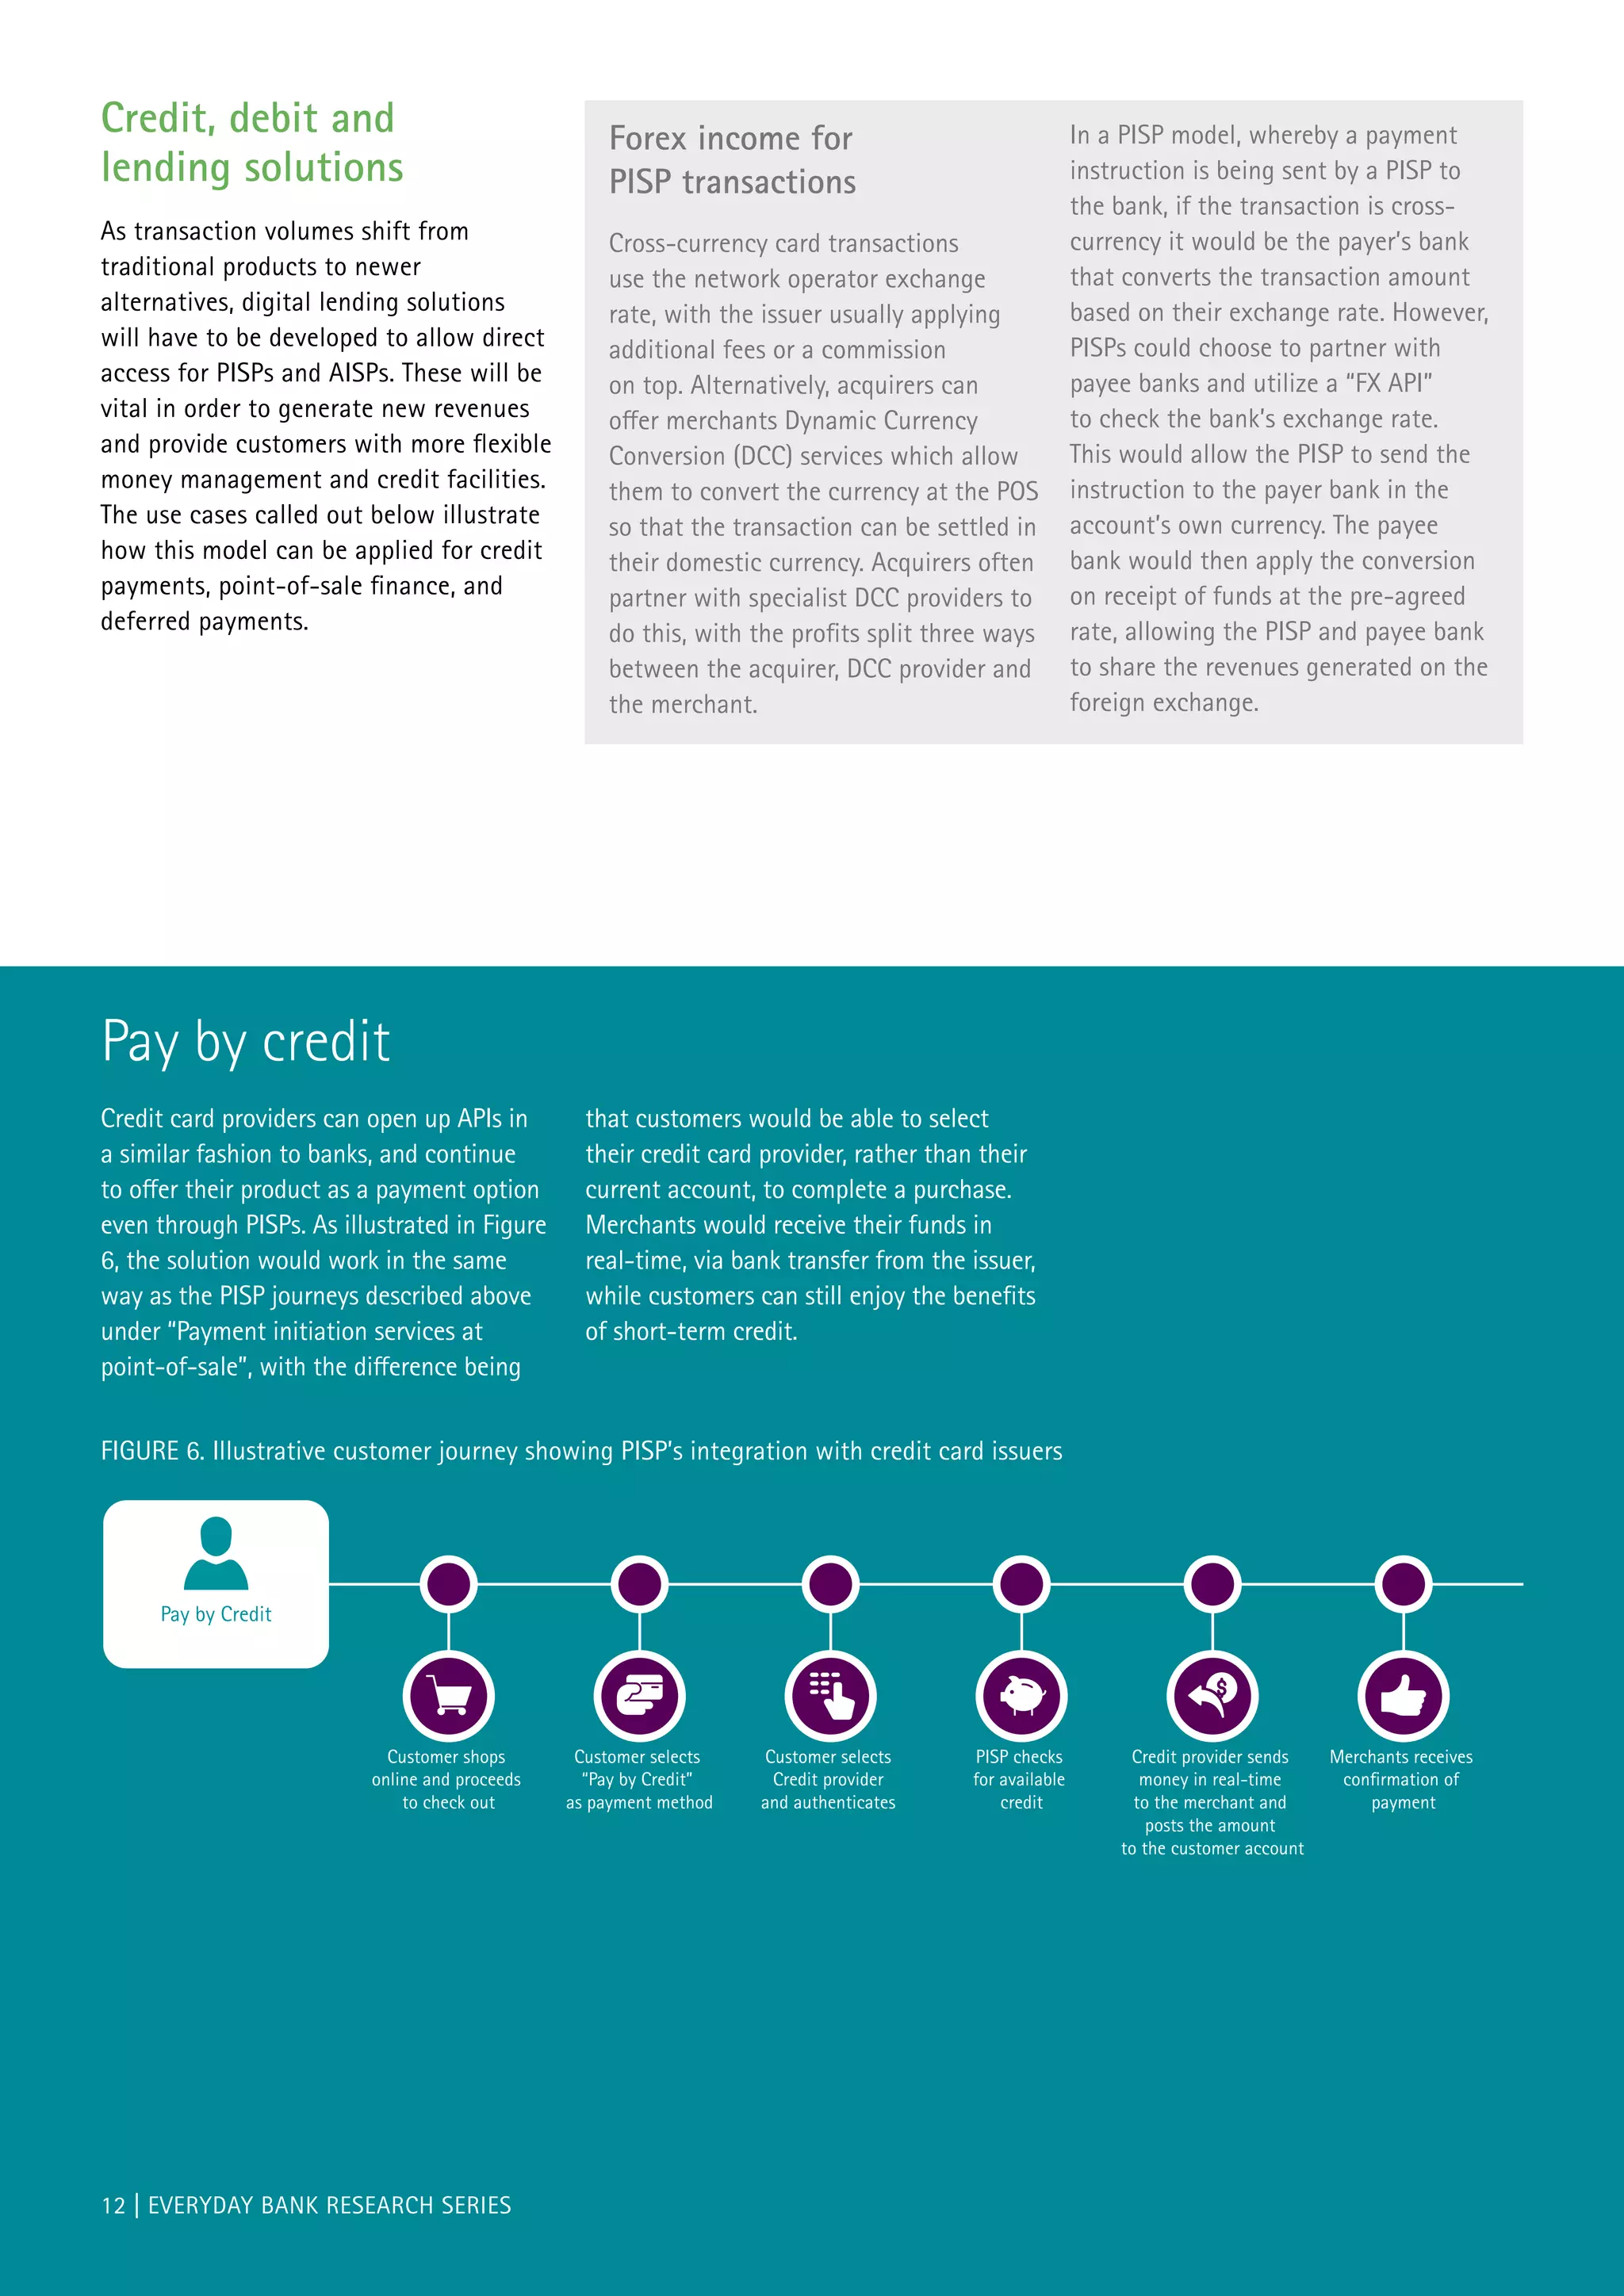
When a DCC payment is triggered, the point-of-sale (POS) terminal or payment gateway communicates with a dynamic currency conversion provider. This provider establishes a proprietary exchange rate for the day, which invariably includes a substantial markup—frequently ranging from 3% to over 10% above the interbank exchange rate or the rate offered by major card networks like Visa or Mastercard.
The sequence of a typical transaction unfolds as follows:
- Card Insertion or Swipe: The cardholder presents a foreign-issued card at a payment terminal.
- BIN Recognition: The payment terminal reads the card data and identifies the issuing country and home currency.
- Prompt Generation: The terminal displays the transaction amount in both the local currency and the cardholder's home currency, often prompting the user to select one.
- Processing: If the cardholder selects DCC, the transaction is processed and settled in the home currency. The merchant and the DCC provider split the resulting conversion markup fee. If the cardholder declines, the transaction processes in the local currency, and their home bank handles the conversion later.
DCC vs. Standard Home Currency Processing
It is vital to distinguish between a DCC payment and standard local currency processing with a foreign transaction fee applied by an issuing bank.
| Feature | Dynamic Currency Conversion (DCC) | Standard Local Currency Processing |
|---|---|---|
| Where Conversion Occurs | At the point of sale (merchant terminal or gateway) | By the card-issuing bank after settlement |
| Exchange Rate Set By | The merchant’s DCC service provider | Visa, Mastercard, or the issuing bank |
| Markup Transparency | Often obscured within the presented exchange rate | Defined in the cardholder's account agreement |
| Revenue Generation | Shared between the merchant and the DCC provider | Retained entirely by the card network and issuer |
| Average Cost | Generally higher (3% to 10%+ markup) | Generally lower (0% to 3% foreign transaction fee) |
Why Merchants Implement DCC Payments
Merchants—particularly hotels, high-end retailers, car rental agencies, and international airlines—frequently enable DCC payment options on their terminals to generate additional revenue. Payment service providers market DCC solutions to merchants as a lucrative value-added service.
Revenue Sharing Models
The financial incentive for merchants is clear: commission sharing. When a cardholder opts for a DCC payment, the third-party provider collects a markup fee on the exchange rate. A percentage of this markup revenue is kicked back to the merchant as a rebate or commission. For businesses with high volumes of international clientele, these kickbacks can offset a significant portion of their monthly merchant processing fees.
Customer Service and Psychological Comfort
Proponents of DCC argue that it provides cardholders with price certainty. When traveling abroad, consumers may struggle to calculate exchange rates mentally, leading to hesitation at checkout. Seeing the exact final price in their native currency removes ambiguity.
However, critics and consumer protection advocates argue that this psychological comfort comes at an excessive financial cost, and the prompts on terminals are often designed to confuse or rush the consumer into selecting the more expensive option.
The Hidden Costs and Disadvantages for Consumers
For cardholders, a DCC payment is rarely the economical choice. Although the convenience of knowing the exact home currency amount on the receipt is appealing, the financial mechanics heavily favor the merchant and the conversion provider at the expense of the consumer.
Inflated Exchange Rates and Markups
The primary drawback is the exchange rate. DCC providers do not use the mid-market or wholesale exchange rate. Instead, they apply a retail exchange rate burdened with a heavy markup. Furthermore, some DCC providers charge a flat transaction fee in addition to the percentage-based markup.
When a cardholder declines DCC and opts for the local currency, the conversion is handled by their card network (e.g., Visa or Mastercard) or their issuing bank. These institutions typically use rates much closer to the interbank rate, even if the bank assesses a modest foreign transaction fee (usually between 1% and 3%). Comparing a 3% bank fee to a DCC markup that can easily exceed 8% reveals why financial advisors universally recommend declining DCC.
The Psychology of Terminal Prompts
Payment terminal interfaces are frequently optimized to maximize DCC adoption. Common tactics include:
- Highlighting the "Pay in Home Currency" button in green while placing the "Pay in Local Currency" button in grey or hiding it behind a secondary menu.
- Framing the local currency option as a risk ("Pay in local currency subject to unknown exchange rate fluctuations") while framing DCC as secure and transparent.
- Configuring the terminal to default to DCC if the user does not actively press a button within a short timeframe.
How to Handle DCC Payments at Checkout
Navigating international transactions requires vigilance to avoid paying unnecessary conversion markups. Whether traveling physically or shopping online across borders, consumers can protect themselves by following disciplined checkout habits.
- International Checkout
- Card Inserted / Online Cart
- Does the terminal/screen prompt for Home Currency vs. Local Currency?
- YES: SELECT LOCAL CURRENCY (Decline DCC markup) -> Processed via Card Network (Fairer interbank rate)
- NO: Proceed with standard local transaction
Best Practices for Cardholders
- Always Choose Local Currency: When prompted on a POS terminal or online payment gateway to choose between your home currency and the local currency, select the local currency.
- Review Receipts Carefully: Examine physical or digital receipts to confirm that the transaction was billed in the local currency (indicated by the local currency code, such as EUR, JPY, or GBP) rather than your home currency (USD, CAD, AUD, etc.).
- Use Cards with No Foreign Transaction Fees: Equip yourself with travel credit cards or debit cards that explicitly waive foreign transaction fees. Pair these cards with the rule of always declining DCC to ensure the lowest possible conversion cost.
- Understand Online Checkouts: When purchasing from international websites, look for currency selectors before checking out. Many websites automatically convert prices based on your IP address or geo-location. Force the website to display and charge in the merchant's local currency if possible.
Technical and Regulatory Standards Governing DCC
The operation of DCC payments is governed by strict compliance rules established by major payment card networks, including Visa and Mastercard, as well as national and regional financial regulators. These rules are designed to ensure transparency and protect consumer rights.
Card Network Regulations
Both Visa and Mastercard mandate strict guidelines for merchants and terminal operators utilizing DCC:
- Informed Consent: The cardholder must be given a clear, un-coerced choice between the local currency and the home currency. Pre-selected defaults that favor DCC without user input are strictly prohibited.
- Rate Disclosure: The terminal or checkout screen must clearly display the applicable exchange rate, the markup percentage applied compared to the European Central Bank (ECB) rate (for transactions in Europe), and any applicable fees.
- Right to Refund: Cardholders who believe they were subjected to DCC without proper consent or disclosure have the right to dispute the transaction through a formal chargeback process with their issuing bank, citing lack of informed consent.
European Union Regulations
In the European Union, regulations such as the Cross-Border Payments Regulation (Regulation (EU) 2019/518) introduced stringent requirements for DCC providers operating within the EEA. Providers must disclose all currency conversion charges transparently as a percentage markup over the latest available foreign exchange reference rates issued by the European Central Bank. This has significantly increased transparency across European merchants, though vigilance at the terminal remains essential.
Frequently Asked Questions
What happens if I accidentally accept a DCC payment?
If you accidentally select DCC at checkout, the transaction will process in your home currency with the inflated markup applied. You cannot reverse the conversion at the terminal once the transaction is completed. While you can technically file a chargeback if the merchant failed to disclose the rate or forced the selection, standard charges accepted via explicit button presses are generally non-refundable through dispute channels.
Are online merchants allowed to use DCC?
Yes, e-commerce gateways frequently utilize DCC. When shopping on foreign websites, the checkout page may automatically display prices in your local currency based on your IP address. Look for a drop-down menu on the website to switch the billing currency back to the merchant's local currency before submitting your payment information.
Why do ATMs also offer DCC?
International ATMs frequently use DCC when foreign cardholders attempt to withdraw cash. The ATM will calculate the withdrawal in your home currency and offer a heavily marked-up exchange rate. Just like at retail terminals, you should always decline DCC at ATMs and choose to be billed in the local currency of the destination country.
Do business credit cards avoid DCC markups?
No. Business credit and debit cards are subject to the same BIN recognition and terminal prompts as consumer cards. Even if a business card offers high reward multipliers or waives bank-level foreign transaction fees, it remains susceptible to DCC markups if the cardholder selects the home currency option at the point of sale.
How can I calculate whether DCC is ever cheaper?
DCC is virtually never cheaper. Because the exchange rate markup is set entirely by the processor to extract profit, and because major card networks (Visa and Mastercard) secure wholesale interbank rates that independent DCC providers cannot beat, declining DCC and letting your home bank handle the exchange is mathematically superior in almost all cases.
Conclusion and Next Actions
A DCC payment is a convenient option for merchants and processors looking to monetize international traffic, but it represents an unnecessary expense for consumers. To protect your finances when traveling or shopping across borders, make it a strict rule to always decline currency conversion at the terminal or checkout screen, ensuring your transactions are processed in the local currency. Before your next trip, review your wallet's credit and debit card agreements to identify which cards waive foreign transaction fees, and rely exclusively on those cards for international purchases.
Metadata: