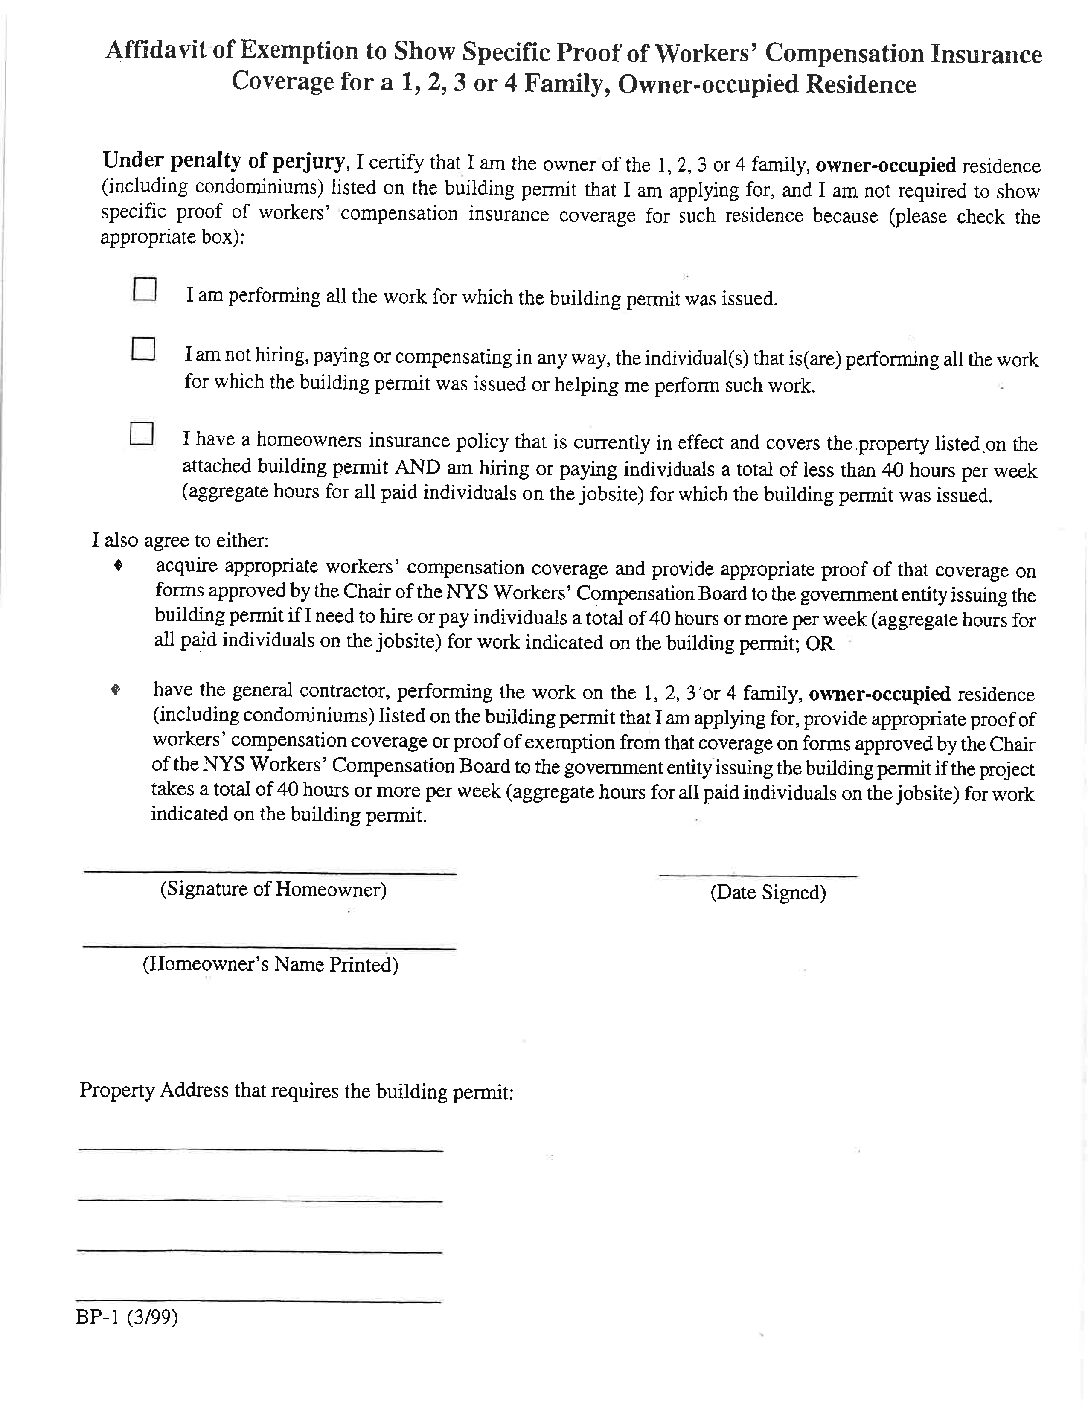
A workers' compensation exemption allows specific categories of business owners, corporate officers, independent contractors, or members of limited liability companies to legally opt out of carrying workers' compensation insurance coverage for themselves, though rules and eligibility vary significantly by jurisdiction.
Navigating the complexities of business insurance requires a deep understanding of statutory requirements, state regulations, and liability protections. For many business owners, sole proprietors, and corporate executives, mandatory workers' compensation insurance represents a substantial recurring operational expense. When business structures involve few or no traditional employees, the requirement to cover oneself can feel redundant or overly burdensome. To address this, most jurisdictions provide statutory mechanisms known as workers' compensation exemptions. These exemptions are not blanket permissions to ignore labor laws; rather, they are legally defined allowances that permit certain individuals to decline coverage for their own injuries on the job, provided they meet strict structural and procedural criteria.
Securing a valid exemption involves navigating administrative hurdles, filing official state forms, and understanding the delicate balance between saving on premium costs and absorbing personal financial risk. Failing to follow the statutory guidelines precisely can result in severe financial penalties, stop-work orders, and personal liability in the event of a workplace accident. Business owners must carefully weigh these factors against their risk tolerance and contractual obligations before pursuing an exemption.
Defining Workers' Compensation Exemptions
At its core, a workers' compensation exemption is a formal, legally recognized status that frees a business entity or a specific individual within that entity from the mandate to purchase and maintain workers' compensation insurance. In the context of business law, workers' compensation is a form of insurance providing wage replacement and medical benefits to employees injured on the job in exchange for relinquishing the employee's right to sue the employer for negligence.
However, state statutes traditionally view business owners, partners, and corporate officers differently than W-2 employees. Because these individuals often hold ownership stakes, control operations, or make executive decisions, they may choose whether to extend this no-fault safety net to themselves. An exemption allows them to step outside the pool of covered individuals.
It is vital to distinguish between exempting oneself or corporate officers and the legal obligation to cover standard employees. In virtually all jurisdictions, if a business employs even a single non-exempt W-2 employee—or meets specific thresholds regarding the number of employees—the employer must maintain a valid workers' compensation policy for those workers. The exemption typically applies solely to the qualifying owners, officers, members, or contractors named on the waiver certificate, leaving the underlying employee coverage mandate intact.
Jurisdictional Frameworks and State-by-State Variance
Workers' compensation is primarily regulated at the state level rather than the federal level, with the exception of specific federal programs like the Federal Employees' Compensation Act or the Longshore and Harbor Workers' Compensation Act. Consequently, there is no universal federal standard for a workers' compensation exemption. Every state maintains its own industrial commission, workers' compensation board, or department of labor that dictates who can opt out and under what conditions.
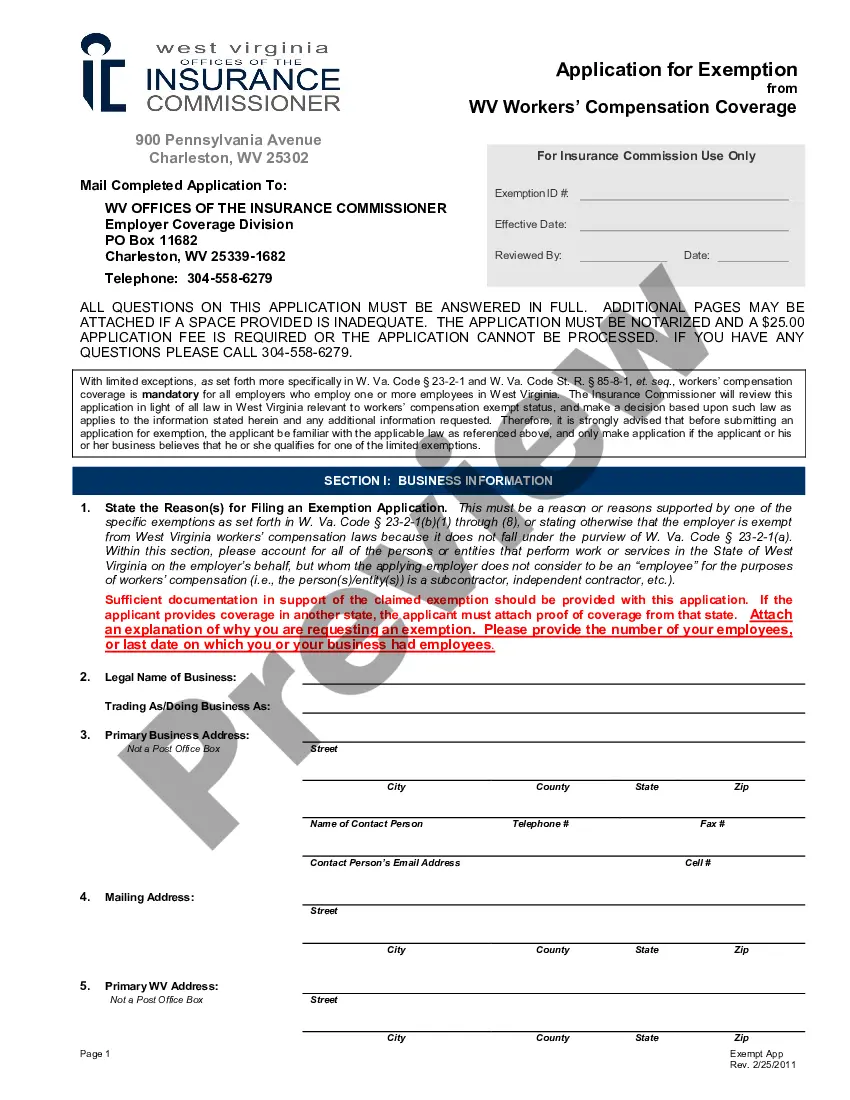
The variance between state laws is substantial. For example, some states permit sole proprietors and partners to opt out automatically by virtue of their business classification, while others require formal application, notarized documentation, and the payment of a processing fee. Certain states limit officer exemptions to corporations with a maximum number of shareholders—often five or fewer—while others allow it for corporations of any size as long as the officers own a specified percentage of stock, such as 10% or 25%.
| Business Structure | Common Exemption Eligibility | General Requirements & Conditions |
|---|---|---|
| Sole Proprietorship | Frequently eligible | Must not have covered employees; may require formal election filing with the state department of labor. |
| Limited Liability Company (LLC) | Varies widely by state | Members and managers owning a specific percentage (e.g., 20% or more) may qualify; active participation in management is often required. |
| Corporation (C-Corp / S-Corp) | Generally eligible for officers | Officers must also be shareholders owning a minimum percentage of stock; maximum limits on total officer count may apply in some states. |
| Independent Contractor | Dependent on statutory tests | Must meet strict independent contractor criteria (e.g., control over work, own tools); may require a specific exemption certificate. |
Understanding these state-specific nuances is critical. Operating under the assumption that an exemption applies in one state simply because it was valid in another can lead to severe compliance violations. Business owners expanding operations across state lines must review the local statutes governing insurance mandates for every geographic location where work is performed.
Eligibility Criteria Across Business Structures
The ability to claim a workers' compensation exemption depends heavily on the legal formation of the business. States categorize entities differently, and the statutory language reflects the degree of control and financial ownership an individual holds within that entity.
Sole Proprietorships and Partnerships
In a sole proprietorship, the owner and the business are legally synonymous. Some states automatically exclude sole proprietors from mandatory workers' compensation requirements because an individual cannot legally enter into an insurance contract with themselves. However, if the sole proprietor hires subcontractors or W-2 employees, the landscape changes. Partnerships face similar rules; general partners are often excluded by default unless they elect coverage, but managing partners must ensure they comply with state definitions regarding active labor versus passive investment.
Limited Liability Companies (LLCs)
LLCs represent one of the most complex categories for workers' compensation exemptions. Because LLCs blend corporate protections with partnership-style flexibility, states treat member-managed and manager-managed LLCs differently. In many jurisdictions, members who hold a significant equity interest (such as 25% or more) and actively manage the company can file for an exemption. Passive investors who do not perform labor on-site are frequently exempt by default, as they do not face workplace injury risks in the same capacity as active operators.
Corporations and Executive Officers
Corporate structures traditionally offer the clearest path to officer exemptions, provided specific ownership thresholds are met. Most states require that an exempt officer also be a member of the board of directors and hold a minimum percentage of corporate stock. This prevents businesses from falsely labeling low-level workers as "vice presidents" merely to bypass insurance premiums. Non-executive employees holding nominal titles remain fully eligible for, and legally entitled to, workers' compensation coverage.
The Application and Verification Process
Securing a valid workers' compensation exemption is an administrative process that requires precision. It cannot be achieved simply by telling an insurance broker or writing a note on a policy renewal form; it requires formal engagement with the state regulatory agency responsible for workers' compensation.
- Verify State Eligibility: Review the current statutes of the state where the business operates to confirm that your specific business structure and ownership percentage meet the statutory thresholds for an exemption.
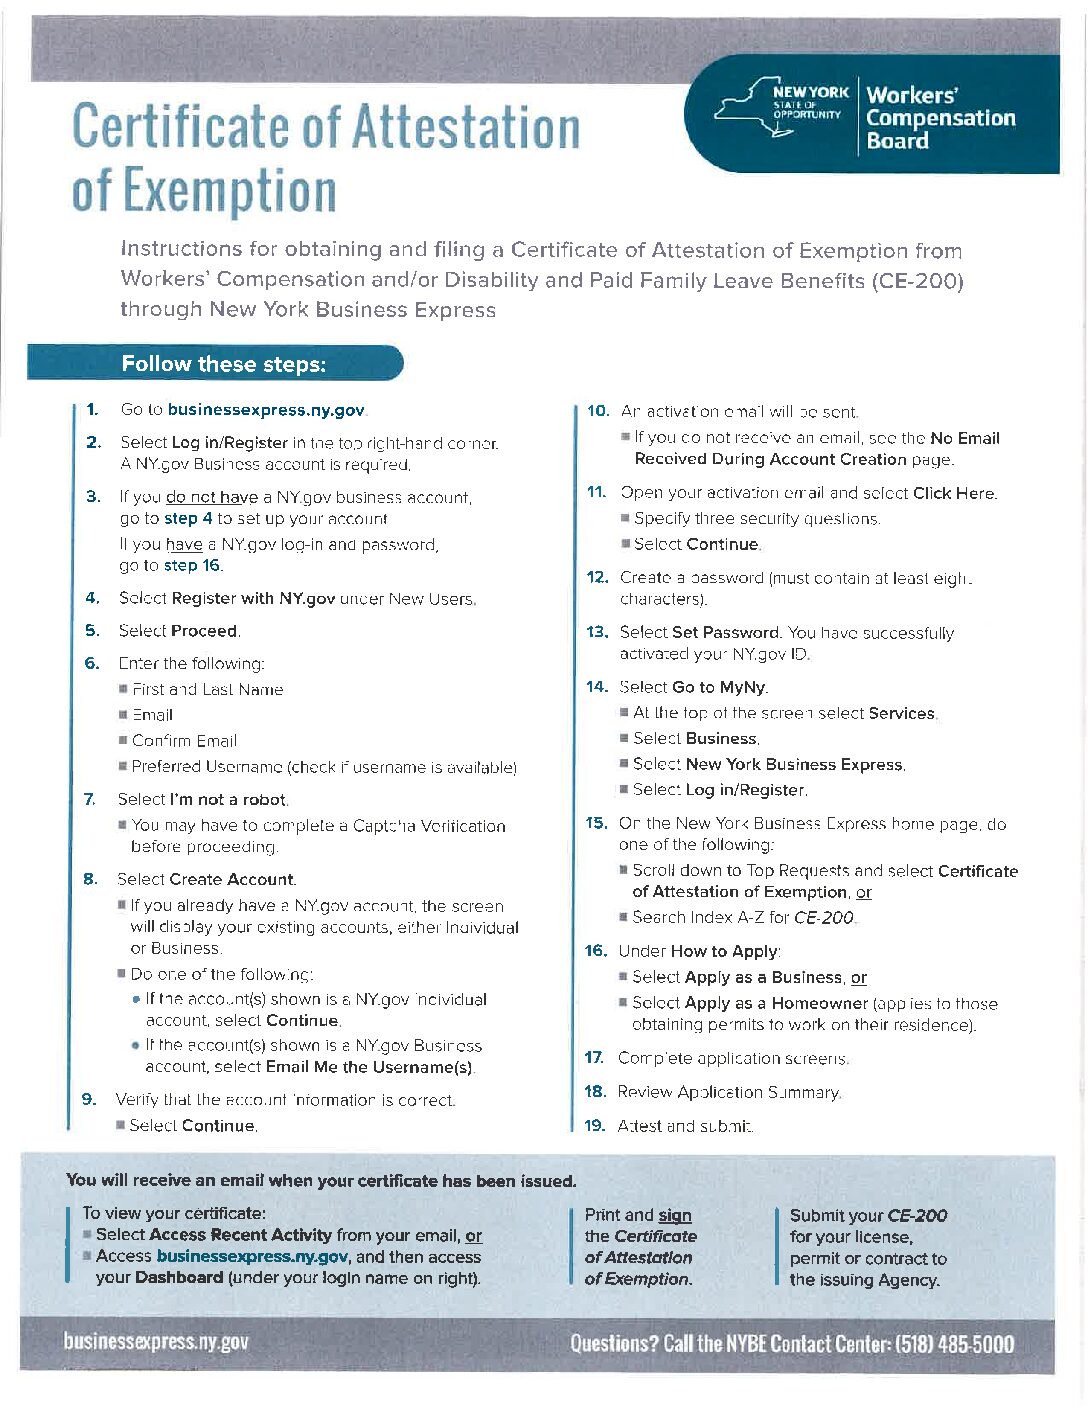
- Obtain the Correct Forms: Download the official application or election form from the state's department of labor or workers' compensation board website. Avoid third-party forms that may be outdated.
- Complete and Notarize: Fill out the documentation completely, detailing the names of the officers, members, or proprietors seeking the exemption, along with their respective ownership percentages and federal employer identification numbers (FEIN). Many states require signatures to be witnessed and notarized.
- Submit and Pay Fees: File the application with the appropriate state agency, enclosing any required administrative processing fees. Processing times can range from a few business days to several weeks.
- Receive the Exemption Certificate: Upon approval, the state issues a formal certificate or waiver. Keep this document accessible, as general contractors, project owners, and insurance auditors will frequently request proof of exemption before allowing work to commence.
Operational Impacts and Risk Management
Opting out of workers' compensation coverage alters the financial and legal risk profile of a business. While the immediate benefit is a reduction in overhead—insurance premiums can represent a significant percentage of payroll expenses—the long-term exposure requires careful evaluation.
When an owner or corporate officer holds a valid exemption, they forfeit their right to receive medical benefits and wage replacement through the workers' compensation system if they suffer an injury while performing job duties. If an injury occurs, the individual must rely on private health insurance, personal disability policies, or out-of-pocket funds. Furthermore, because private health insurers often exclude coverage for injuries sustained during the course of employment or commercial labor, an untreated workplace injury can lead to severe financial strain.
Additionally, businesses must consider how an exemption affects commercial relationships. General contractors hiring subcontractors routinely require proof of workers' compensation insurance or a valid state-issued exemption certificate to protect themselves from "upstream" liability. If a subcontractor's exempt owner is injured on a job site without proper documentation, the general contractor's insurance policy—or the project owner—may legally absorb the liability, leading to cancelled contracts, disputes, and litigation.
Common Mistakes and Compliance Pitfalls
Navigating workers' compensation exemptions involves several regulatory traps that can invalidate an exemption and result in retroactive premium assessments, fines, or stop-work orders.
- Assuming Automatic Exemption: A common error is assuming that registering as an LLC or corporation automatically exempts the owners from insurance mandates. In many states, affirmative paperwork and state approval are mandatory before an exemption takes legal effect.
- Failing to Update Waivers After Ownership Changes: Exemption certificates are tied to specific individuals and ownership percentages. If ownership shifts, shares are sold, or new members join, the existing exemption may become void, requiring a new filing.
- Ignoring Employee Thresholds: Business owners sometimes believe that if the owners are exempt, the business has no reporting obligations. However, the moment an external W-2 employee is hired, the exemption status for owners does not eliminate the duty to secure a standard policy for that employee.
- Misclassifying Workers: Attempting to treat regular employees as "independent contractors" or "corporate officers" to claim exemptions constitutes workers' compensation fraud. State auditors routinely review payroll records to verify that individuals claiming exemptions genuinely exercise executive control and equity ownership.
Frequently Asked Questions
Can an employee apply for a workers' compensation exemption?
No. Workers' compensation exemptions are strictly reserved for business owners, corporate officers, LLC members, partners, and qualifying independent contractors who meet specific statutory ownership or operational criteria. Standard W-2 employees cannot opt out of coverage, as mandatory insurance laws are designed specifically to protect them.
What happens if I work without a required workers' compensation policy or valid exemption?
Operating without required coverage or an approved exemption is illegal in most jurisdictions. Consequences include severe daily financial fines, stop-work orders that halt all business operations, potential criminal misdemeanor or felony charges for willful non-compliance, and complete personal liability for any workplace injuries sustained on the job.
Do independent contractors always need a workers' compensation exemption?
Not necessarily. Whether an independent contractor needs an exemption depends on state law and whether they hire helpers. In many states, true independent contractors are considered separate business entities and are not counted as employees of the hiring party. However, many project owners and general contractors demand a state-issued independent contractor exemption certificate to verify that the worker is legally operating outside the contractor's insurance umbrella.
Does a workers' compensation exemption expire?
In many states, exemption certificates have a defined validity period—such as one, two, or five years—or remain valid only as long as the underlying business structure and ownership percentages remain unchanged. Business owners must monitor expiration dates and renewal requirements to maintain continuous compliance.
Can out-of-state businesses use an exemption across state lines?
Generally, no. Workers' compensation laws are state-specific. An exemption granted in one state does not automatically transfer or confer legal compliance in another state. If a business performs work in a new jurisdiction, it must evaluate and comply with that state's specific exemption and insurance mandates.
Conclusion and Next Actions
Claiming a workers' compensation exemption provides a viable pathway for business owners and corporate officers to reduce operational costs by opting out of self-insurance. However, this administrative choice demands meticulous attention to detail. Business owners must verify their state's exact statutory requirements, complete the formal application process, and maintain accurate records of their exemption certificates. To ensure full compliance and protect your enterprise from unexpected liabilities, consult with a licensed insurance professional or a qualified employment attorney in your operating jurisdiction before altering your coverage status.