Your property assessed value is the specific dollar amount assigned to your real estate by a local government assessor to determine the appropriate amount of property tax you owe. Unlike market value, which fluctuates with buyer demand, the assessed value is a statutory figure calculated using local assessment ratios and official valuation cycles.
Property ownership involves various financial metrics, but none impact your annual carrying costs as directly as the assessed value. Whether you are a first-time homeowner in 2026 or a long-term investor, understanding how this number is derived, where to find it, and how it differs from other valuation types is essential for effective financial planning. Because property taxes fund essential local services like schools, infrastructure, and public safety, the accuracy of your assessment ensures you are paying your fair share—and not a penny more.
The Core Definition: Assessed Value vs. Market Value
To understand your property's assessed value, you must first distinguish it from other types of real estate valuation. Many homeowners mistakenly believe that their tax assessment is what they could receive if they sold their home today. While they are related, they serve entirely different functions.
Market Value
Market value is the estimated price at which your property would sell on the open market between a willing buyer and a willing seller. This figure is highly volatile, influenced by current interest rates, local inventory, neighborhood desirability, and even the time of year. In 2026, market values continue to be driven by data-driven platforms and real-time economic shifts.
Appraised Value
Appraised value is a professional opinion of value usually required by a mortgage lender. A licensed appraiser visits the property, compares it to recent sales of similar homes (comparables), and provides a report to ensure the property is sufficient collateral for a loan.
Assessed Value
The assessed value is the value used by your municipality for tax purposes. It is often a percentage of the market value, known as an "assessment ratio" or "level of assessment." For example, if your home’s market value is $500,000 and your local jurisdiction has a 20% assessment ratio, your assessed value would be $100,000. It is this lower figure to which the local tax rate (often called a millage rate) is applied.
How to Locate Your Property Assessed Value in 2026
Finding your assessed value is a matter of accessing public records. Since property assessments are a matter of public interest, this data is generally transparent and easily accessible through several channels.
1. Your Annual Property Tax Bill
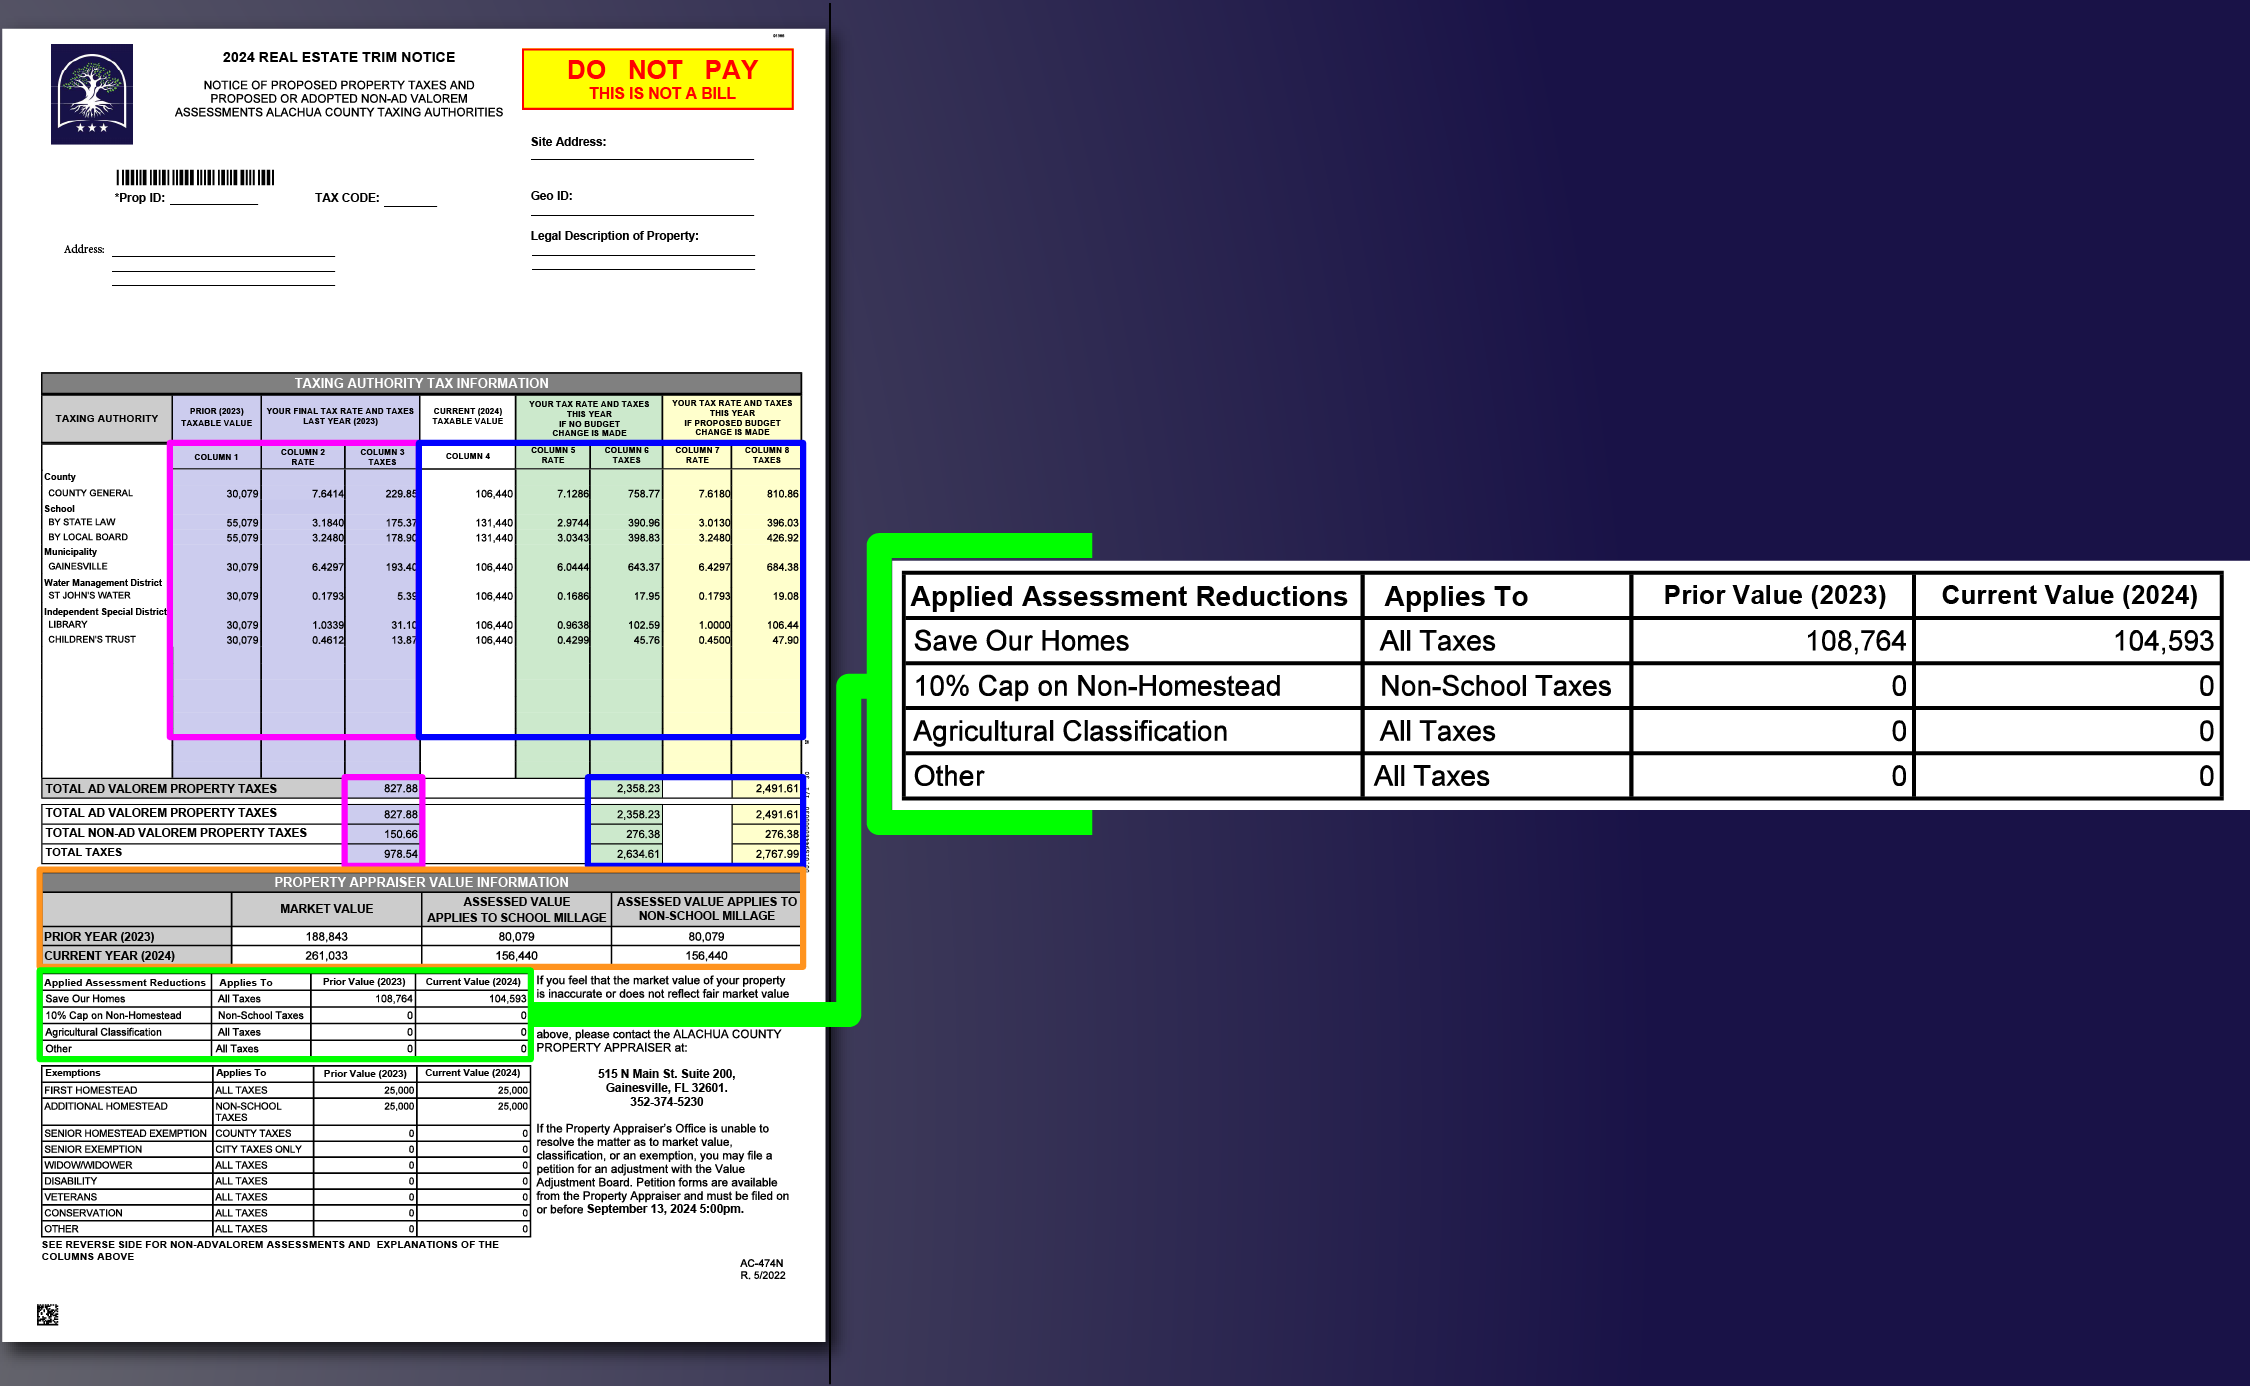
The most direct way to find your assessed value is to look at your most recent property tax statement. Most jurisdictions issue these annually or semi-annually. The bill will typically itemize the "Land Value" and the "Improvement Value" (the structures on the land). The sum of these two is your total assessed value.
2. Local County or Municipal Assessor’s Website
By 2026, nearly every county in the United States and similar jurisdictions globally have modernized their digital infrastructure. You can visit the official website of your County Assessor or Property Appraiser. Most sites offer a "Property Search" or "GIS Map" tool where you can enter your address or Parcel Identification Number (PIN) to view the current and historical assessed values.
3. The Local Tax Office
If you prefer an offline method, you can visit or call the local tax collector or assessor’s office. They are required to provide this information to the property owner. You can also request a copy of your "property record card," which contains the specific data points the assessor used to reach your valuation, such as square footage, number of bedrooms, and recent renovations.
4. Real Estate Documentation
When you purchase a home, the assessed value is listed in the closing documents and often recorded on the deed or the transfer tax declaration. However, keep in mind that these figures may change during the next assessment cycle following a sale.
The Mechanics of the Assessment Process
How does an assessor arrive at a number without visiting every single house every year? They use a process known as mass appraisal. This is a systematic method of valuing a large group of properties as of a given date using standard procedures and statistical testing.
Data Collection and Maintenance
Assessors maintain a database of property characteristics. This includes:
- Physical Characteristics: Acreage, square footage, age of the structure, construction materials, and the number of bathrooms.
- Legal Data: Zoning laws, easements, and deed restrictions.
- Market Data: Sales prices of homes in your specific neighborhood over the last one to three years.
Valuation Models
In 2026, sophisticated Geographic Information Systems (GIS) and Automated Valuation Models (AVMs) are the standard. These tools allow assessors to apply "market adjustments" to entire neighborhoods simultaneously. If sales in a specific area rose by 5% over the year, the model might adjust the assessed values of all similar homes in that area by a corresponding percentage.
Assessment Ratios
As mentioned earlier, the "Assessed Value" is rarely 100% of the "Fair Market Value." Each state or province sets its own rules.
- Uniformity: Laws usually require that similar properties be assessed at the same ratio to ensure fairness.
- Cycles: Some jurisdictions reassess every year, while others may only do so every three or four years. In a "revaluation year," you might see a significant jump in your assessed value if the market has been climbing since the last cycle.
Factors That Influence Your Assessed Value
Several variables can cause your assessed value to rise or fall, some of which are within your control and some that are not.
Property Improvements
Adding a deck, finishing a basement, or installing a swimming pool typically triggers a reassessment. When you pull a building permit for these projects, the local building department notifies the assessor’s office. The added value of these "improvements" will be reflected in your next tax bill.
Economic and Neighborhood Trends
The value of your land is heavily influenced by what is happening around it. The construction of a new school, a popular park, or a major employment hub nearby can increase the market value of your area, leading to a higher assessment. Conversely, the closure of a major factory or an increase in local crime rates can lead to a decrease in value.
Depreciation and Obsolescence
Over time, buildings wear out. Assessors apply depreciation schedules to the "improvement" portion of your value. Furthermore, "functional obsolescence"—such as a four-bedroom house with only one bathroom—can lower the assessed value because the home's layout is no longer desirable by modern standards.
How Your Assessed Value Determines Your Tax Bill
It is a common misconception that if your assessed value doubles, your taxes will double. This is not necessarily true. Your tax bill is the result of a formula involving two main variables: your assessed value and the millage rate.
The Formula
The calculation generally looks like this: [(Assessed Value - Exemptions) x Millage Rate] / 1,000 = Total Property Tax
Understanding the Millage Rate
A "mill" represents one-tenth of a cent, or $1 of tax for every $1,000 of assessed value. Local taxing authorities (school boards, city councils, county commissions) determine the millage rate based on their annual budget requirements. If the total assessed value of all property in a city goes up significantly, the city council may choose to "roll back" the millage rate so that they only collect the revenue they need, preventing a massive tax hike for residents.
The Role of Exemptions
Before the tax rate is applied, certain amounts can be subtracted from your assessed value. These are known as exemptions. Common examples include:
- Homestead Exemption: For owners who use the property as their primary residence.
- Senior Citizen Exemption: For residents over a certain age (often 65+).
- Veteran/Disabled Veteran Exemption: For those who served in the military.
- Agricultural/Greenbelt: For land used for farming or conservation.
Comparing Valuation Types
To help visualize the differences between the values associated with your property, refer to the table below.
| Value Type | Purpose | Determining Party | Frequency of Change |
|---|---|---|---|
| Market Value | Buying or selling a home | The open market (buyers/sellers) | Daily/Constant |
| Appraised Value | Securing a mortgage or loan | Licensed Professional Appraiser | At the time of transaction |
| Assessed Value | Calculating property taxes | Government Tax Assessor | Annual or Periodic (per local law) |
| Replacement Cost | Insurance coverage limits | Insurance Underwriter | Annual (based on construction costs) |
Challenging an Inaccurate Assessed Value
What happens if you believe your assessed value is too high? Unlike your mortgage or your market value, your assessed value can be formally appealed.
Grounds for Appeal
You cannot appeal your taxes simply because you think they are "too high." You must prove that the assessed value is incorrect. Valid reasons for appeal include:
- Data Errors: The assessor’s records show four bedrooms when you only have three, or they have the wrong square footage.
- Unequal Appraisal: Your home is assessed at a significantly higher value than identical homes in your immediate neighborhood.
- Market Overvaluation: The assessor claims your home is worth $600,000, but recent sales of identical homes prove it is only worth $500,000.
The Appeal Process
The window for appealing is usually very short—often only 30 to 60 days after you receive your annual assessment notice.
- Step 1: Informal Review. Speak with someone at the assessor's office. Many errors can be fixed without a formal hearing.
- Step 2: Formal Appeal. File a petition with the local Board of Equalization or Board of Review.
- Step 3: Evidence Submission. Provide photos, a recent independent appraisal, or a list of comparable sales (comps) to support your claim.
- Step 4: The Hearing. Present your case to the board. If they agree, they will adjust your assessed value, which will lower your future tax bills.
Frequently Asked Questions
Does a higher assessed value mean I can sell my house for more?
Not necessarily. While a high assessment suggests the property has significant value, savvy buyers and real estate agents look at "market comps" and professional appraisals rather than tax records. In fact, a very high assessed value can sometimes deter buyers because it implies higher annual property tax costs.
If I renovate my kitchen, will my assessed value go up immediately?
In most cases, the change will not occur until the next assessment cycle. However, because renovations usually require a building permit, the assessor's office will eventually be notified. In 2026, many jurisdictions use permit-tracking software that automatically flags properties for a "spot reassessment" once the work is finalized.
Why is my assessed value much lower than my neighbor's identical house?
This is often due to "tax caps" or "assessment limits." Many regions have laws that prevent the assessed value of a primary residence from rising by more than a small percentage (e.g., 3% per year) as long as the same person owns it. If your neighbor recently bought their house, their assessment may have "reset" to the current market value, while yours remains protected by your years of ownership.
Will my property assessed value go down if the market crashes?
Eventually, yes. However, because assessment cycles often lag behind the real-time market by a year or more, you might see your assessed value remain high even after market prices have started to dip. This is a common time for homeowners to file assessment appeals.
Can I find the assessed value of a property I don't own?
Yes. Property assessments are public records. You can use the local assessor’s online portal to look up the assessed value of any property in the jurisdiction, which is a useful tool for potential buyers to estimate what their future tax burden might be.
Practical Recommendations for Homeowners
To manage your property taxes effectively in 2026, you should take a proactive approach to your assessed value. First, audit your property record card at least once every three years. Ensure the square footage, room counts, and lot size are accurate. Small errors can lead to hundreds of dollars in overpayment every year.
Second, if you are planning a major renovation, factor the "tax hit" into your budget. Contact the assessor's office beforehand to ask how they value specific improvements, such as an ADU (Accessory Dwelling Unit) or a finished basement. This prevents financial surprises once the project is complete.
Finally, stay aware of the appeal deadlines in your specific county. Mark them on your calendar for the month your assessment notice typically arrives. If the real estate market in your area experiences a downturn, being ready to file an appeal immediately can save you significant money on your annual carrying costs.