Navigating Medicare in New Jersey involves understanding federal health insurance guidelines alongside state-specific resources like the New Jersey Department of Human Services, Medicaid programs, and local counseling initiatives. Beneficiaries must evaluate Original Medicare, Medicare Advantage, supplemental Medigap policies, and prescription drug plans while coordinating with state assistance programs to optimize healthcare coverage and out-of-pocket costs.
Understanding the Foundation: Original Medicare in New Jersey
Medicare is a federal health insurance program primarily serving individuals aged 65 and older, as well as younger individuals with qualifying disabilities or end-stage renal disease (ESRD). For residents of New Jersey, the foundation of the program is Original Medicare, which is managed directly by the federal Centers for Medicare & Medicaid Services (CMS). Original Medicare is split into two primary parts: Part A and Part B.
Part A: Hospital Insurance
Medicare Part A covers inpatient hospital stays, care in a skilled nursing facility, hospice care, and some home health care. For most New Jersey residents who have worked and paid Medicare taxes for at least 10 years (40 quarters), Part A is premium-free. Those who do not meet this work history requirement may purchase Part A by paying a monthly premium. Part A comes with specific cost-sharing structures, including a deductible for each benefit period, after which coinsurance applies for extended hospital stays or prolonged care in a skilled nursing facility.
Part B: Medical Insurance
Medicare Part B covers medically necessary services and preventive care, such as doctor visits, outpatient care, clinical laboratory services, durable medical equipment, and mental health services. Unlike Part A, all beneficiaries pay a standard monthly premium for Part B, which can be higher for individuals with higher modified adjusted gross incomes, a threshold determined by the Social Security Administration based on tax returns from two years prior. Part B also features an annual deductible and an 80/20 coinsurance arrangement for most covered medical services, meaning Medicare covers 80% of the approved amount while the beneficiary pays the remaining 20%.
Expanding Coverage: Medicare Advantage vs. Medigap in New Jersey
While Original Medicare provides robust protection, it does not cover all medical expenses. Beneficiaries must decide whether to fill the gaps in Original Medicare by purchasing a standalone Medigap policy alongside a Part D prescription drug plan, or by enrolling in a private Medicare Advantage plan.
Medicare Advantage (Part C)
Medicare Advantage plans are offered by private insurance companies approved by Medicare. In New Jersey, options vary significantly by county, with urban areas like Essex and Hudson counties offering a vast array of carrier choices, while rural areas may have more limited selections. These plans bundle Part A, Part B, and usually Part D (prescription drug coverage) into a single plan.
Many Medicare Advantage plans in New Jersey also offer extra benefits not covered by Original Medicare, such as routine dental, vision, hearing care, and wellness program memberships. However, beneficiaries must generally use the plan's network of doctors and hospitals, and prior authorization may be required for certain specialized procedures or equipment. Out-of-pocket maximums protect enrollees from catastrophic healthcare costs, a feature absent in standard Original Medicare.
Medicare Supplement Insurance (Medigap)
Alternatively, New Jersey residents can choose to stick with Original Medicare and purchase a Medicare Supplement Insurance (Medigap) policy. Regulated by the New Jersey Department of Banking and Insurance (DOBI), Medigap policies are sold by private insurers to help pay for costs that Original Medicare does not cover, such as copayments, coinsurance, and deductibles.
New Jersey has unique state-specific consumer protection laws regarding Medigap open enrollment. While federal rules provide a one-time open enrollment window when an individual first turns 65 and enrolls in Part B, New Jersey law grants an annual open enrollment period that allows beneficiaries to switch to a Medigap plan with equal or lesser benefits without medical underwriting, protecting those with pre-existing conditions.
Prescription Drug Coverage: Medicare Part D in New Jersey
Prescription drug coverage is a critical component of healthcare planning for New Jersey seniors. Medicare Part D plans are standalone insurance policies purchased from private companies approved by Medicare to help cover the cost of outpatient prescription medications.
Every Part D plan has a formulary, which is a list of covered drugs categorized into different "tiers." Medications in lower tiers generally cost less than those in higher tiers. New Jersey residents must carefully review plan formularies during the annual open enrollment period, as drug lists and pharmacy networks frequently change from year to year.
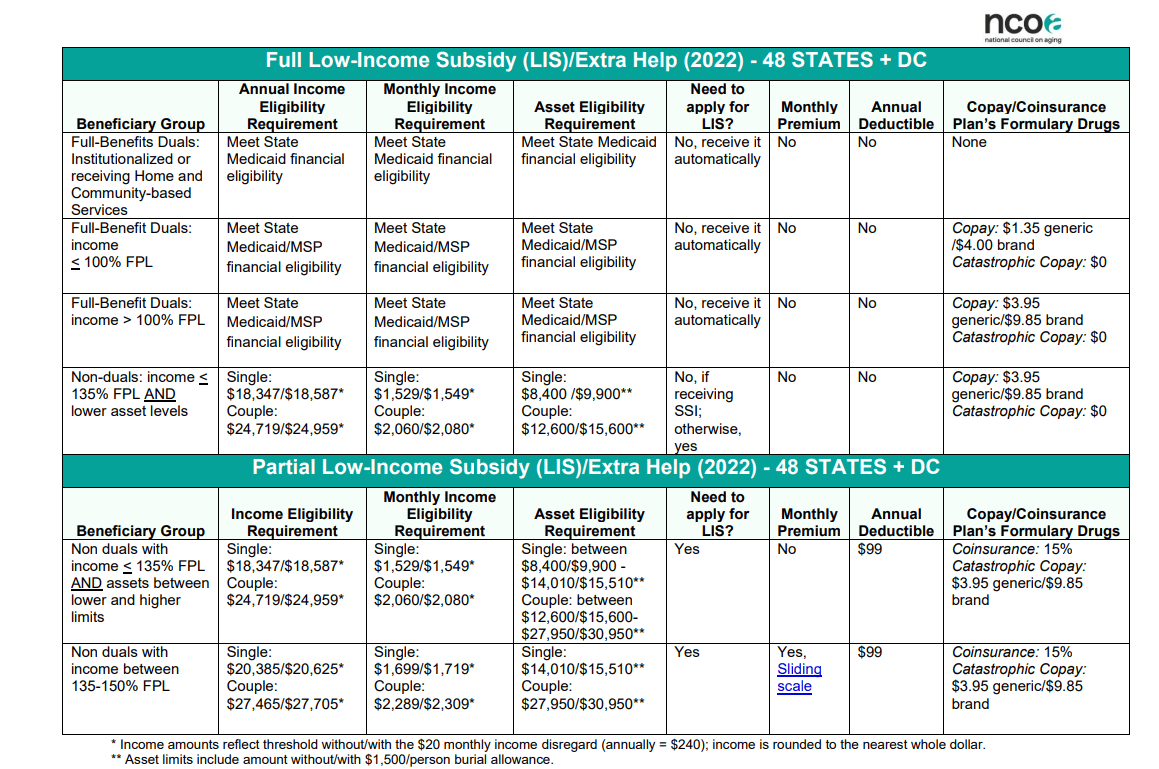
To offset prescription costs, qualifying low-income residents in New Jersey can apply for Extra Help, a federal low-income subsidy program that reduces or eliminates monthly premiums, annual deductibles, and copayments associated with Part D.
Financial Assistance and State Programs for New Jersey Beneficiaries
Healthcare costs can strain fixed incomes. Fortunately, New Jersey provides several state-administered programs designed to assist low-income Medicare beneficiaries with premiums, deductibles, and cost-sharing obligations.
Medicare Savings Programs (MSPs)
New Jersey administers several Medicare Savings Programs through the state's Medicaid agency (NJ FamilyCare). These programs assist qualified individuals with paying Medicare Part B premiums and, in some cases, Medicare Part A and Part B deductibles and coinsurance:
- Qualified Medicare Beneficiary (QMB): Helps pay for Part A and Part B premiums, deductibles, coinsurance, and copayments.
- Specified Low-Income Medicare Beneficiary (SLMB): Helps pay for the Medicare Part B monthly premium.
- Qualifying Individual (QI): Also helps pay for the Part B premium, subject to limited state funding allocated on a first-come, first-served basis.
PAAD and Senior Gold Prescription Discount Program
Unique to New Jersey, the Pharmaceutical Assistance to the Aged and Disabled (PAAD) program and the Senior Gold Prescription Discount Program provide state-funded relief for prescription drug costs.
- PAAD is a state-funded program that helps eligible older adults and individuals with disabilities pay for prescription drugs and insulin. To qualify, residents must meet specific age and income guidelines. PAAD functions alongside Medicare Part D, often covering out-of-pocket costs during coverage gaps.
- Senior Gold serves as a secondary prescription safety net for New Jersey residents whose incomes exceed the PAAD limits but fall below a higher state-established threshold. Enrollees pay a flat copayment plus a monthly premium to receive significant discounts on covered medications.
| Program Name | Primary Financial Benefit | General Eligibility Focus |
|---|---|---|
| Medicare Savings Programs (MSPs) | Pays Part B premiums, deductibles, and coinsurance. | Low-income individuals meeting strict asset and income limits. |
| PAAD (New Jersey) | Reduces prescription drug and insulin costs. | New Jersey residents aged 65+ or disabled meeting state income caps. |
| Senior Gold (New Jersey) | Provides prescription discounts above PAAD income limits. | Moderate-income New Jersey residents aged 65+ or disabled. |
| Extra Help (Federal) | Lowers Part D drug plan costs, premiums, and copayments. | Beneficiaries with limited resources and financial assets. |
Enrollment Periods and Critical Deadlines
Understanding when and how to enroll in Medicare is vital to avoiding late-enrollment penalties and coverage gaps. New Jersey residents must navigate several distinct enrollment windows.
Initial Enrollment Period (IEP)
The Initial Enrollment Period is a seven-month window that begins three months before the month an individual turns 65, includes the birth month, and extends for three months following the birth month. For individuals qualifying due to a disability, the IEP is tied to the 25th month of receiving Social Security Disability Insurance (SSDI) benefits.
Annual Election Period (AEP)
Running from October 15 through December 7 each year, the Annual Election Period allows existing Medicare beneficiaries to make changes to their coverage. During this time, New Jersey residents can switch from Original Medicare to a Medicare Advantage plan (or vice versa), change from one Medicare Advantage plan to another, or enroll in, switch, or drop a Medicare Part D prescription drug plan. Changes take effect on January 1 of the following year.
Medicare Advantage Open Enrollment Period (MAOEP)
From January 1 through March 31 annually, individuals enrolled in a Medicare Advantage plan can switch to a different Medicare Advantage plan or disenroll from Medicare Advantage and return to Original Medicare, while also picking up a standalone Part D plan.
Navigating Local Assistance: The SHIP Program
Navigating the complexities of Medicare, Medigap, and state-specific programs can be challenging. To assist residents, the New Jersey Department of Human Services oversees the State Health Insurance Assistance Program (SHIP).
SHIP provides free, objective, and confidential counseling and assistance to Medicare beneficiaries, their families, and caregivers. SHIP counselors do not sell insurance or promote specific commercial products; instead, they help residents understand their rights, compare plan options, evaluate billing issues, and apply for cost-saving programs like MSPs and PAAD. Local SHIP counseling sites are located in every county across New Jersey, often operating out of county offices on aging or senior centers.
Frequently Asked Questions
When am I first eligible to sign up for Medicare in New Jersey?
Most individuals become eligible during their Initial Enrollment Period, which begins three months before the month they turn 65, includes their birth month, and ends three months afterward. Enrolling during this window prevents potential permanent late-enrollment penalties for Part B and Part D.
Can I have both Medicare and NJ FamilyCare (Medicaid)?
Yes. Individuals who qualify for both Medicare and NJ FamilyCare are known as "dual-eligibles." In New Jersey, these beneficiaries receive coordinated care and financial assistance, with Medicaid covering many out-of-pocket expenses such as Medicare premiums, deductibles, and copayments.
How do I apply for prescription drug assistance in New Jersey?
New Jersey residents can apply for PAAD, Senior Gold, and Medicare Savings Programs by contacting the New Jersey Department of Human Services or by visiting the official NJ FamilyCare website. Local county SHIP offices can also assist with completing and submitting these applications.
What is the difference between a Medigap policy and a Medicare Advantage plan?
A Medigap policy works alongside Original Medicare, covering out-of-pocket costs like copays and deductibles while allowing you to see any doctor nationwide who accepts Medicare. A Medicare Advantage plan replaces Original Medicare, offering all-in-one coverage through private insurers that typically requires the use of specific provider networks.
Where can I get free, unbiased counseling on New Jersey Medicare options?
You can contact the New Jersey State Health Insurance Assistance Program (SHIP) through the New Jersey Department of Human Services. SHIP provides free, non-commercial counseling to help you navigate plan selections, enrollment deadlines, and appeals.
Next Steps and Action Plan
- Review Current Coverage: Examine your current health needs, prescription medications, and out-of-pocket expenses to determine if your existing plan remains optimal.
- Consult SHIP Counselors: Reach out to your local New Jersey SHIP office for free, personalized counseling tailored to your county and financial situation.
- Verify Deadlines: Mark key calendar dates, such as the Annual Election Period (October 15 – December 7), to ensure timely submission of any plan changes.
- Explore Financial Aid: Check income and asset guidelines for New Jersey's PAAD, Senior Gold, and Medicare Savings Programs to see if you qualify for state-level assistance.