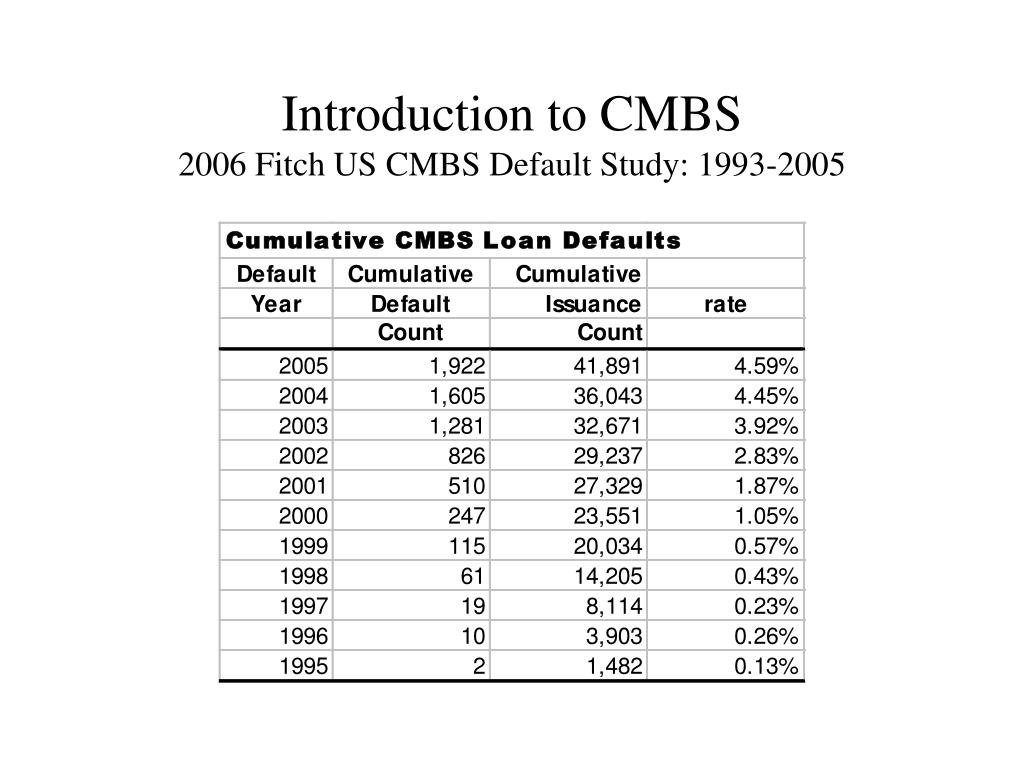
Commercial mortgage-backed securities (CMBS) ratings are independent assessments of the credit risk associated with bonds backed by commercial real estate loans, helping investors gauge the likelihood of timely interest and principal repayment. These letter-grade evaluations are issued by nationally recognized statistical rating organizations (NRSROs) such as Standard & Poor's, Moody's Ratings, Fitch Ratings, and DBRS Morningstar. By analyzing underlying property cash flows, loan structures, and collateral health, these ratings dictate how institutional investors price, trade, and manage risk within the multi-billion-dollar commercial real estate debt market.
The Foundation of Commercial Mortgage-Backed Securities
To understand how credit ratings function within the commercial mortgage-backed securities ecosystem, one must first examine how these financial instruments are constructed. Unlike residential mortgages, which are typically uniform and bundled into conforming pools, commercial mortgages are idiosyncratic, non-recourse loans secured by income-producing real estate such as office buildings, retail centers, multifamily complexes, industrial warehouses, and hotels.
When a financial institution or conduit lender originates these commercial loans, they are often pooled together into a single trust or special purpose vehicle (SPV). This SPV then issues bonds—known as CMBS certificates or tranches—to institutional investors. Because the underlying properties generate varying levels of cash flow and carry distinct risk profiles, the cash flows from the master loan pool are distributed to investors sequentially through a credit-support structure commonly referred to as a waterfall.
The creation of these securities requires rigorous due diligence. Rating agencies evaluate every facet of the transaction, from the legal framework governing the trust to the local economic conditions surrounding each mortgaged property. Without independent credit evaluations, institutional buyers would struggle to price the diverse risk inherent in portfolios containing everything from premier Manhattan skyscrapers to tertiary suburban strip malls.
How Rating Agencies Evaluate CMBS
The credit rating process for commercial mortgage-backed securities is a multi-dimensional assessment that combines quantitative cash flow modeling with qualitative legal and structural analysis. Rating agencies do not merely look at the face value of a loan; they perform stress tests on the underlying real estate collateral to determine how well the properties can withstand economic downturns.
Debt Service Coverage Ratio and Loan-to-Value
Two primary metrics drive quantitative evaluations in CMBS underwriting: the Debt Service Coverage Ratio (DSCR) and the Loan-to-Value (LTV) ratio.
- Net Cash Flow (NCF) and DSCR: Rating agencies calculate their own adjusted NCF for each property, often stripping out landlord-favorable assumptions regarding vacancy rates, operating expenses, and rental escalations. The agency DSCR is derived by dividing this adjusted NCF by the annual debt service obligations. A higher DSCR indicates a greater cushion to absorb rental income drops before a default occurs.
- LTV Calculations: The LTV ratio compares the loan amount to the agency-determined value of the property. Because commercial property values fluctuate based on capitalization rates and market demand, rating agencies apply conservative valuation models, resulting in LTV figures that are frequently higher (more conservative) than those calculated by the original loan originators.
Property Types and Geographic Concentration
The diversity and quality of the underlying real estate collateral heavily influence the final ratings assigned to a CMBS pool. Rating agencies categorize risk by property sector, recognizing that multifamily and industrial assets historically exhibit different default and loss severities compared to urban office buildings or discretionary retail spaces. Furthermore, geographic concentration limits are enforced; if a disproportionate share of the loan pool relies on a single metropolitan statistical area (MSA) or a dominant local employer, the rating agency increases credit enhancement requirements to mitigate regional economic shock.
The Tranche Structure and the Credit Waterfall
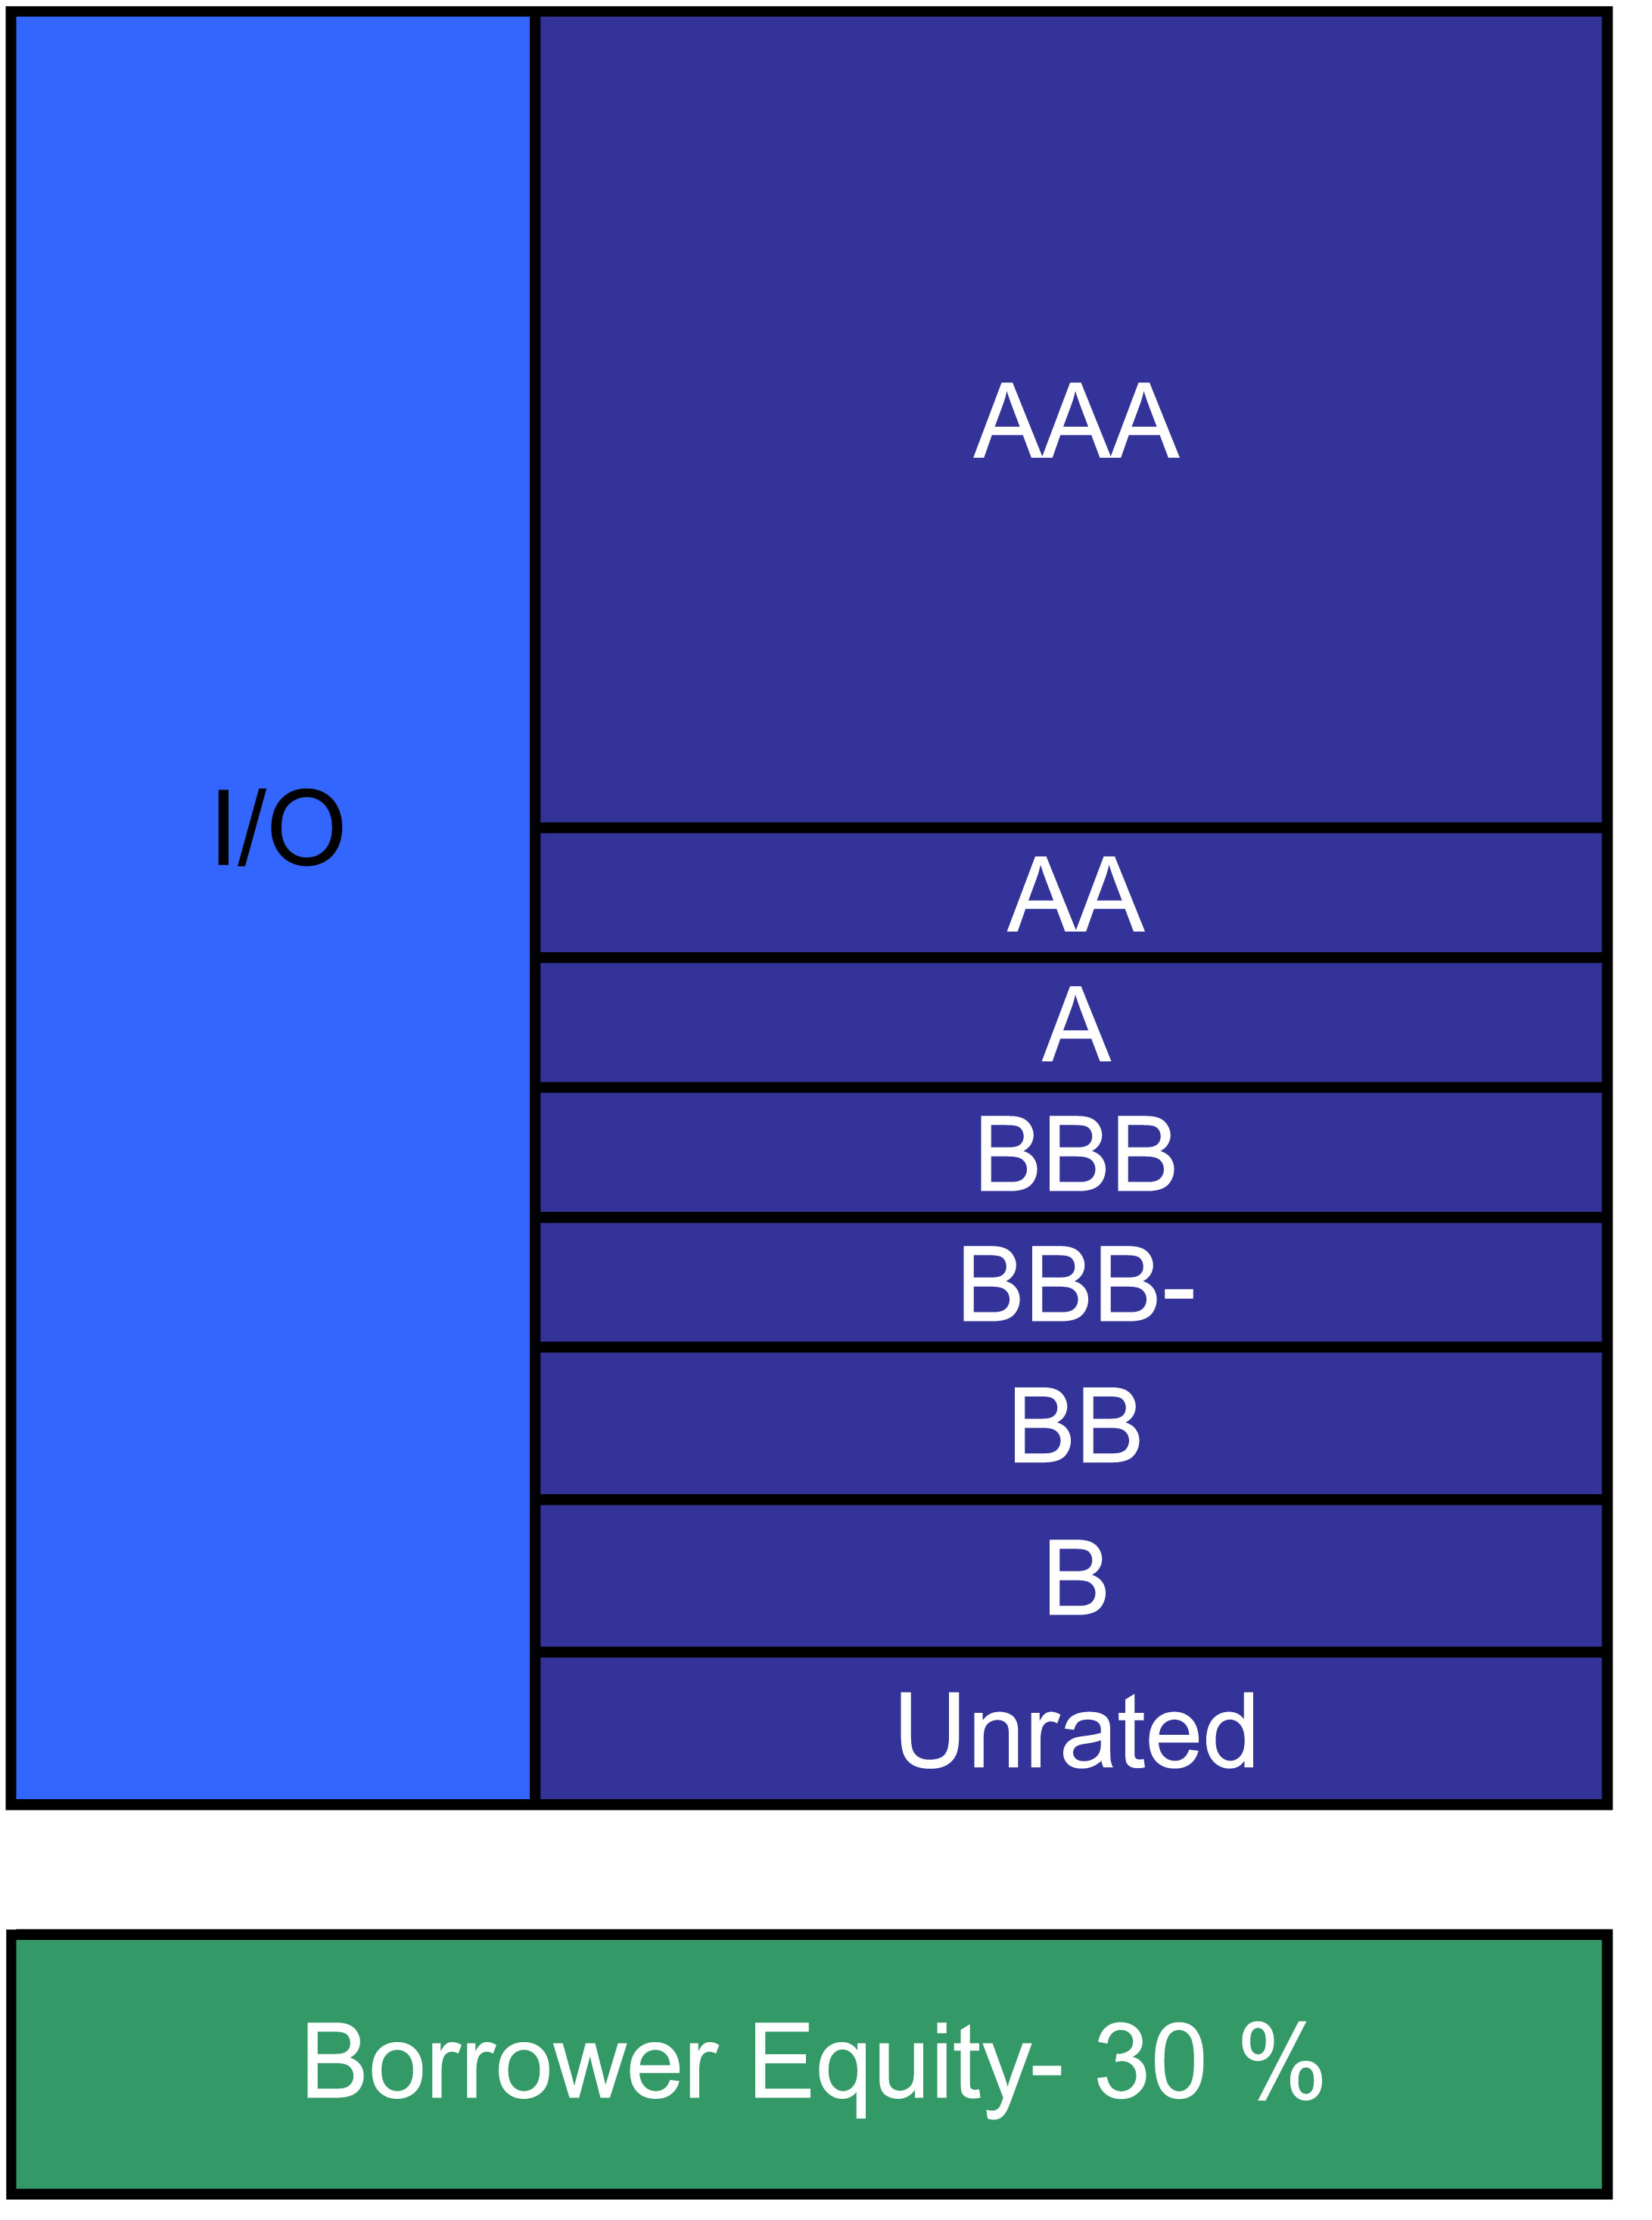
A defining characteristic of traditional conduit CMBS is the sequential pay structure, also known as the subordination or waterfall structure. This design slices the risk pool into distinct tranches, each bearing a specific credit rating ranging from investment-grade (AAA down to BBB-) to non-investment-grade (sub-investment grade or high-yield) and unrated equity pieces (often called the B-piece or first-loss tranche).
- AAA / Investment Grade Tranches (Senior Priority)
- AA, A, BBB / Mezzanine Tranches (Intermediate Priority)
- BB, B / Sub-Investment Grade Tranches (Higher Risk)
- NR / First-Loss / B-Piece Tranche (Equity Risk)
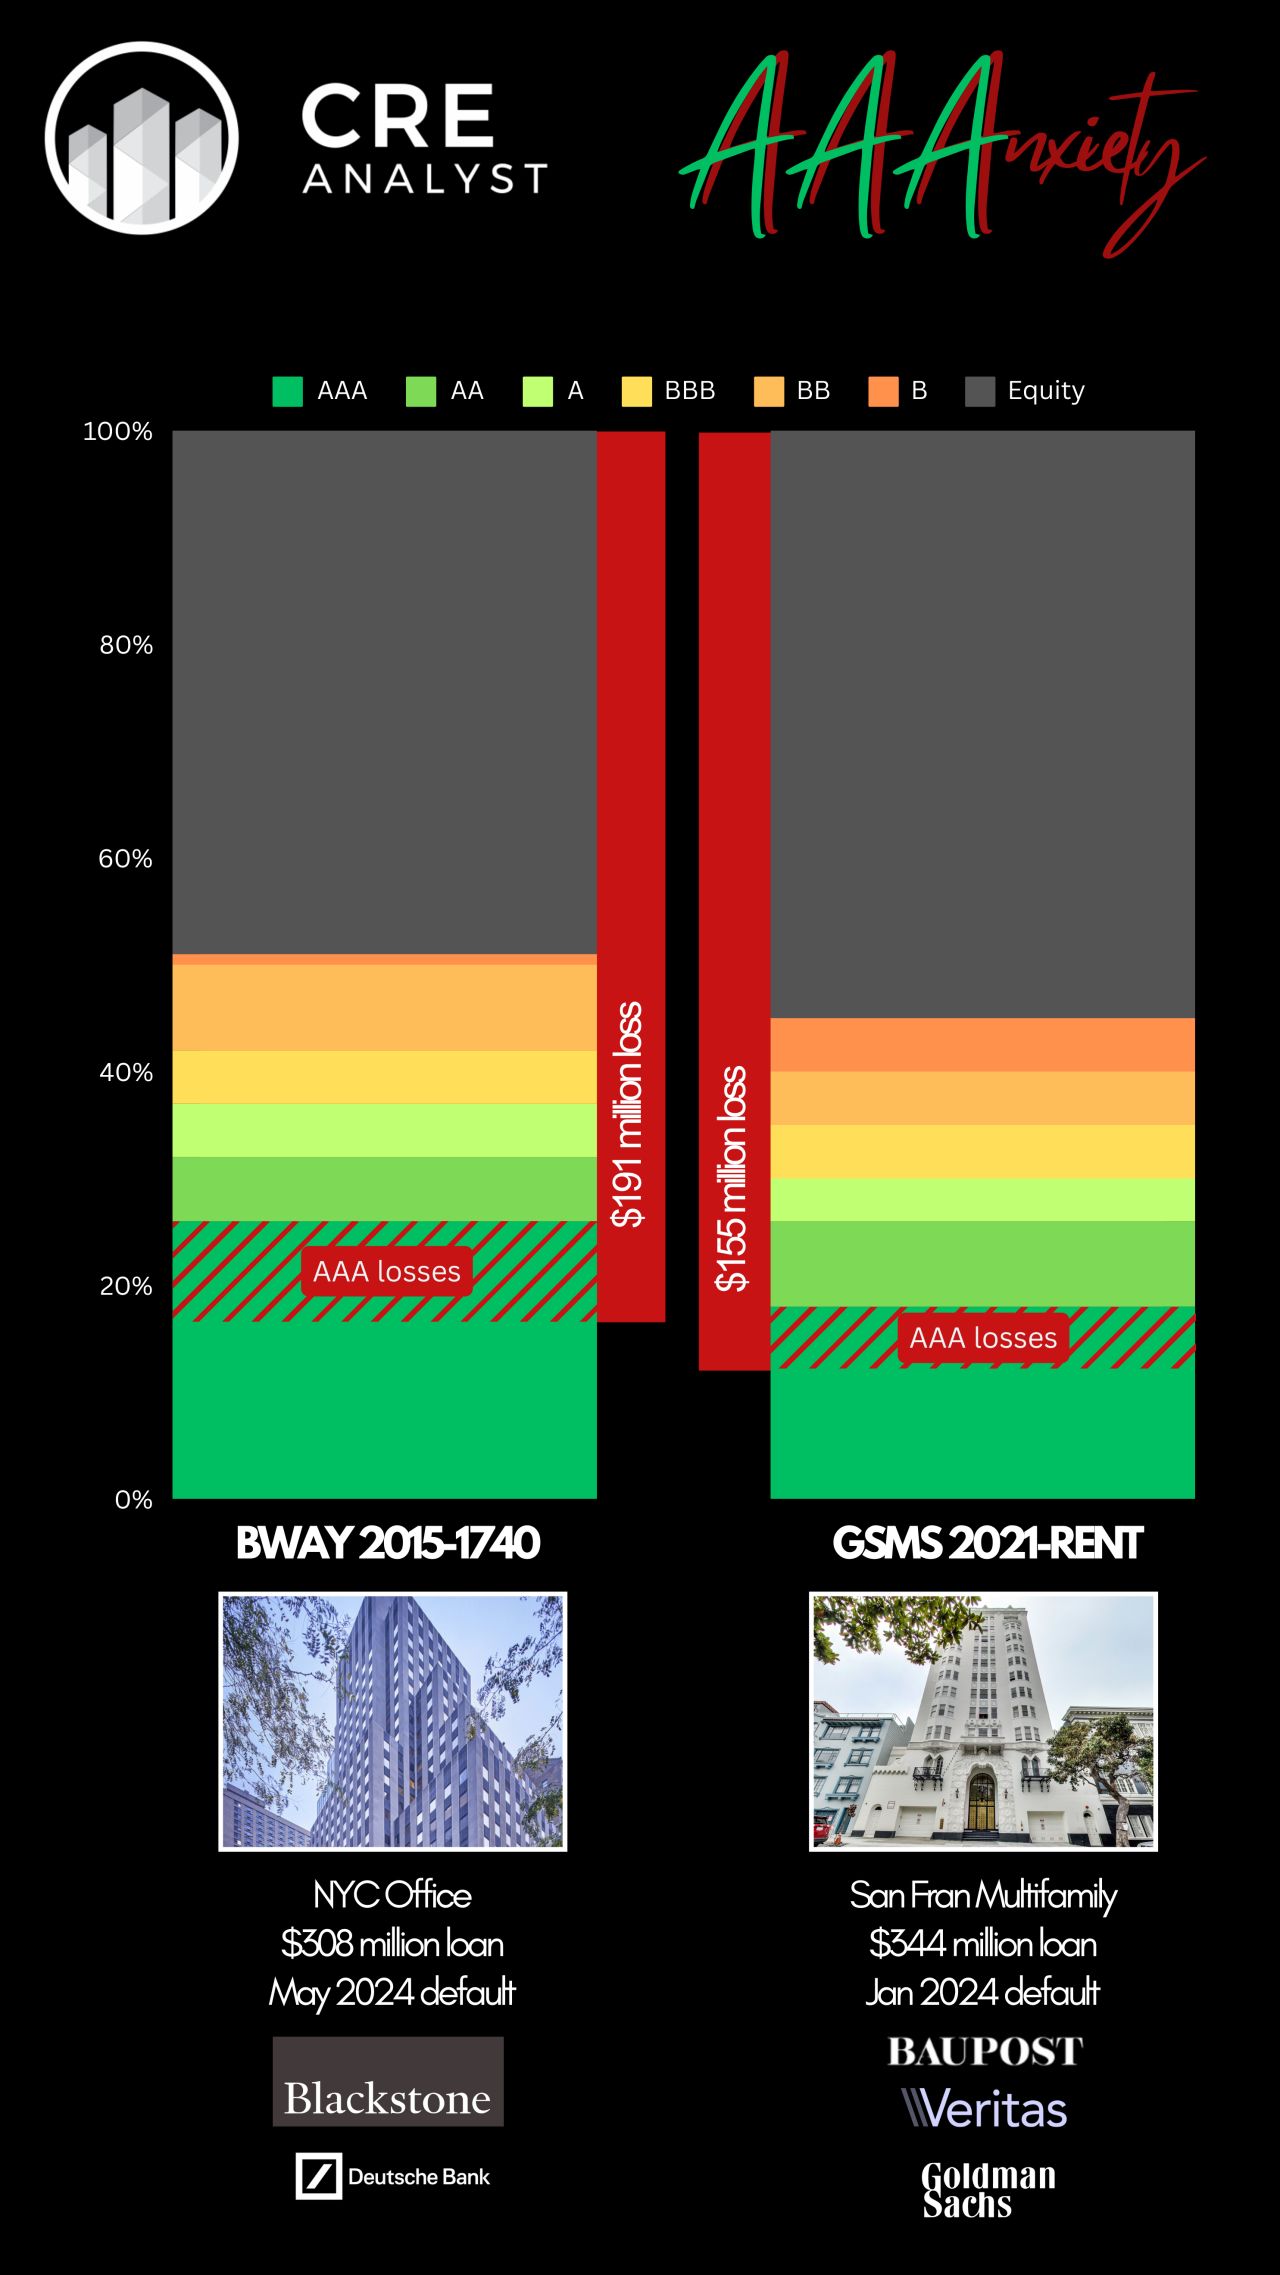
Losses within the commercial mortgage pool are absorbed from the bottom up. If a loan defaults and the liquidation of the underlying property results in a realized loss, that loss is first deducted from the principal balance of the unrated or lowest-rated tranches. Only after the entire principal of those junior tranches is wiped out do losses begin to affect investment-grade bonds, starting with the lowest-rated investment-grade tranche (BBB-) and moving upward toward the AAA securities.
Credit Enhancement Mechanisms
To achieve high investment-grade ratings on senior tranches, transactions rely on several forms of credit enhancement:
- Subordination: The presence of lower-rated and unrated tranches that absorb initial losses.
- Overcollateralization: A situation where the aggregate principal balance of the commercial loans exceeds the total face value of the issued bonds.
- Spread/Excess Interest: The margin between the interest rates paid by borrowers on the underlying loans and the lower coupon rates paid to senior bondholders, which can be used to pay down principal or cover minor losses.
- Reserve Accounts: Escrows established for taxes, insurance, tenant improvements, and leasing commissions.
Comparing CMBS Ratings Across Major Agencies
While different NRSROs maintain their own proprietary quantitative models and qualitative adjustment factors, the long-term credit rating scales exhibit general alignment across the industry. Understanding these distinctions is vital for portfolio managers bound by regulatory investment guidelines or institutional mandates.
| Rating Agency | Highest Investment Grade | Lowest Investment Grade | High-Yield / Speculative | Default / Distressed |
|---|---|---|---|---|
| Standard & Poor's (S&P) | AAA | BBB- | BB+ to D | D |
| Moody's Ratings | Aaa | Baa3 | Ba1 to C | C / D |
| Fitch Ratings | AAA | BBB- | BB+ to D | D |
| DBRS Morningstar | AAA | BBB(low) | BB(high) to D | D |
Note: Ratings of BBB- (S&P/Fitch), Baa3 (Moody's), or BBB(low) (DBRS) and above are generally classified as investment-grade, enabling regulated entities like banks and insurance companies to hold them under statutory capital requirements.
Surveillance and Rating Downgrades
CMBS ratings are not static static judgments rendered at issuance; they are subject to continuous surveillance throughout the life of the transaction, which typically spans 10 years. Rating agencies monitor loan performance reports (such as monthly remittance reports provided by master and special servicers), watchlists, and delinquency trackers.
When a commercial property experiences financial distress—such as the departure of a major anchor tenant, a sharp drop in local market rents, or an inability of the borrower to refinance maturing debt—the rating agency may place the associated bond tranche on "Rating Watch" or downgrade its credit rating.
- Adverse Selection and Maturity Defaults: In environments marked by rising interest rates or structural shifts in real estate demand (such as hybrid work models impacting office valuations), refinancing risk becomes acute. If maturing loans cannot find replacement financing due to tightened lending standards or lower property valuations, special servicers take control, often leading to realized losses and subsequent downgrades of junior and mezzanine tranches.
- Cascade Effects: A downgrade of subordinate tranches can trigger rating agency downgrades higher up the capital structure if cumulative losses threaten to breach the credit enhancement threshold protecting senior classes.
Practical Considerations for Investors
Navigating commercial mortgage-backed securities requires a sophisticated understanding of how credit ratings translate into portfolio strategy and risk management. Investors must look beyond the initial letter grade to evaluate structural protections, asset class concentration, and macroeconomic trends affecting commercial real estate.
- Regulatory Capital and Compliance: Institutional investors such as pension funds, insurance companies, and commercial banks must adhere to strict risk-based capital rules. Holding investment-grade CMBS requires lower capital reserves compared to holding speculative or unrated high-yield tranches.
- Yield Versus Risk Trade-off: Lower-rated tranches (such as single-B or unrated B-pieces) offer significantly higher yields to compensate for the elevated probability of default and loss severity. However, these positions require intensive asset-level surveillance and direct engagement with special servicers during loan restructuring scenarios.
- Diversification and Index Inclusion: Many institutional investors buy CMBS through standardized indices or exchange-traded products, where index inclusion rules dictate minimum credit rating thresholds (e.g., requiring all underlying bonds to maintain investment-grade status from at least two major NRSROs).
Frequently Asked Questions
What happens to a CMBS rating when a major tenant vacates a property?
When a major tenant vacates a property within a loan pool, the property's net cash flow typically drops, potentially lowering the Debt Service Coverage Ratio. Rating agencies review the asset to determine if the loss of income threatens debt service. If the loan is placed on a watchlist or transferred to a special servicer due to impending default, the agencies may downgrade the specific tranches most exposed to that loan's eventual loss severity.
Are all commercial mortgage-backed securities rated by multiple agencies?
Not all CMBS issues utilize every rating agency. While large, public conduit transactions (often referred to as multi-borrower deals) typically secure ratings from at least two major NRSROs to satisfy institutional investor requirements, single-asset, single-borrower (SASB) transactions or smaller private placements may engage only one rating agency depending on the preferences of the issuer and the target investor base.
What is the role of the B-piece buyer in relation to rating agencies?
The B-piece buyer purchases the unrated, first-loss tranche of a CMBS transaction. Because they absorb the first dollar of credit loss, B-piece buyers perform exhaustive, independent underwriting before a deal closes. Rating agencies often take note of the B-piece buyer's risk assessment and negotiation of loan structural modifications during the pooling process, though the agencies maintain independent methodologies for assigning official credit ratings.
How do rising interest rates impact existing CMBS ratings?
Rising interest rates increase borrowing costs for commercial real estate owners seeking to refinance maturing balloon loans. If property cash flows have not grown proportionally to offset higher capitalization rates and borrowing costs, refinancing becomes difficult. This macro environment increases default risk on maturing loans, leading to potential credit rating downgrades across subordinate tranches within seasoned CMBS pools.
Can a CMBS rating be upgraded after issuance?
Yes, CMBS ratings can be upgraded. As the underlying loan pool seasons, borrowers pay down principal through regular amortization, and performing loans successfully mature and pay off in full, the relative credit enhancement protecting remaining senior tranches increases. If the remaining pool represents lower aggregate risk relative to the remaining bond balances, rating agencies may upgrade tranches to reflect their improved credit profiles.
Conclusion and Next Actions
For investors and financial professionals navigating commercial real estate debt markets, CMBS ratings serve as an indispensable baseline for risk assessment. However, relying solely on letter grades without examining underlying property fundamentals, geographic distributions, and loan maturity schedules exposes portfolios to unforeseen market corrections. To make informed allocation decisions, review detailed monthly servicer remittance reports, monitor macroeconomic trends impacting specific property sectors such as office and retail, and consult qualified fixed-income advisors to align your investments with established risk tolerances and regulatory compliance frameworks.