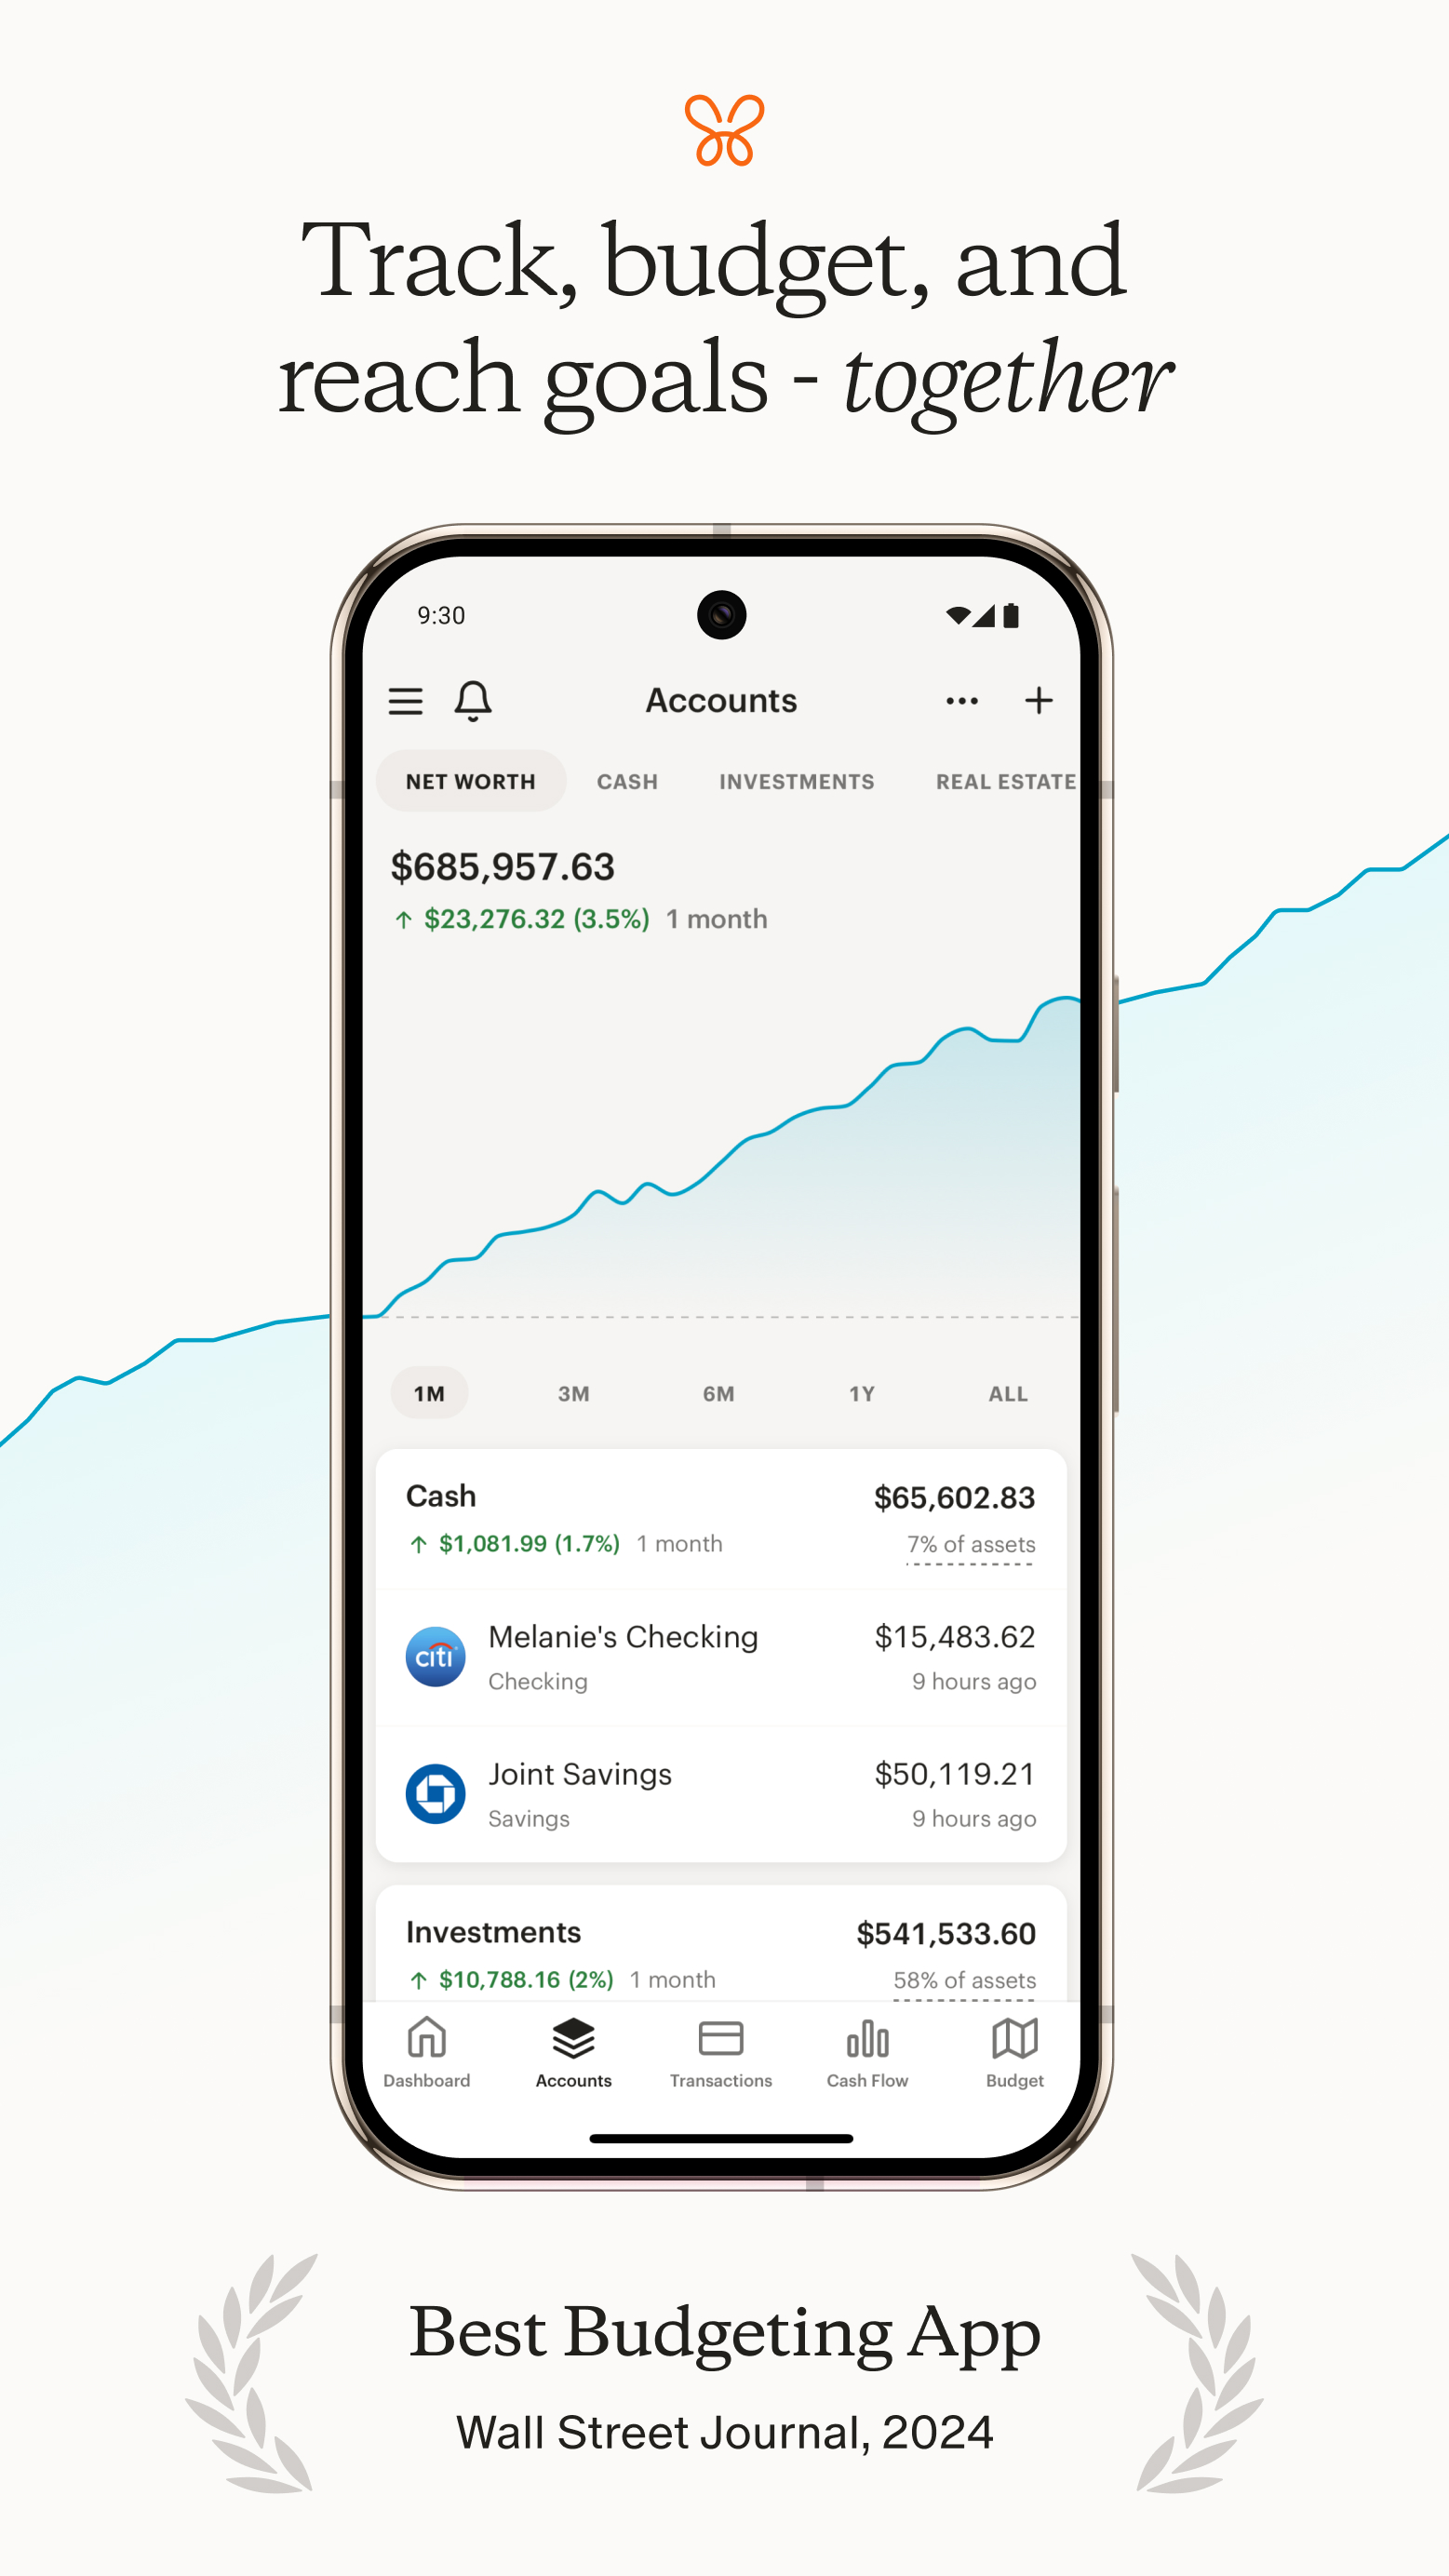
Tracking money is the systematic process of recording every dollar that enters and leaves your possession to gain a clear picture of your financial health. In 2026, this involves using automated digital tools, synchronized banking APIs, or manual ledgers to categorize spending, monitor income trends, and ensure that your daily financial decisions align with your long-term wealth goals.
Effective money tracking is the foundation of financial literacy. Without a clear record of where your capital originates and where it is deployed, creating a functional budget or investment strategy is nearly impossible. Whether you are trying to climb out of debt, save for a primary residence, or optimize a high-net-worth portfolio, the principles of cash flow transparency remain the same.
The Core Philosophy of Tracking Money
Tracking money is often confused with budgeting, but the two are distinct functions. Budgeting is a forward-looking plan—a map of where you intend your money to go. Tracking is the backward-looking verification—the record of where your money actually went. By 2026, the integration of financial technology has made it easier than ever to see these two functions side-by-side.
The primary goal of tracking is to eliminate "financial leakage." This refers to small, recurring, or unconscious expenses that provide little value but cumulatively erode your savings. When you track money, you transform abstract numbers on a screen into concrete data points that reveal your true priorities and habits.
Choosing Your Tracking Methodology
Before you record a single transaction, you must choose a method that fits your personality and technical comfort level. There is no "perfect" system; the best method is the one you will actually use consistently.
Automated Digital Tracking
In 2026, most consumers opt for automated solutions. These tools connect directly to your bank accounts and credit cards via secure protocols like OAuth 2.0.
- Pros: Requires minimal time; provides real-time updates; generates visual reports and charts automatically.
- Cons: Can lead to "passive" tracking where the user ignores the data; occasional sync errors with smaller credit unions.
- Security: Modern apps use SOC 2 Type II compliance to ensure that your financial data is encrypted and handled according to strict privacy standards.
Manual Entry (The Spreadsheet Method)
Many financial experts still recommend manual entry for those who struggle with overspending. Using software like Microsoft Excel or Google Sheets requires you to touch every transaction.
- Pros: High level of intentionality; full control over categories; no subscription fees; maximum privacy.
- Cons: Time-consuming; prone to human error; difficult to maintain on mobile devices.
The Cash-Based Envelope System
For those focused on strict debt reduction, the physical or digital envelope system remains a gold standard. You allocate a specific amount of money to "envelopes" (categories) and stop spending once the envelope is empty.
- Pros: Prevents overspending entirely; creates a psychological barrier to waste.
- Cons: Difficult to use for online subscriptions or utility bills; physical cash can be lost or stolen.
Step-by-Step Implementation Guide
To track money effectively in 2026, follow this structured approach to ensure no transaction is missed and every data point is useful.
1. Centralize Your Financial Data
Start by listing every account where money flows. This includes checking accounts, high-yield savings accounts, credit cards, digital wallets (like PayPal or Apple Pay), and investment brokerages. If you use multiple institutions, a central aggregator is essential. According to the Consumer Financial Protection Bureau (CFPB), maintaining a consolidated view of your accounts is a key step in preventing fraud and managing liquidity.
2. Define Granular Categories
Vague categories like "Miscellaneous" are the enemies of effective tracking. Instead, create specific categories that allow for actionable analysis:
- Fixed Needs: Rent/Mortgage, Utilities, Insurance, Minimum Debt Payments.
- Variable Needs: Groceries, Transportation, Healthcare.
- Wants/Lifestyle: Dining out, Subscriptions (Streaming/Gym), Hobbies.
- Financial Goals: Retirement contributions, Emergency fund, Sinking funds for travel.
3. Establish a Review Cadence
Tracking is useless if you don't look at the data. In 2026, a tiered review system is most effective:
- Daily: A 2-minute "sweep" to categorize any new transactions and check for unauthorized charges.
- Weekly: A 15-minute review to see if you are staying within your weekly spending limits.
- Monthly: A comprehensive deep dive to analyze trends, adjust categories, and calculate your savings rate.
Advanced Tracking: Net Worth and Investment Performance
Once you have mastered tracking your daily expenses (cash flow), the next step is tracking your overall wealth, known as Net Worth. This is calculated by subtracting your total liabilities (what you owe) from your total assets (what you own).
In 2026, tracking net worth is vital because of asset volatility. You should track:
- Liquid Assets: Cash and equivalents.
- Invested Assets: Stocks, bonds, and retirement accounts.
- Use Assets: Real estate and vehicles (using conservative valuations).
- Liabilities: Student loans, mortgages, and consumer debt.
Tracking these metrics over time allows you to see the "big picture." Even if you have a high-spending month, your net worth may still increase if your investments perform well or if you are paying down the principal on a mortgage.
Comparison of Tracking Tools and Methods
The following table compares the most common ways to track money in 2026 based on effort, cost, and effectiveness.
| Method | Effort Level | Cost (2026 Avg) | Best For | Security Level |
|---|---|---|---|---|
| Mobile Apps | Low (Automated) | $5–$15/month | Busy professionals | High (Encrypted) |
| Spreadsheets | High (Manual) | Free - $100/year | Data enthusiasts | Medium (Local/Cloud) |
| Banking Portals | Medium | Free | Single-bank users | Very High |
| Envelope System | Very High | Free | Debt reduction | Low (Physical Cash) |
| AI Assistants | Very Low | Variable | Trend analysis | High (API-based) |
Common Mistakes When Tracking Money
Even with the best tools, several pitfalls can undermine your efforts.
- Forgetting "Ghost" Subscriptions: Many people forget to track automated renewals. In 2026, the average household manages over 10 different subscriptions. Ensure these are logged as recurring expenses.
- Ignoring Cash Transactions: While rare in 2026, small cash tips or purchases often go unrecorded, leading to a "leak" in your data.
- Lack of Reconciliation: If your tracking software says you have $500 but your bank account says $450, you must find the $50 discrepancy. Without reconciliation, your data becomes untrustworthy.
- Being Too Critical: The goal of tracking is awareness, not punishment. If you overspend in one category, record it honestly and adjust your plan for the next month rather than stopping the tracking process altogether.
Troubleshooting Technical Issues
In 2026, most tracking issues are technical rather than manual. If your accounts fail to sync:
- Update Permissions: Banks frequently update their security protocols. You may need to re-authenticate your connection via your bank's mobile app.
- Check for "Pending" Transactions: Most tracking software waits for a transaction to clear before final categorization. This can cause a 24-48 hour delay.
- Verify Multi-Factor Authentication (MFA): If you have MFA enabled (which is highly recommended), some aggregators may struggle to pull data without a fresh token.
Frequently Asked Questions
How often should I manually track my expenses?
While automated tools handle the bulk of the work, you should manually review and categorize your expenses at least once a week. This ensures that the AI hasn't miscategorized a purchase—for example, marking a grocery store purchase as "Pharmacy" just because the store has a pharmacy inside. Weekly reviews keep the data fresh in your mind and allow you to pivot your spending before the month ends.
Is it safe to link my bank account to tracking apps in 2026?
Yes, provided you use reputable services that utilize read-only access. Modern financial APIs do not share your login credentials with the app; instead, they provide a secure "token" that allows the app to see transaction history without having the power to move money. Always look for apps that offer two-factor authentication and have clear data-deletion policies.
Should I track my partner's spending as well?
If you share finances or a household budget, tracking must be a collaborative effort. Many apps in 2026 offer "household" or "joint" views where both partners can see the same data pool. If you keep finances separate, you should still track your individual contributions to shared expenses (like rent or utilities) to ensure an equitable distribution of costs.
What is the "50/30/20" rule in the context of tracking?
The 50/30/20 rule is a framework used to analyze your tracked data. It suggests that 50% of your income should go to "Needs," 30% to "Wants," and 20% to "Savings and Debt Repayment." Tracking allows you to see exactly what percentage of your income is currently hitting these buckets, which informs whether you need to cut lifestyle spending or find ways to reduce fixed costs.
Can I track money without using any digital tools?
Yes, you can use a physical ledger or "Kakeibo," a traditional Japanese method of financial management. This involves writing down every purchase in a notebook and reflecting on your spending at the end of each month. While slower, this method provides the highest level of psychological engagement with your money, which can be very effective for changing long-term habits.
Final Recommendation for 2026
To achieve the best results, adopt a hybrid approach. Use an automated app to aggregate your data and handle the "heavy lifting" of data entry, but perform a manual weekly "check-in" to review categories and reflect on your spending. This combination provides the efficiency of modern technology with the intentionality of traditional bookkeeping. Start today by choosing one primary account to track, and once you are comfortable, expand to your entire financial ecosystem.