Securing boat finance involves obtaining a specialized marine loan from a bank, credit union, or dedicated marine lender to purchase a watercraft, requiring a thorough understanding of down payments, credit profiles, loan terms, and specialized vessel documentation.
Purchasing a boat is a significant financial commitment that often mirrors the complexity of buying a home or an automobile. Unlike standard consumer purchases, acquiring a watercraft typically requires specialized financing structures known as marine loans. Whether you are looking at a sleek bowrider for weekend recreation, a center console for coastal fishing, or a luxury yacht for extended cruising, understanding how boat finance works is essential to securing favorable terms and avoiding costly pitfalls.
The marine lending market possesses unique characteristics. Lenders evaluate risks differently for recreational vessels compared to other assets, taking into account depreciation rates, maintenance costs, and whether the boat will be used as a primary residence, a seasonal recreational item, or a charter business. Navigating this landscape requires a firm grasp of credit requirements, down payment structures, term lengths, and the legal nuances of marine titling and documentation.
Understanding Marine Loans and How They Work
Marine loans are specialized financial products specifically designed for the purchase of watercraft. While it is sometimes possible to use unsecured personal loans or home equity lines of credit (HELOCs) to buy a boat, traditional marine loans are secured installment loans where the boat itself serves as collateral. This means that if the borrower defaults on the loan, the lender has the legal right to repossess the vessel to recover the remaining debt.
Unlike unsecured loans, which rely solely on the borrower’s credit score and income, secured marine loans allow lenders to offer higher loan amounts and longer repayment terms because the physical asset mitigates some of their risk. However, this also means the underwriting process is more rigorous. Lenders will evaluate not only the financial health of the borrower but also the make, model, age, and condition of the boat being purchased.
Secured vs. Unsecured Financing
Choosing between a secured marine loan and other forms of borrowing depends heavily on the buyer's financial situation and the size of the purchase:
- Secured Marine Loans: Tied directly to the boat as collateral. Typically feature lower interest rates, higher borrowing limits, and extended repayment terms ranging from 10 to 20 years. These are the industry standard for purchases exceeding modest thresholds.
- Unsecured Personal Loans: Do not require the boat as collateral. These are generally easier and faster to secure for smaller watercraft, such as personal watercraft (PWAs) or small aluminum fishing boats. However, they carry significantly higher interest rates and shorter repayment windows, usually capped at 5 to 7 years.
- Home Equity Loans and HELOCs: Borrowers with substantial home equity may leverage their property to finance a boat. While interest rates can be attractive and potentially tax-deductible (depending on current tax laws and how the funds are classified), this approach puts the primary residence at risk if loan payments cannot be met.
Key Requirements and Qualification Criteria
Qualifying for a boat loan requires meeting specific financial benchmarks established by lenders to minimize default risk. Because boats are categorized as discretionary luxury items rather than absolute necessities, marine lenders exercise strict underwriting standards, particularly during economic downturns.
Credit Score Thresholds
Credit history is a primary determinant of loan approval and interest rate pricing.
- Prime Borrowers: Credit scores of 740 and above generally unlock the most competitive interest rates, lowest down payment requirements, and flexible terms.
- Near-Prime Borrowers: Scores ranging from 680 to 739 are widely accepted by mainstream marine lenders, though interest rates will reflect a moderate risk premium.
- Sub-Prime Borrowers: Scores below 680 face restricted options, requiring larger down payments (often 30% or more), co-signers, or specialized secondary lenders that charge substantially higher interest rates.
Debt-to-Income (DTI) Ratio
Lenders examine the debt-to-income ratio to ensure the borrower has sufficient cash flow to manage the new monthly payment alongside existing financial obligations. Most marine lenders prefer a total DTI ratio below 43%, though exceptional credit profiles and substantial liquid assets can occasionally accommodate higher ratios.
Down Payments and Equity
Unlike automotive loans where zero-down offers are common, marine financing almost universally requires a down payment.
- Standard Requirements: Down payments typically range from 10% to 20% of the purchase price for new or late-model recreational boats.
- Older or Specialty Vessels: For older boats (typically more than 10 to 15 years old), wooden boats, or high-performance vessels, lenders may require 20% to 30% down to account for rapid depreciation and higher maintenance risks.
Loan Terms, Structures, and Financial Costs
Understanding the mechanics of marine loan pricing helps buyers structure a budget that accounts for both the initial acquisition and long-term ownership costs.
Loan Amortization and Term Lengths
Marine loans are typically structured as fixed-rate installment loans with monthly payments amortized over a set period. Standard loan terms range from 5 to 20 years, depending on the loan balance:
- Loans under $25,000: Terms usually span 5 to 10 years.
- Loans between $25,000 and $100,000: Terms frequently range from 10 to 15 years.
- Loans over $100,000 (Luxury and Yacht Financing): Terms can extend up to 20 years, mirroring mortgage structures.
While longer loan terms reduce monthly payments, they significantly increase the total interest paid over the life of the loan. Buyers must weigh monthly cash flow comfort against the cumulative cost of borrowing.
Comparative Overview of Marine Financing Structures
| Financing Type | Typical Loan Amount | Average Term Length | Down Payment Required | Primary Risk / Consideration |
|---|---|---|---|---|
| Secured Marine Loan | $25,000 to $1,000,000+ | 10 to 20 Years | 10% to 20% | Vessel acts as collateral; subject to strict marine survey. |
| Unsecured Personal Loan | $5,000 to $50,000 | 3 to 7 Years | 0% (None) | Significantly higher interest rates; shorter repayment windows. |
| Home Equity Line (HELOC) | Varies by equity | 10 to 15 Years | Based on home equity | Puts primary residential property at direct risk of foreclosure. |
| Dealer/In-House Financing | Varies | 5 to 15 Years | 10% to 20% | Convenience comes with potential for higher markups or dealer fees. |
The Boat Financing Process: Step-by-Step
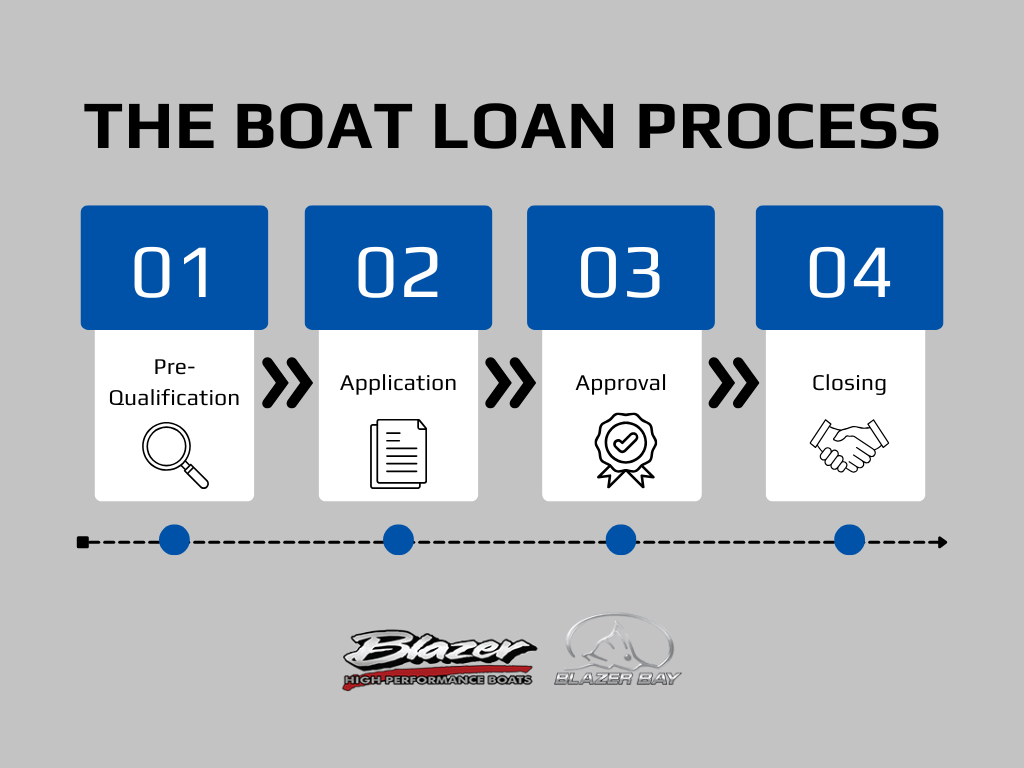
Securing boat finance involves a structured sequence of milestones, moving from initial budget planning to final loan disbursement and vessel registration.
- Determine Your Budget and Total Cost of Ownership: Calculate what you can comfortably afford, remembering that boat ownership includes recurring expenses beyond the loan payment, such as slip rentals, winterization, insurance, routine maintenance, and fuel.
- Check Your Credit and Financial Profile: Review your credit report for errors, pay down revolving debt to lower your DTI ratio, and gather financial documentation (tax returns, W-2s, bank statements).
- Get Pre-Approved: Contact dedicated marine lenders or credit unions to secure a pre-approval letter. Pre-approval establishes your precise purchasing budget and signals to sellers that you are a serious, qualified buyer.
- Select the Vessel and Complete a Marine Survey: Once you find a boat, make an offer contingent on a professional marine survey and a mechanical inspection. For financed boats, lenders often require an independent marine survey to verify the vessel's fair market value and structural integrity.
- Finalize Loan Underwriting: Submit the accepted purchase agreement, marine survey, and vessel identification details to your lender. The lender will review the paperwork, verify insurance binder compliance, and issue final loan documents.
- Closing and Documentation: Sign the final loan agreement, pay your down payment and closing fees, and complete state registration or U.S. Coast Guard documentation.
Hidden Costs and Ongoing Expenses of Boat Ownership
When budgeting for boat finance, focusing solely on the monthly principal and interest payment is a common and costly mistake. True boat ownership involves several secondary and ongoing financial obligations that must be integrated into your personal finance plan.
- Marine Insurance: Unlike auto insurance, which is straightforward, marine insurance premiums vary widely based on the vessel's value, navigational territory, engine horsepower, and the owner’s boating experience. Lenders mandate comprehensive insurance coverage and will require proof of a binder before releasing funds.
- Surveys and Appraisals: Prior to loan approval, buyers frequently pay out-of-pocket for a marine surveyor to inspect the hull, electrical systems, and electronics. These evaluations cost hundreds or thousands of dollars depending on the size of the boat.
- Storage and Mooring: Whether keeping the boat in a wet slip at a marina, on a rack in dry stack storage, or on a trailer in your driveway, storage fees consume a substantial portion of annual operating costs.
- Maintenance and Winterization: Industry rules of thumb suggest budgeting roughly 10% of the boat’s purchase price annually for routine maintenance, repairs, bottom painting, and seasonal winterization.
Common Mistakes to Avoid in Boat Finance
Navigating the marine lending market successfully requires avoiding several frequent missteps made by first-time and experienced buyers alike.
- Failing to Get Pre-Approved First: Shopping for a boat without a pre-approval leaves you at the mercy of dealership financing, which may not offer the most competitive rates.
- Neglecting the Age and Type Restrictions: Many lenders refuse to finance boats older than 15 or 20 years, or they impose restrictions on specific hull materials (like older wood or specific fiberglass configurations). Always verify lender parameters before falling in love with a classic vessel.
- Ignoring Prepayment Penalties: Some marine loans carry penalties if you pay off the principal balance early. Always review loan contracts for clauses restricting early payoff.
- Underestimating Depreciation: Boats depreciate faster than real estate and often faster than standard automobiles. Ensure your down payment is large enough that you do not immediately find yourself "upside down" (owing more on the loan than the boat is worth).
Frequently Asked Questions About Boat Finance
Can I finance a used boat, or are loans only for brand-new models?
Yes, you can finance used boats, but the age of the vessel directly impacts the terms. Most lenders finance used boats up to 10, 15, or even 20 years old. However, older boats generally require higher down payments, shorter loan repayment terms, and mandatory marine surveys to verify their current market value.
What is the typical down payment required for a marine loan?
Most marine lenders require a down payment ranging from 10% to 20% of the purchase price. Buyers with exceptional credit scores may occasionally qualify for 10% down, while higher-risk profiles, older vessels, or luxury yachts may necessitate down payments of 20% to 30%.
Do I need a marine survey to get a boat loan?
Lenders almost universally require a professional marine survey for financed used boats, particularly those over a certain age (often 10 years) or exceeding specific value thresholds (such as $50,000). The survey ensures the boat is worth the loan amount and is structurally sound enough to serve as adequate collateral.
Can I finance a boat through a dealership, or should I use an independent lender?
You can do both. Dealerships often partner with multiple marine lenders and can provide convenient, point-of-sale financing. However, it is always wise to compare dealer offers against pre-approved rates from independent banks, credit unions, or specialized marine finance brokers to ensure you secure the most competitive interest rate and terms.
Conclusion and Next Actions
Securing boat finance requires a balanced approach that pairs realistic budgeting with careful lender selection. Before stepping onto a sales lot or browsing online marketplaces, pull your credit report, determine your maximum comfortable monthly payment, and seek pre-approval from a reputable marine lender or credit union. By accounting for hidden costs like insurance, surveys, and seasonal storage, you can protect your financial health while pursuing your passion on the water.