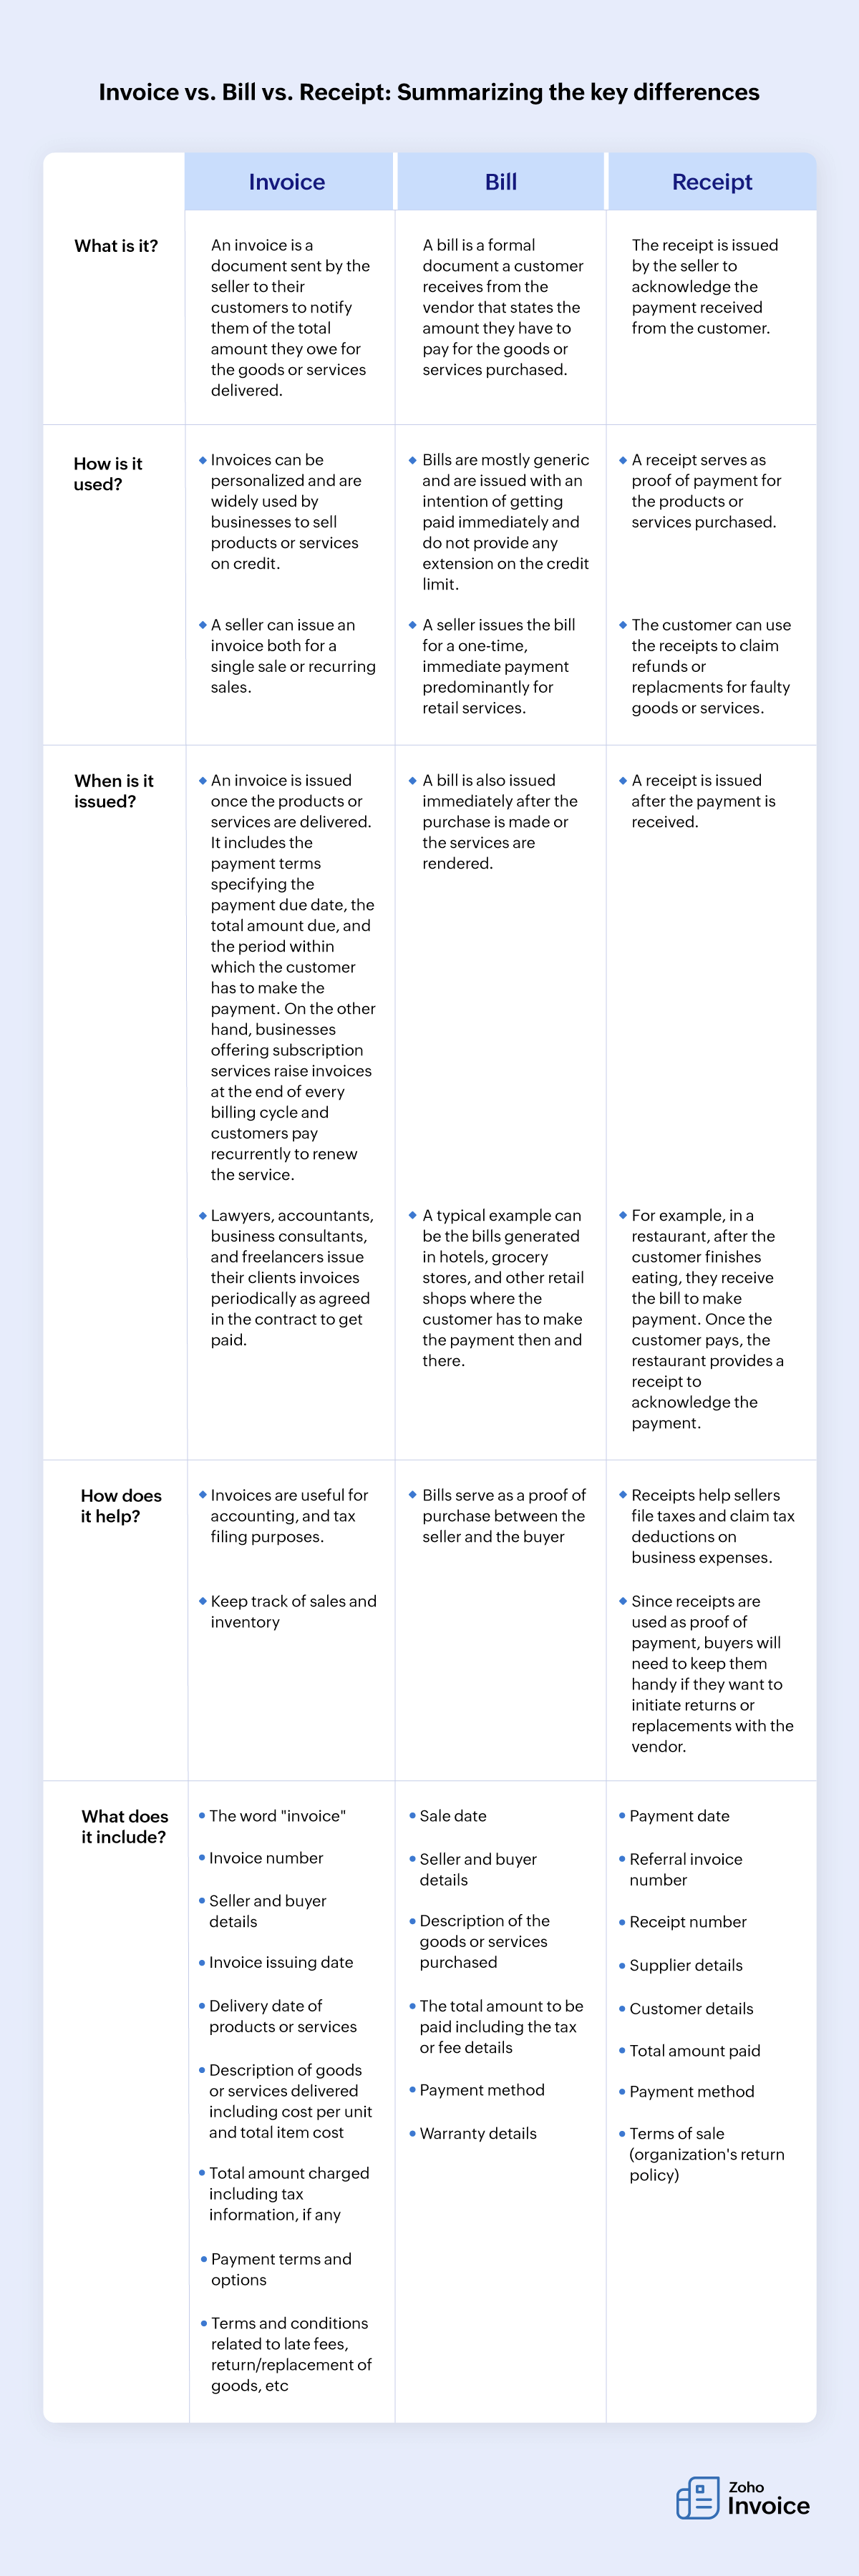
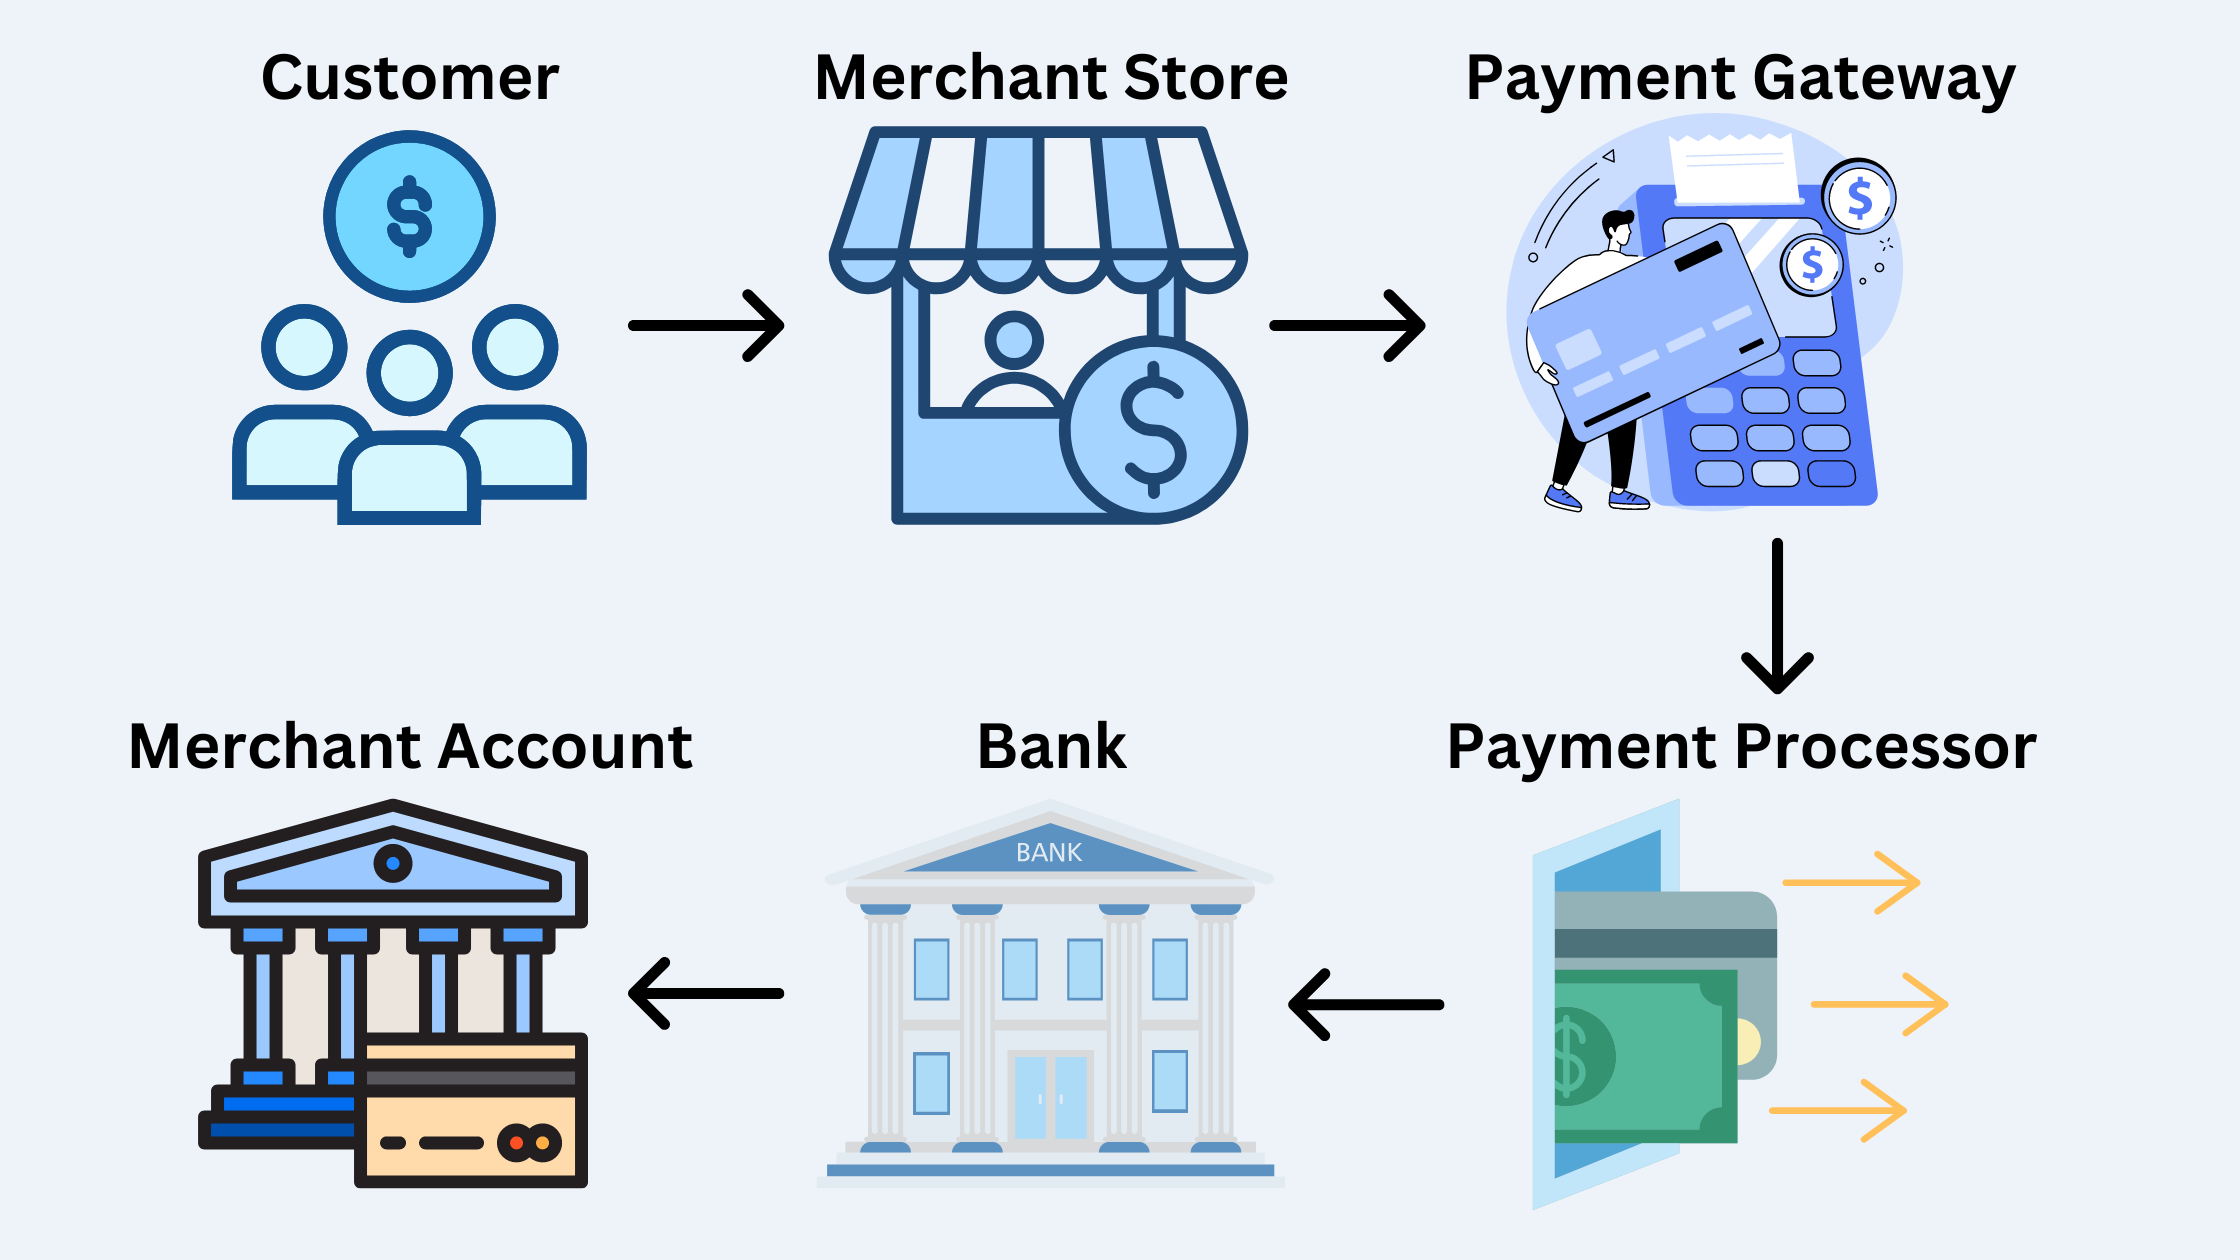
When managing personal finances, choosing between traditional direct bill pay options and dedicated banking bill pay services significantly impacts how efficiently you handle monthly obligations. While the terms sound interchangeable, they represent distinct mechanisms for moving money from your account to a service provider, each carrying unique advantages, security implications, and processing speeds.
Defining the Core Concepts: What Are "Vs Bill Pay" and Online Banking Bill Pay?
To understand the mechanics of electronic payments, it is helpful to look at how modern financial technology manages recurring obligations. In the broader financial ecosystem, "bill pay" generally refers to any method used to settle a debt or recurring invoice electronically. However, consumer banking searches often contrast two specific routing methods: merchant-initiated automatic withdrawals and bank-initiated payment services.
When people evaluate these payment models, they are typically weighing the security and control of pushing payments through their financial institution against the convenience of pulling payments directly from a merchant portal. Making the right choice requires examining how each system operates behind the scenes, how long transactions take to clear, and what recourse you have if an error occurs.
The Mechanics of Bank Bill Pay (The "Push" Method)
Bank bill pay is a service provided directly by your credit union or commercial bank through online banking or a mobile application. This model operates on a "push" payment structure. You, the account holder, log into your banking dashboard, input your biller’s account details and mailing address, and instruct your bank to send a specific amount of money on a designated date.
Depending on the biller's electronic capabilities, your bank fulfills this request in one of two ways:
- Electronic Transmission (ACH/EFT): The bank routes the funds electronically through automated clearing house networks or direct electronic data interchange, usually arriving within one to two business days.
- Physical Check Generation: If the merchant does not accept electronic transfers, the bank prints a physical paper check and mails it via the United States Postal Service to the biller’s payment processing center. This method can take up to five business days.
The Mechanics of Merchant Bill Pay (The "Pull" Method)
In contrast, merchant-initiated bill pay—often called auto-pay or direct debit—operates on a "pull" payment structure. You visit the utility company, credit card issuer, or mortgage lender's website, input your checking account routing number and account number, and authorize that organization to withdraw funds directly from your account each month.
Under this setup, the merchant triggers the transaction on the due date. Your bank simply honors the incoming automated clearing house (ACH) withdrawal request, provided sufficient funds are available in your account.
Comparative Analysis: Bank Bill Pay vs. Merchant Bill Pay
Evaluating these two payment modalities across critical operational vectors highlights why consumers choose one over the other depending on the specific bill being paid.
| Feature / Factor | Bank Bill Pay (Push) | Merchant Bill Pay / Auto-Pay (Pull) |
|---|---|---|
| Control Over Timing | High. You schedule exact disbursement dates directly from your dashboard. | Moderate. The merchant dictates when the withdrawal hits your account. |
| Data Security Exposure | Low. Your bank account details are shared only with your financial institution. | Higher. Your routing and account numbers are stored across multiple vendor portals. |
| Processing Speed | Variable (1 to 5 business days depending on electronic vs. paper check). | Typically fast and synchronized with the billing cycle due date. |
| Overdraft Risk | Lower, because you manually control execution or calendar reminders. | Higher, if billing amounts fluctuate unexpectedly and deplete balances. |
| Fee Vulnerability | Rarely incurs bank fees, but watch for rushed check delivery charges. | Rarely incurs direct fees, but bank overdraft or insufficient funds fees can apply. |
Security, Privacy, and Risk Management
One of the most consequential differences between these two payment methods lies in data exposure and vulnerability to third-party data breaches.
Minimizing Data Footprint with Bank Bill Pay
When you use your bank's bill pay system, you provide sensitive banking credentials—your checking account number and bank routing number—to a single entity: your financial institution. The biller receives either an electronic payment routed through secure banking networks or a physical check printed by your bank. The merchant never stores your core bank account numbers in their customer database. This isolation significantly reduces your exposure if a utility company, insurance provider, or subscription service suffers a data breach.
Convenience Versus Exposure with Merchant Portals
Setting up auto-pay directly with a merchant requires handing over your banking details directly to that company. While reputable enterprises utilize secure encryption standards to store this information, every additional database containing your financial identifiers represents a potential security vector.
Furthermore, managing dozens of active merchant auto-pay agreements can become difficult. If you change banks, get a new checking account, or close a debit card, you must manually update your payment credentials across every individual merchant portal. Conversely, updating your account details in a bank bill pay portal centralizes your changes in one secure dashboard.
Financial Control, Budgeting, and Cash Flow Management
Maintaining precise control over cash flow is essential for avoiding overdraft fees and maintaining financial stability. The structural differences between push and pull payments directly influence how easily you can manage your monthly budget.
Avoiding Variable Amount Surprises
Utility bills, credit card balances, and medical expenses fluctuate from month to month. If you enroll in full-balance auto-pay with a merchant, an unexpectedly high bill can unexpectedly drain your checking account, triggering cascading insufficient funds fees.
Using bank bill pay introduces a deliberate speed bump into the process. Because you must log in or manually approve fixed or variable amounts each cycle, you review the invoice total before authorizing the push transaction. This mandatory touchpoint prevents automated systems from withdrawing more than you anticipate.
Handling Fixed Versus Variable Expenses
- Fixed Expenses (Mortgage, Car Loans, Insurance): These bills remain identical month after month. Merchant auto-pay is generally safe and efficient here because the withdrawal amount never surprises you.
- Variable Expenses (Utilities, Credit Cards, Variable Subscriptions): Bank bill pay or manual review models provide superior protection. They allow you to inspect the bill before releasing funds, ensuring your checking account remains comfortably cushioned.
Legal Protections and Dispute Resolution
When a payment error occurs—such as a duplicate charge, an incorrect billing amount, or a delayed processing fee—the mechanism you used to pay dictates how quickly and effectively you can resolve the issue.
Consumer Protections Under Regulation E
Electronic fund transfers in the United States are governed by the Electronic Fund Transfer Act (EFTA), commonly implemented via Regulation E. Under Reg E, consumers have specific rights regarding unauthorized or erroneous electronic withdrawals.
However, disputing an erroneous merchant-initiated withdrawal requires coordinating with both the merchant and your bank. If a merchant pulls an incorrect amount, you must first request a refund from the company. If they are uncooperative, you must file a formal dispute with your bank to stop future unauthorized debits and recover funds.
Bank Error Resolution Protocols
When using bank bill pay, your relationship is strictly with your financial institution. If your bank guarantees delivery by a certain date and fails to deliver—resulting in a late fee from your utility provider—most major banks maintain guarantees that reimburse late fees if the error originates on their end. Investigating delayed or misrouted payments is often streamlined because the audit trail resides entirely within your bank’s internal transaction logs.
Step-by-Step Guide: Setting Up and Managing Bank Bill Pay
Transitioning your recurring obligations to a bank-managed payment schedule requires careful setup to ensure zero disruptions in service. Follow this structured approach to transition smoothly:
- Audit Your Current Obligations: Gather your last three months of bank statements to identify every recurring bill, noting whether the amount is fixed or variable.
- Log Into Online Banking: Navigate to the "Bill Pay" or "Payments" tab within your secure mobile app or desktop banking portal.
- Add Payees: Enter the exact name, billing address, and account number found on your physical or digital statement for each service provider. Double-check account numbers to prevent misrouted funds.
- Determine Delivery Lead Times: Note your bank's estimated processing times for each payee. Set scheduled payment dates at least three to five business days before the actual due date to account for mail delivery or processing lags.
- Establish Calendared Reviews: Even when utilizing automated bank bill pay rules, set a monthly calendar reminder to review upcoming disbursements against your available account balance.
Frequently Asked Questions
Is bank bill pay completely free?
For the vast majority of consumer checking accounts, standard electronic and paper check bill pay services are provided at no additional cost. However, some financial institutions charge fees for expedited overnight check delivery or wire transfers. Always review your bank's fee schedule.
What happens if my bank bill pay check arrives late?
Most major financial institutions offer a bill pay guarantee. If you scheduled the payment with adequate lead time according to their stated guidelines and the check arrived late due to bank error, the bank typically reimburses resulting late fees and finance charges. You will need to provide documentation from the biller.
Can I cancel a bank bill pay transaction after scheduling it?
Yes. As long as the status of the payment in your online banking dashboard reads "Pending" or "Scheduled," you can cancel or modify the transaction. Once the status changes to "Processed" or "Paid," the funds have left your control and cannot be recalled via the bill pay interface.
Is merchant auto-pay safer for credit scores?
Merchant auto-pay reduces the risk of missed payments due to human forgetfulness, which protects your credit score from late-payment marks. However, safety depends entirely on maintaining adequate funds in your account to prevent accidental overdrafts and returned payments.
How do I switch existing auto-pay services to bank bill pay?
To switch, first log into the merchant's customer portal and cancel your existing auto-pay or stored banking information. Next, log into your bank's bill pay system, add the merchant as a payee, and schedule your desired recurring or manual payment instructions.
Conclusion and Next Actions
Choosing between merchant-initiated bill pay and bank-managed bill pay depends on your priorities regarding convenience, budgeting vigilance, and data security. If you prefer automated, hands-off management for fixed-cost bills, merchant auto-pay offers seamless execution. If you value centralized data security, precise control over variable cash flow, and reduced exposure to data breaches, utilizing your bank's push bill pay service is the superior strategic choice. Audit your current monthly recurring expenses today, identify accounts vulnerable to variable pricing, and migrate those payments to a secure bank bill pay framework to optimize your financial security.